
OSI Systems (OSIS) As New Contracts And Earnings Optimism Revive The Value Debate
Recent commentary around OSI Systems (OSIS) has focused on its value characteristics and earnings outlook, at a time when demand for its security screening and optoelectronic products is supported by new government contracts and sector investment.
At a share price of US$200.49, OSI Systems has seen short term share price momentum fade, with the 90 day share price return down 7.48% and the year to date share price return down 21.55%. However, the 5 year total shareholder return of 113.04% points to a much stronger long run record. This helps explain why fresh government security contracts and an upcoming quarterly results call are drawing renewed attention to the valuation story.
Spot opportunities with similar value characteristics by scanning our hand-picked list of 29 high quality undervalued stocks. These stocks share some of the same earnings and contract-driven themes as OSI Systems.OSI Systems looks like a solid operator in security and optoelectronics, yet the share price has slipped this year. Is that recent weakness giving you a genuine value entry, or just fair pricing catching up with reality?
Most Popular Narrative: 28% Undervalued
On the widely followed valuation narrative, OSI Systems screens as undervalued, with a fair value of $278.29 set against the last close at $200.49 and built off a detailed view of backlog, margins and earnings power.
The main factor that has to go right is that OSI Systems continues to grow higher margin Security, RF and service revenues while sustaining the recent margin improvement in Healthcare. This would allow the whole group to support structurally higher profitability on its existing contract base.
See why 5 investors see OSI Systems as 28% undervalued.
Result: Fair Value of $278.29 (UNDERVALUED)
Still, the OSI Systems narrative depends on Security revenues recovering from recent declines and on geopolitical delays not turning record backlog into slower and more uneven cash conversion.
Find out about the key risks to this OSI Systems narrative.
Another View: SWS DCF Says OSI Systems Is Overvalued
The story changes when you switch from analyst fair value to the SWS DCF model. On this framework, OSI Systems screens as expensive, with the current share price of $200.49 sitting well above an estimated future cash flow value of $80.22. That gap points to a very different risk profile for long term holders.
For readers who want to see how this cash flow based estimate is built step by step, Look into how the SWS DCF model arrives at its fair value.
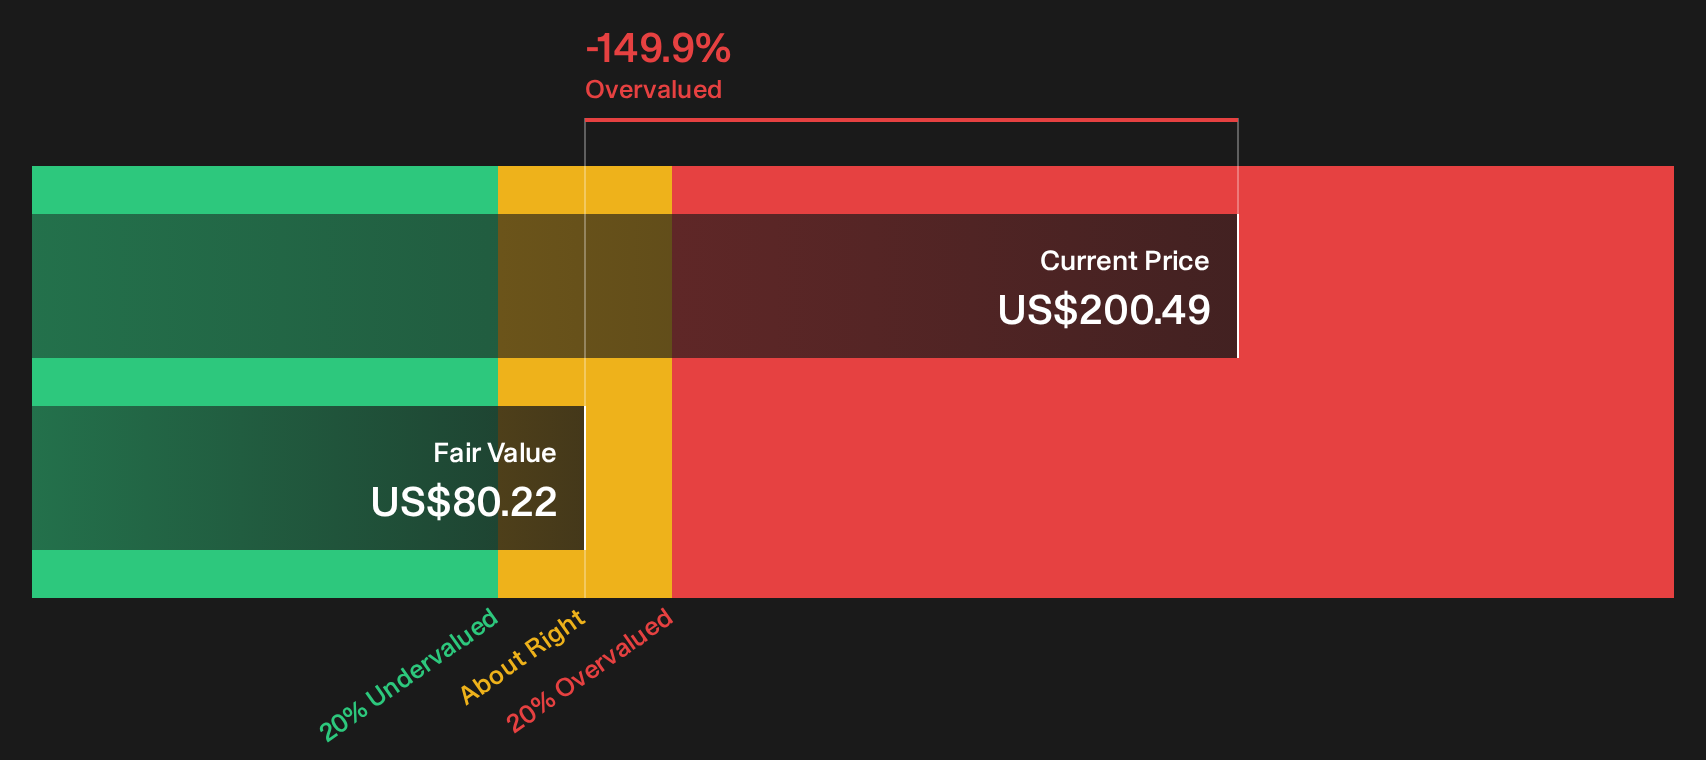
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OSI Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the OSI Systems story so far. If you want to move quickly and decide where you stand, weigh up the 5 key rewards and 1 important warning sign.
Looking for more OSI Systems style investment ideas?
If OSI Systems has you rethinking what value really looks like, it makes sense to widen the search using focused screeners built around concrete fundamentals.
- Target resilient compounding potential by scanning a 30 resilient stocks with low risk scores that prioritises balance sheet strength and lower historical risk profiles.
- Hunt for strong value candidates by reviewing a 29 high quality undervalued stocks filtered for quality fundamentals and appealing pricing metrics.
- Spot under-the-radar potential by checking a 20 high quality undiscovered gems of lesser known businesses that still show solid financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com