
California Water Service Group (CWT) Prices New Debt, Is The 12% Undervalued View Compelling?
California Water Service Group (CWT) has moved to reshape its balance sheet, pricing $275,000,000 in new debt across senior unsecured notes and first mortgage bonds in privately placed transactions disclosed on October 15, 2026.
Recent bond activity coincides with a mixed share price picture for California Water Service Group. The 1 day share price return is 3.55% and the year to date share price gain is 10.69%, while the 1 year total shareholder return has slipped 1.91% and the 5 year total shareholder return is down 13.02%. This suggests momentum has improved in the short term, but long term performance remains subdued.
Capitalize on California Water Service Group’s balance sheet reshaping by comparing it with a hand picked 30 resilient stocks with low risk scores that share resilient fundamentals and tempered risk profiles.California Water Service Group now trades at a discount to both analyst targets and an intrinsic estimate, even as it layers on fresh long dated debt. Is that pricing caution or opportunity?
Most Popular Narrative: 12% Undervalued
On the most followed view, California Water Service Group’s fair value sits at $53.75 against a last close of $47.54. This puts today’s balance sheet reshaping in the context of a stock trading below that narrative estimate while carrying a higher capital load.
Accelerating capital investment in water infrastructure and modernization is now backed by a roughly 11% 10 year growth capital CAGR and management expectations for nearly 12% rate base CAGR to around US$3.5b by 2028. This can support higher regulated revenue and earnings capacity for California Water Service Group.
See why 5 investors see California Water Service Group as 12% undervalued.
Result: Fair Value of $53.75 (UNDERVALUED)
Still, the California Water Service Group story can wobble if regulators take a tougher line on PFAS cost recovery, or if new Nexus and BVRT territories underdeliver on earnings.
Find out about the key risks to this California Water Service Group narrative.
Another View: What Multiples Say About California Water Service Group
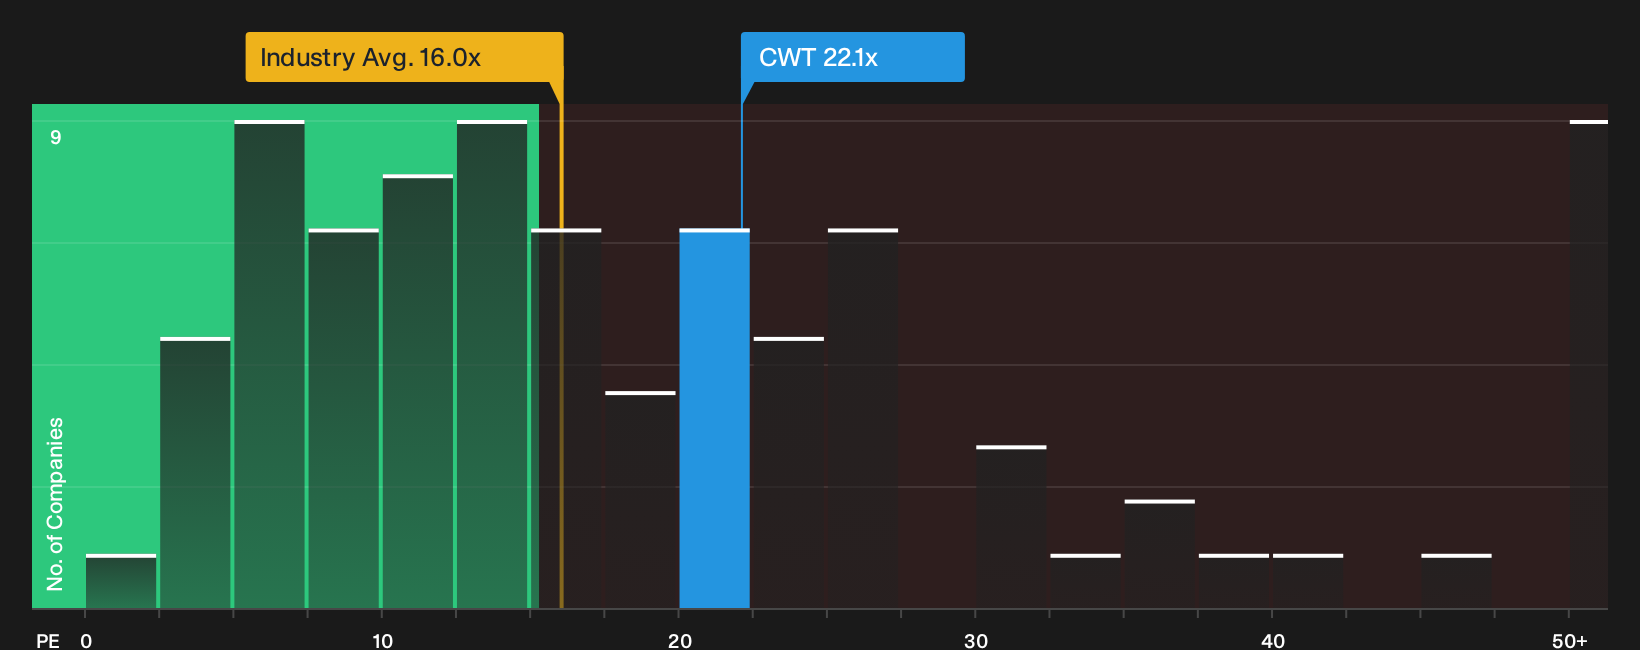
Analysts frame California Water Service Group as 12% undervalued against a fair value of $53.75, yet the current P/E ratio of 22.1x is richer than both the Global Water Utilities industry on 16.4x and the stock’s own fair ratio of 19.2x. That gap points to valuation risk if sentiment cools.
For investors comparing this pricing to other utilities, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around California Water Service Group can easily pull you in either direction. Consider acting promptly, review the data yourself, and weigh both the cautious and optimistic takeaways in the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond California Water Service Group?
If California Water Service Group has your attention, broaden your watchlist with fresh ideas that match your risk comfort, income goals, and value focus.
- Target resilient balance sheets and dependable fundamentals with a curated list of solid balance sheet and fundamentals (26 results) that keeps financial strength front and center.
- Hunt for mispriced opportunities by scanning a focused 29 high quality undervalued stocks tailored to investors who care about getting more value for every dollar.
- Lock in potential income streams by reviewing a high yield 6 dividend fortresses that highlights companies prioritizing shareholder payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com