
Is PDF Solutions (PDFS) Undervalued As Earnings Growth Comes Into Focus?
PDF Solutions (PDFS) is drawing attention ahead of its November 5 earnings release, with forecasts calling for quarterly EPS of $0.34 and revenue of $68.76 million compared with the same quarter last year.
Recent trading paints a mixed picture for PDF Solutions. The share price has fallen 10.3% over the past day and is down 22.6% over 3 months and 18.5% over 30 days. Yet year to date the share price return is still up 33.6%, and the 1 year total shareholder return, which includes reinvested dividends, sits at 44%. This suggests that enthusiasm has cooled in the short term even as longer term holders remain comfortably ahead.
Scan beyond PDF Solutions and compare what the market is pricing in for other potential earnings movers across our hand picked 29 high quality undervalued stocks in similar data and chip related businesses.
Bulls point to PDF Solutions' projected double digit earnings and revenue growth, while bears highlight the sharp pullback in the share price. Which story do the current valuation markers support?
Most Popular Narrative: 34% Undervalued
Compared with the last close at $39.47, the most followed narrative pegs fair value for PDF Solutions at $59.38. This frames today’s weakness against a higher long term earnings story built on recurring software and data platforms.
Accelerated enterprise adoption of PDF's secure, cloud-based supply chain orchestration and analytics solutions, including secureWISE, Sapience Manufacturing Hub, and Exensio, positions the company to capitalize on the industry's growing need for integrated data traceability and resilient manufacturing networks. This supports robust recurring revenue growth and higher earnings stability.
See why 13 investors see PDF Solutions as 34% undervalued.
Result: Fair Value of $59.38 (UNDERVALUED)
Still, the narrative around PDF Solutions can quickly wobble if US China export controls tighten further or if heavy R&D and capex fail to translate into profitable contracts.
Find out about the key risks to this PDF Solutions narrative.
Another Angle On PDF Solutions Valuation
The fair value narrative of $59.38 paints PDF Solutions as undervalued at $39.47, but the SWS DCF model tells a very different story. On that view, the future cash flow value lands at just $11.70, which frames the current share price as expensive rather than cheap. Which lens do you trust when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
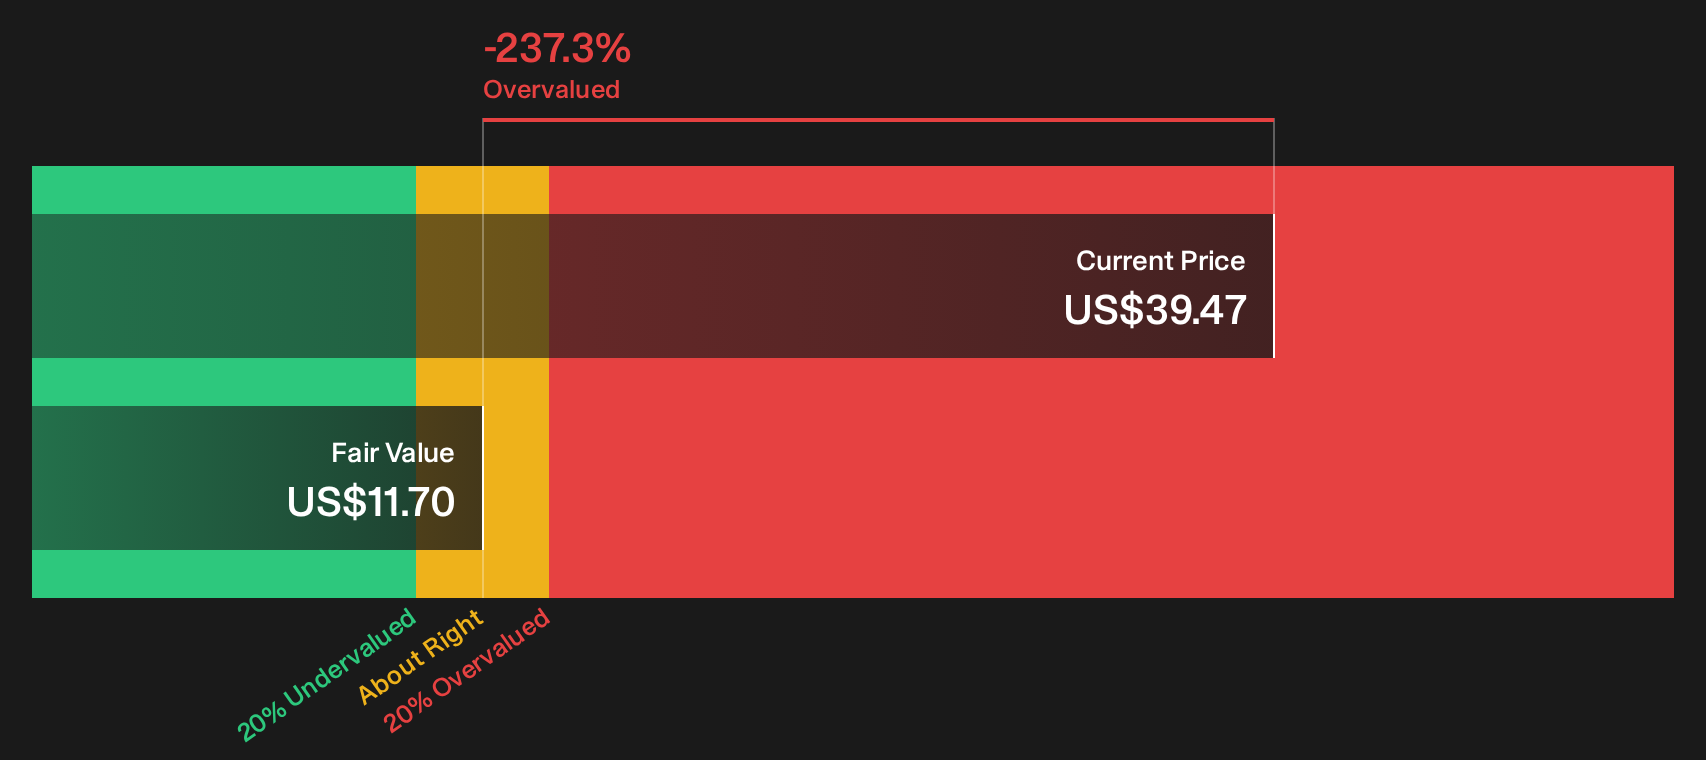
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PDF Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like these around PDF Solutions can pull you in opposite directions, so move quickly, review the numbers for yourself, then weigh up the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond PDF Solutions?
If PDF Solutions has your attention, do not stop here. Broaden your watchlist with a few focused idea lists that can surface very different opportunities.
Use these hand picked screeners to spot opportunities that match your risk appetite, instead of waiting for the next big story to pass you by.
- Scan for potential mispricings by reviewing a curated set of companies that currently screen as 29 high quality undervalued stocks.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (26 results) that can handle tougher conditions without stretching finances.
- Look beyond the mainstream by combing through a 20 high quality undiscovered gems that may not yet be widely followed by the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com