
Earnings Forecast Upgrade Might Change The Case For Investing In Swire Pacific (SEHK:19)
- Swire Pacific has recently attracted attention after analysts raised full year earnings expectations, with the Zacks Consensus Estimate for the current year increasing 42.4% alongside an anticipated 30.6% earnings growth.
- The sharp upgrade in profit forecasts highlights how Swire Pacific's diversified mix in property, aviation, and beverages is being reassessed for its earnings power rather than just its asset base.
- The next area of attention is how Swire Pacific's sharply upgraded earnings expectations could reshape the existing investment narrative around its core businesses.
Scan the market for other companies seeing sharp earnings upgrades by jumping into our curated list of 615 high quality undiscovered gems while you weigh what Swire Pacific's revised outlook could mean for your portfolio.
Swire Pacific Investment Narrative Recap
To be a shareholder in Swire Pacific, you need to be comfortable with a diversified group whose fortunes are tied to three big engines: property in Hong Kong and Mainland China, beverages across Asia, and aviation exposure through Cathay Pacific and HAECO. The short term swing factor remains the aviation cycle and travel demand, while office and retail leasing conditions sit in the background.
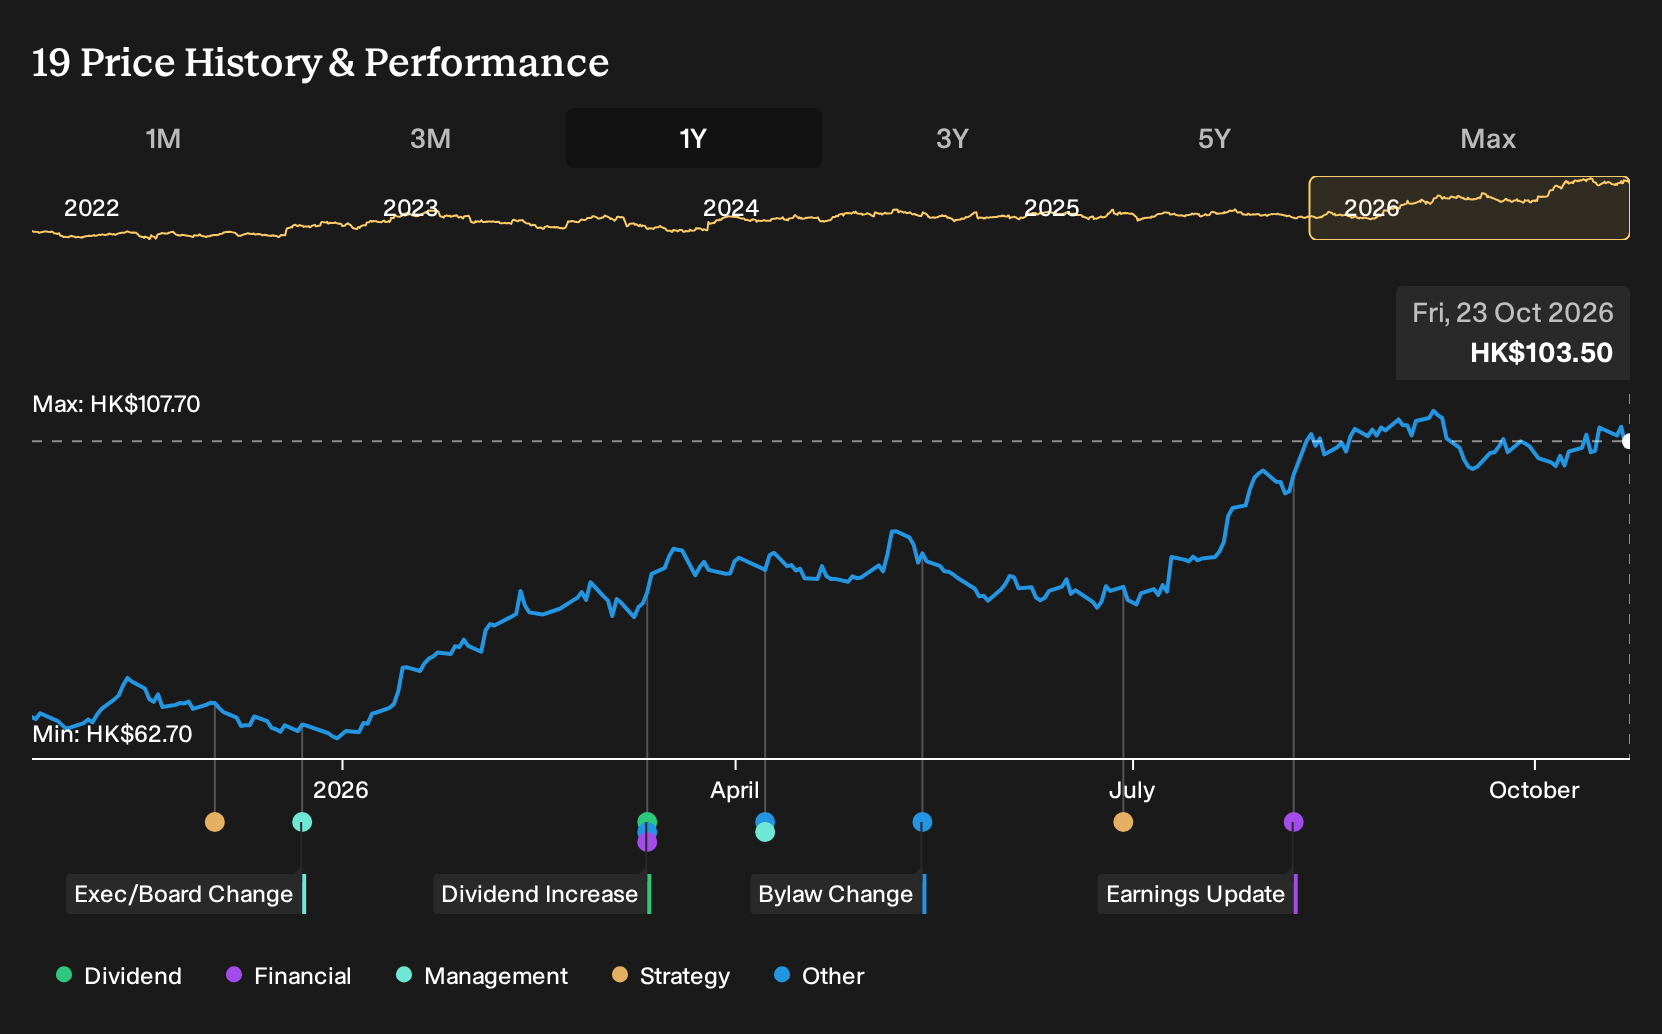
The recent 6.6% share price gain over four weeks and sharply higher earnings expectations focus attention on execution. If aviation or Mainland China projects underperform, the earnings mix could look less balanced. The biggest near term risk still comes from weaker office demand and higher funding costs affecting property values and returns.
The clearest recent datapoint linked to this story is the revised earnings outlook that points to 30.6% expected growth for the current year, together with a 42.4% uplift in the consensus earnings estimate over 60 days. For Swire Pacific, that frames how investors think about recovery in aviation, resilience in beverages, and rental income trends.
For catalysts, you are essentially watching whether that higher earnings base can be supported by cash flows from the HK$94.1b revenue pool and HK$8.9b of net income already reported. Any sign that Cathay Pacific, HAECO, or key Mainland China property assets are not contributing as implied by those upgraded forecasts would quickly test confidence in the current narrative.
What The New Earnings Path Implies For Swire Pacific
Swire Pacific's narrative projects HK$108.9b revenue and HK$15.0b earnings by 2029. This assumes 5.0% yearly revenue growth and an earnings increase of roughly 1.7x from HK$8.9b today.
Those headline figures give a rough sketch of what analysts think needs to happen. The revenue line is assumed to rise at 5.0% a year, which is not explosive. However, it sets the stage for earnings to step up more sharply if margins move from 9.4% today to 13.8% in three years. That shift in profitability is what turns HK$8.9b of earnings today into the HK$15.0b target that underpins many of the models on Swire Pacific.
On that profile, investors are not just being asked to accept higher profits. They are also being asked to accept a future P/E of 12.3x on those 2029 earnings, compared with 15.8x today and 6.4x for the wider Hong Kong industrials peer group. The forecast package of HK$108.9b in revenue and HK$15.0b in earnings essentially assumes that the market will still pay a premium multiple for Swire Pacific's mix of property, beverages, and aviation once those earnings arrive.
Valuation targets then fall out of those inputs. The analyst consensus price target sits at HK$105.46 against a current share price of HK$104.3, with individual targets spread between HK$92.0 on the cautious side and HK$118.0 at the top end. That 1.1% gap between today’s price and the central target suggests most forecasters see Swire Pacific as roughly in line with their fair value numbers. Any surprise in aviation cash flows, Mainland China property delivery, or beverage margins could have an outsized impact on how investors reassess the story.
Uncover why Swire Pacific's fair value aligns with its current price.
Exploring Other Perspectives
For Swire Pacific, the bullish twist comes from aviation as a potential upside swing factor. The most optimistic analysts were already pencilling in HK$115.7b of revenue and HK$15.3b of earnings by 2029, well above the consensus HK$108.9b and HK$15.0b. Those views were set before this earnings upgrade, so you may see them shift again as new information lands.
Explore another Swire Pacific fair value estimate, including one that suggests as much as 7% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Swire Pacific research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Swire Pacific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Swire Pacific's overall financial health at a glance.
Looking For More Ideas Beyond Swire Pacific?
If you want to stress test your view on Swire Pacific against other potential opportunities, it helps to scan a wider field of candidates that match clear financial filters.
- For investors who want upside potential without stretching on quality, review our 615 high quality undiscovered gems that combine stronger fundamentals with less crowded ownership.
- If capital preservation ranks high for you, focus on companies in our 221 resilient stocks with low risk scores that screen well on balance sheet strength and risk metrics.
- Income focused investors can concentrate their research on businesses in the 226 dividend fortresses that pair higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com