
BioNTech (BNTX) Tests Its Oncology Story As Fair Value Sits Higher
BioNTech (NasdaqGS:BNTX) is back in focus after a new collaboration with Gilead to test pumitamig alongside Trodelvy in first line triple negative breast cancer, adding to recent oncology trial updates.
Despite the new Gilead tie up and a stream of oncology updates, BioNTech’s recent trading tells a cautious story, with the share price down about 10.5% over the past month and the 1 year total shareholder return declining about 16.6%. This points to fading momentum as investors weigh pipeline progress against execution risk.
Scan BioNTech’s peers progressing in oncology and see which ones the market may be underestimating by reviewing our curated 29 high quality undervalued stocks.
BioNTech clearly has a deep oncology effort and fresh partnerships, yet the share price has retreated again. Is a complex, trial heavy pipeline now being valued fairly, or are investors paying too much for promise?
Most Popular Narrative: 24.5% Undervalued
Compared with BioNTech's last close of $88.12, the most followed narrative anchors fair value at $116.76, so the market gap is wide and the oncology pivot does much of the explaining.
Expansion of BioNTech’s late stage oncology pipeline, including pumitamig, gotistobart and multiple ADCs such as T PAM and elfetabart drozuntecan, increases the chance of future product approvals that could add new revenue streams and support earnings over time.
See why 71 investors see BioNTech as 25% undervalued.
Result: Fair Value of $116.76 (UNDERVALUED)
Still, the BioNTech story can crack if pumitamig stumbles in Phase III or if COVID 19 demand stays weak and oncology revenue fails to fill the gap.
Find out about the key risks to this BioNTech narrative.
Another View: What BioNTech’s P/S Ratio Implies
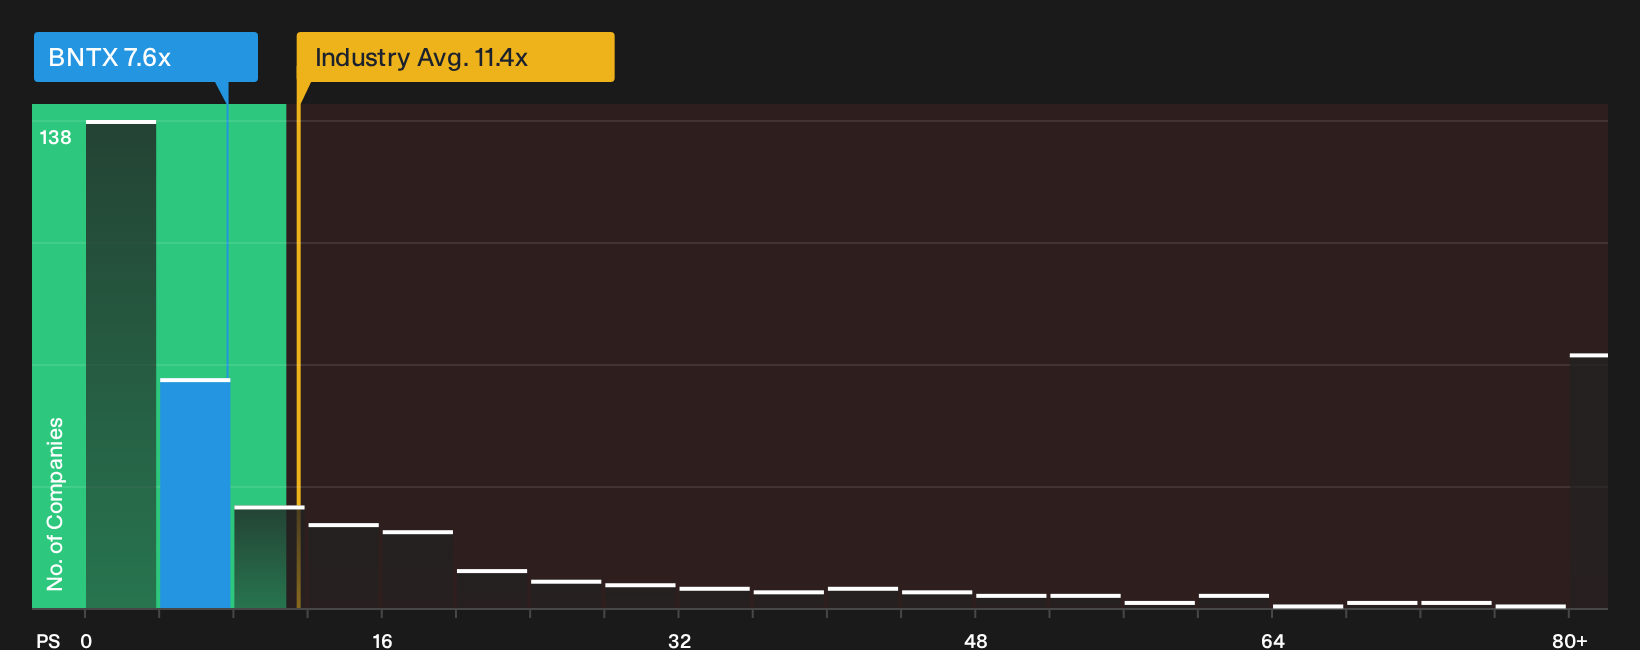
There is a catch to the “24.5% undervalued” narrative. On a simple P/S lens, BioNTech trades at about 7.6x, which is cheaper than the US Biotechs sector on 11.4x, yet richer than its peer group on 5.6x and above an estimated fair ratio of 6.7x.
That mix of relative discount versus the wider industry, premium to peers, and a P/S above the fair ratio points to real valuation risk if oncology execution disappoints, even if the story looks attractive against analyst targets. Which reference point do you trust most when the numbers pull in different directions?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Looking for more BioNTech sized opportunities?
If you stop with BioNTech, you only see one angle. Broaden your watchlist now and give yourself more ways for the numbers to work in your favor.
- Target resilient ideas with strong downside protection by scanning our 30 resilient stocks with low risk scores that aim to keep risk scores in check while still offering real business strength.
- Hunt for quality at a discount by reviewing a curated 20 high quality undiscovered gems that many investors may not yet have on their radar.
- Strengthen your core holdings by focusing on balance sheet health through a focused list of solid balance sheet and fundamentals (26 results) that filters for sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com