
Select Water Solutions (WTTR) Scaled Its Water Infrastructure Ambitions, Is The Stock Still Undervalued?
Select Water Solutions (WTTR) drew fresh attention after recent share price moves, with the stock closing at US$18.14. Investors are weighing this level against the company’s track record and current fundamentals.
Recent trading has been choppy for Select Water Solutions. The stock has pulled back over the past month, with a 30 day share price return of down 5.96% and a 90 day share price return of down 10.06%. However, the year to date share price return of 63.57% and five year total shareholder return of 233.69% show that longer term momentum has still been strong overall.
Scan beyond Select Water Solutions and compare its recent swings with hand picked 29 high quality undervalued stocks that also combine solid balance sheets with meaningful cash generation.
Select Water Solutions now trades at a clear discount to both analyst targets and estimated fair value. Are investors correctly pricing in risk, or has market caution swung too far?
Most Popular Narrative: 26% Undervalued
Against the last close at $18.14, the most followed narrative for Select Water Solutions places fair value near $24.57, using a 7.52% discount rate and a long range view of its water infrastructure buildout.
The acquisition of Pilot Water Solutions, which brings 3.8 million barrels per day of recycling capacity, 4.8 million barrels per day of active and undeveloped permitted disposal capacity, and more than 1,600 miles of pipeline, is expected to scale the Water Infrastructure segment so that it contributes around 70% of gross profit before D&A by 2027, with targeted cost synergies that can support higher segment EBITDA and improved overall margins.
See why 16 investors see Select Water Solutions as 26% undervalued.
Result: Fair Value of $24.57 (UNDERVALUED)
Still, Select Water Solutions faces real pressure points if heavy 2026 capex fails to earn its keep, or if tighter disposal well rules hit water volumes.
Find out about the key risks to this Select Water Solutions narrative.
Another View: What Multiples Say About Select Water Solutions
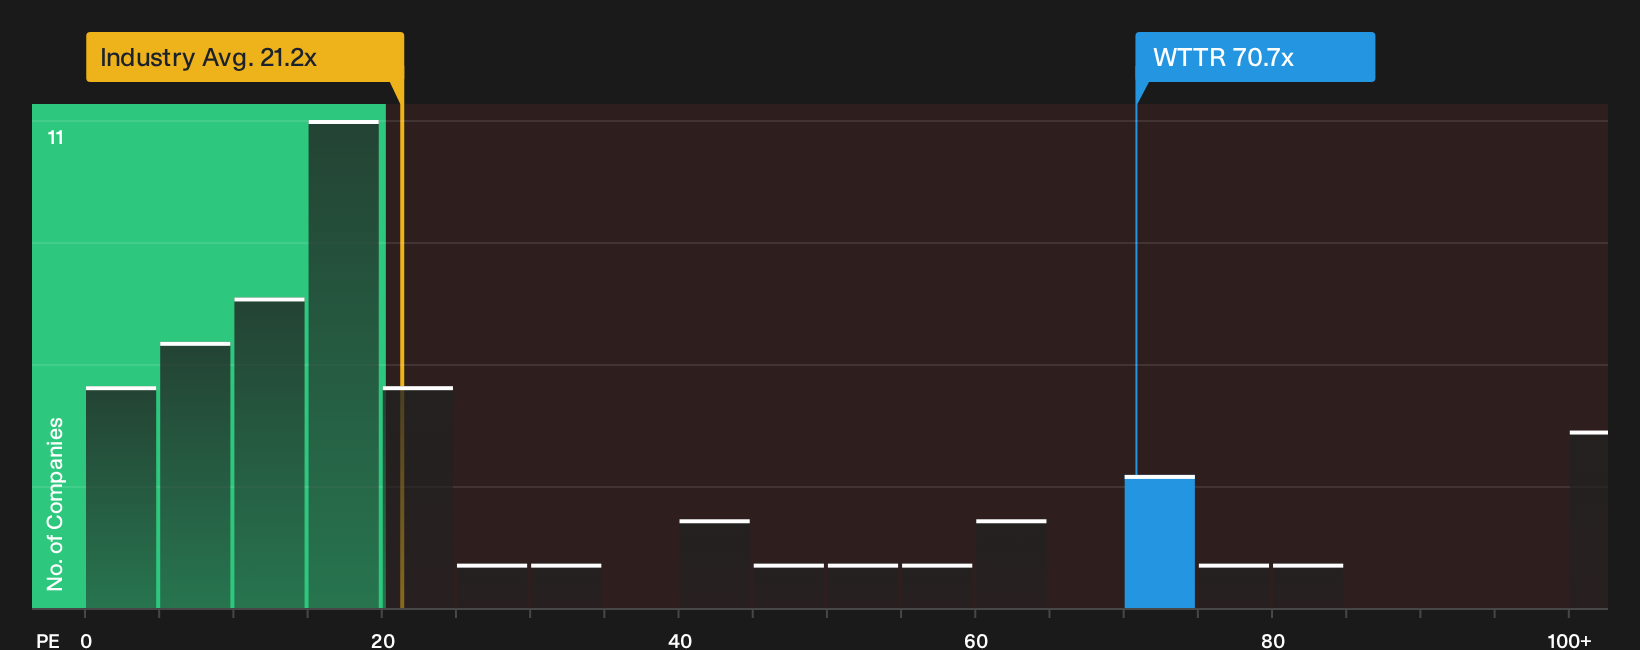
Take the DCF upside for Select Water Solutions and put it next to the market multiple. At a P/E of 70.7x versus a fair ratio of 28.8x, and with the US Energy Services group around 21.8x and peers near 62.3x, the stock carries clear valuation risk if sentiment cools.
That kind of gap means even if earnings track forecasts, a shift toward the fair ratio could affect returns, while any slip in expectations could add pressure. To see what the numbers indicate about this price, have a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Select Water Solutions is split, with optimism around value and concern around potential setbacks. Act quickly, review the numbers, and weigh both sides by starting with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Select Water Solutions?
Do not stop with one ticker. Fresh ideas often come from comparing businesses side by side, and missing that comparison can leave real opportunities on the table.
- Target resilient income by scanning for companies with durable payouts and strong coverage using our 6 dividend fortresses.
- Hunt for high quality businesses that the market may be overlooking by working through the 20 high quality undiscovered gems.
- Prioritise capital protection first and offense second by focusing on companies in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com