
Calix (CALX) Expands Its AI Platform, Is The Undervalued Case Convincing?
Calix (CALX) just rolled out a broad set of product upgrades at its ConneXions 2026 event, spotlighting AI-driven tools, SmartMDU improvements, new GigaPro switches, and wider SmartLife support that could reshape service provider workflows.
Despite the steady drumbeat of AI and SmartLife announcements around ConneXions 2026, Calix’s share price has drifted lower this year, with the year-to-date share price return down 31.95% and the 1-year total shareholder return declining 40.50%. However, the 3-year total shareholder return of 11.49% points to longer term gains that contrast with the recent weaker momentum.
Capitalize on the AI and broadband theme around Calix by scanning a curated set of 55 AI infrastructure stocks that could be setting up for the next wave of infrastructure-heavy upgrades.Calix appears to be actively expanding its broadband and AI platform, yet the share price has moved in the opposite direction this year. Is a solid operating story now being offered at a reasonable valuation?
Most Popular Narrative: 41% Undervalued
With the most followed narrative putting Calix’s fair value at $62.33 against a last close of $36.47, the gap between story and share price is wide and invites a closer look at what is driving that estimate.
The rollout of the AI native Calix One platform and Agent Workforce Cloud to roughly 1,200 migrated customers, supported by around $2b of historical platform investment and more than 0.5 billion workflows processed annually, points to further monetisation of agentic workflows that can support higher software and services revenue and improving gross margin quality.
See why 19 investors see Calix as 41% undervalued.
The prevailing narrative uses an 8.82% discount rate and arrives at a fair value of $62.33, which is materially above both the current $36.47 price and the consensus analyst target of $62.33. That view leans heavily on forecasts for earnings to reach $185.1m by around 2029, a projected profit margin of 10.9%, and an implied P/E of 23.4x on those future earnings, alongside expectations that share count trends lower through buybacks.
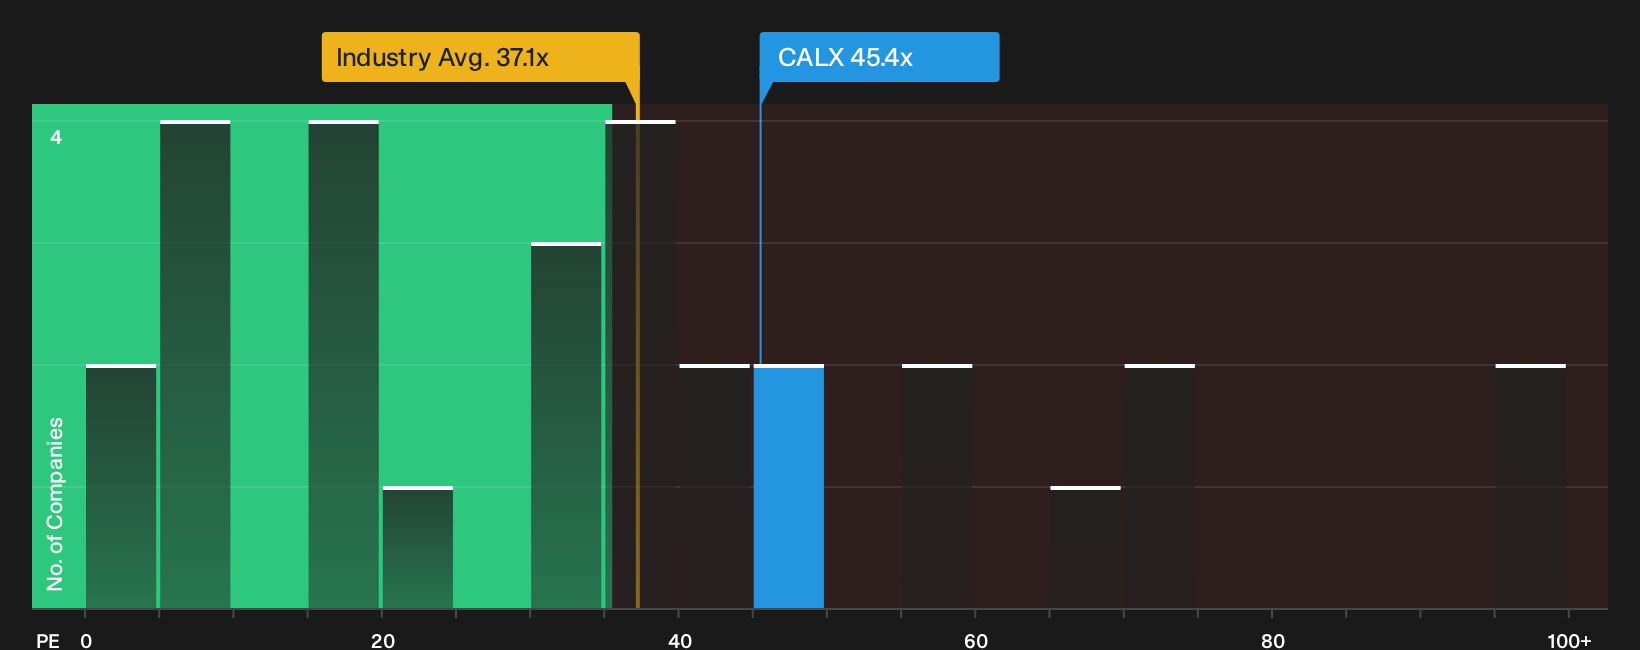
Analyst expectations also assume annual revenue growth of 15.2% and earnings growth of 46.6%, supported by higher recurring software and services mix, high quality earnings and a forecast return on equity of 21.6% in three years. Set against this are governance investigations, memory cost pressures and the fact that Calix trades on a current P/E of 45.4x, above both peers and its own fair P/E estimate of 42.9x, which helps explain why the market may not be fully embracing the optimistic scenario embedded in the popular thesis.
Result: Fair Value of $62.33 (UNDERVALUED)
Still, the upbeat Calix story runs into two hard constraints: rising memory related cost pressure on hardware margins and fresh shareholder investigations that could weigh on sentiment.
Find out about the key risks to this Calix narrative.
Another View: Calix On Earnings Multiples
Through the lens of Calix fair value screens, the story gets more complicated. The shares trade on a 45.4x P/E, richer than both the US Communications industry at 36.3x and the peer average at 40.9x, and also above a fair ratio of 42.9x that the market could eventually move toward.
That gap suggests investors are paying a premium today even as the stock has fallen this year. This raises a simple question: Is the current price compensating you enough for execution, governance and memory cost risks if sentiment cools toward that fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Still unsure whether the optimistic tone around Calix matches the current pricing and risk profile you see in the numbers? Move quickly, review the underlying metrics, then cross-check what investors are excited about through the 3 key rewards
Looking for more investment ideas beyond Calix?
If Calix has your attention but you want a wider bench of opportunities, now is the time to scan the market for other setups that fit your style.
- Target resilience by focusing on businesses with stronger finances and lower risk profiles through the 30 resilient stocks with low risk scores.
- Hunt for quality at a potentially appealing price by reviewing a curated pool of 29 high quality undervalued stocks.
- Strengthen your income plan by checking companies that feature higher yields and defensive characteristics across the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com