
Is Frasers Property (SGX:TQ5) Undervalued After Its Leadership Hire?
Frasers Property (SGX:TQ5) has put leadership change in the spotlight after announcing that Mr. Mirpuri will join its executive team in January 2027, reporting directly to Group CEO Panote Sirivadhanabhakdi.
Frasers Property shares have slipped over the year despite a recent 1 day share price gain of 1.70%. The year to date share price return is down 20.8% and the 1 year total shareholder return has declined 13.1%, while the 3 year total shareholder return of 32.28% hints at earlier momentum that has cooled more recently.
Scan for other real estate players where leadership or platform shifts could matter just as much by reviewing our hand picked list of solid balance sheet and fundamentals (205 results) alongside Frasers Property.
After a weak year for the share price and a fresh leadership appointment in industrial and logistics, the key question for Frasers Property now is whether most of the value reset is already behind it or still ahead.
Preferred P/E of 20.4x: Is it justified for Frasers Property?
Frasers Property trades on a P/E of 20.4x, which sits against a last close of SGD0.895 and raises questions about how much future profit the market is already factoring in compared with peers and the wider Singapore real estate sector.
The P/E ratio links the current share price to earnings per share and acts as a shorthand for how much investors are willing to pay for each dollar of profit. For a diversified real estate investor and developer like Frasers Property, that multiple effectively bundles together expectations around rental income, development profits, capital recycling and the resilience of its portfolio across industrial and logistics, hospitality, retail and commercial assets.
On the sector scorecard, the P/E of 20.4x looks expensive compared to the SG Real Estate industry average of 12.4x, which suggests the stock carries a richer tag than the typical local peer. At the same time, it screens as better value than the peer average of 24.4x, and the estimated fair P/E ratio of 14.6x points to a level the market could move towards if sentiment or earnings do not keep supporting the current premium.
Explore the SWS fair ratio for Frasers Property.
Result: Price-to-Earnings of 20.4x (OVERVALUED)
Still, any disappointment around earnings resilience or shifts in Frasers Property’s industrial and hospitality cycles could quickly challenge the premium P/E and reset sentiment.
Find out about the key risks to this Frasers Property narrative.
Another View on Frasers Property’s Valuation
The P/E premium tells one story for Frasers Property, but the SWS DCF model tells another. On that framework, the stock at SGD0.895 is assessed as trading well below an estimated future cash flow value of SGD2.73, which points to a wide gap between price and implied intrinsic worth.
This kind of disconnect can cut both ways. It can reflect a market that is cautious about earnings quality, funding risk or execution, or it can be a sign that investors are heavily discounting long term cash generation. The question is which side of that trade you think is closer to reality.
Look into how the SWS DCF model arrives at its fair value.
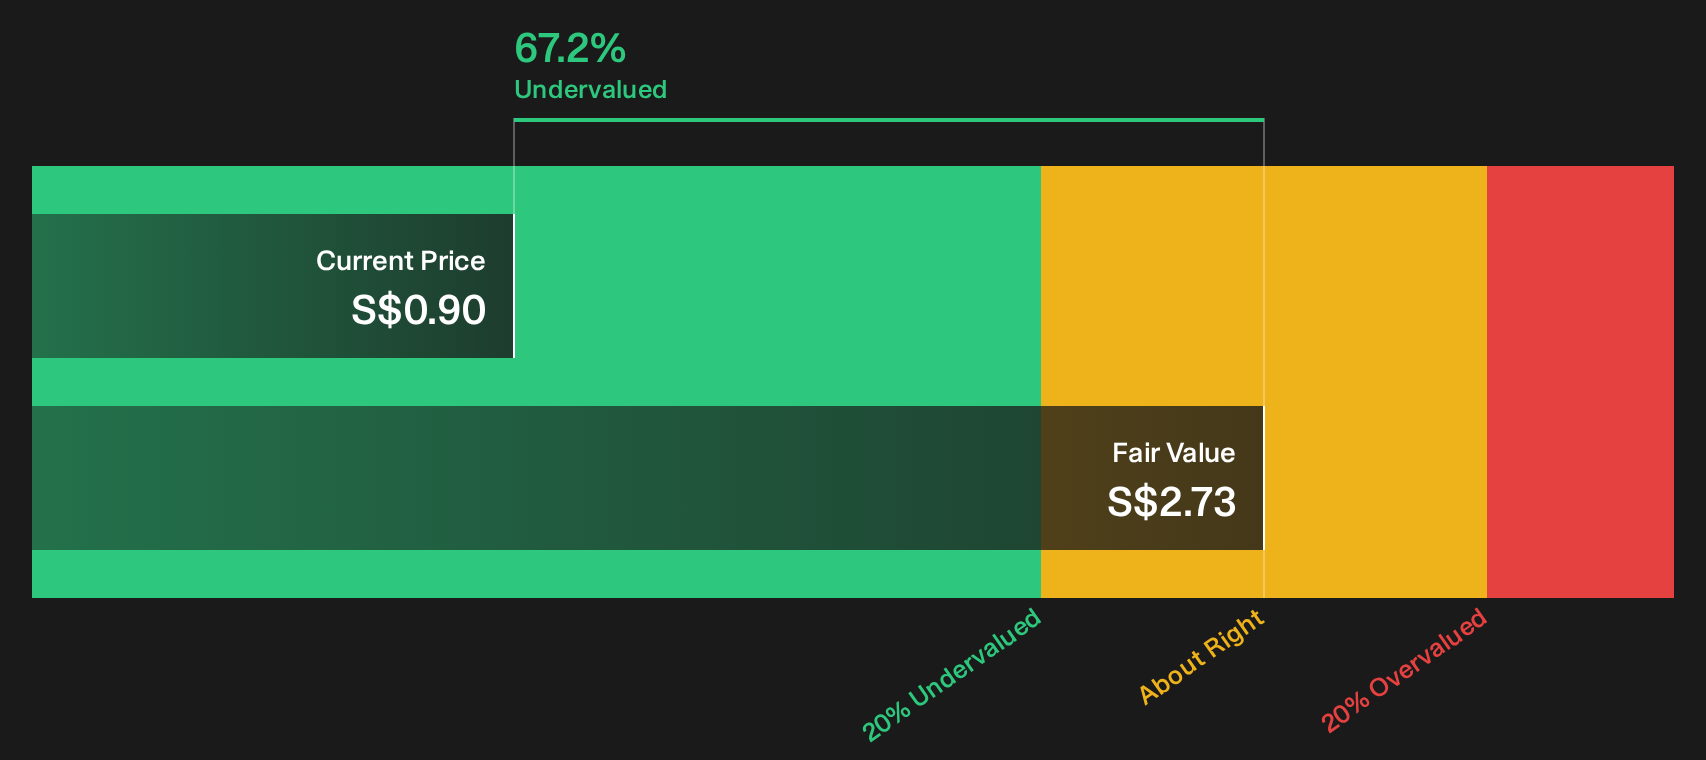
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Frasers Property for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 201 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on value and risk can be confusing. Move quickly from reading to testing the numbers, and weigh both sides by reviewing the 2 key rewards and 2 important warning signs.
Looking for more Frasers Property style investment ideas?
If you stop your research with Frasers Property, you risk missing other opportunities that suit your goals just as well or even better.
- Target resilient cash generators by scanning our 201 high quality undervalued stocks that combine solid fundamentals with a price tag the market may not be fully recognizing.
- Strengthen your income stream by reviewing the 226 dividend fortresses and focus on businesses offering higher yields with an eye on durability.
- Dial down portfolio stress by filtering for the 221 resilient stocks with low risk scores so you can concentrate on companies with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com