
We Think Hot Chili (ASX:HCH) Can Afford To Drive Business Growth
Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. But while history lauds those rare successes, those that fail are often forgotten; who remembers Pets.com?
So, the natural question for Hot Chili (ASX:HCH) shareholders is whether they should be concerned by its rate of cash burn. For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). Let's start with an examination of the business' cash, relative to its cash burn.
When Might Hot Chili Run Out Of Money?
A company's cash runway is calculated by dividing its cash hoard by its cash burn. In June 2026, Hot Chili had AU$25m in cash, and was debt-free. Importantly, its cash burn was AU$32m over the trailing twelve months. Therefore, from June 2026 it had roughly 9 months of cash runway. Importantly, though, the one analyst we see covering the stock thinks that Hot Chili will reach cashflow breakeven before then. In that case, it may never reach the end of its cash runway. The image below shows how its cash balance has been changing over the last few years.
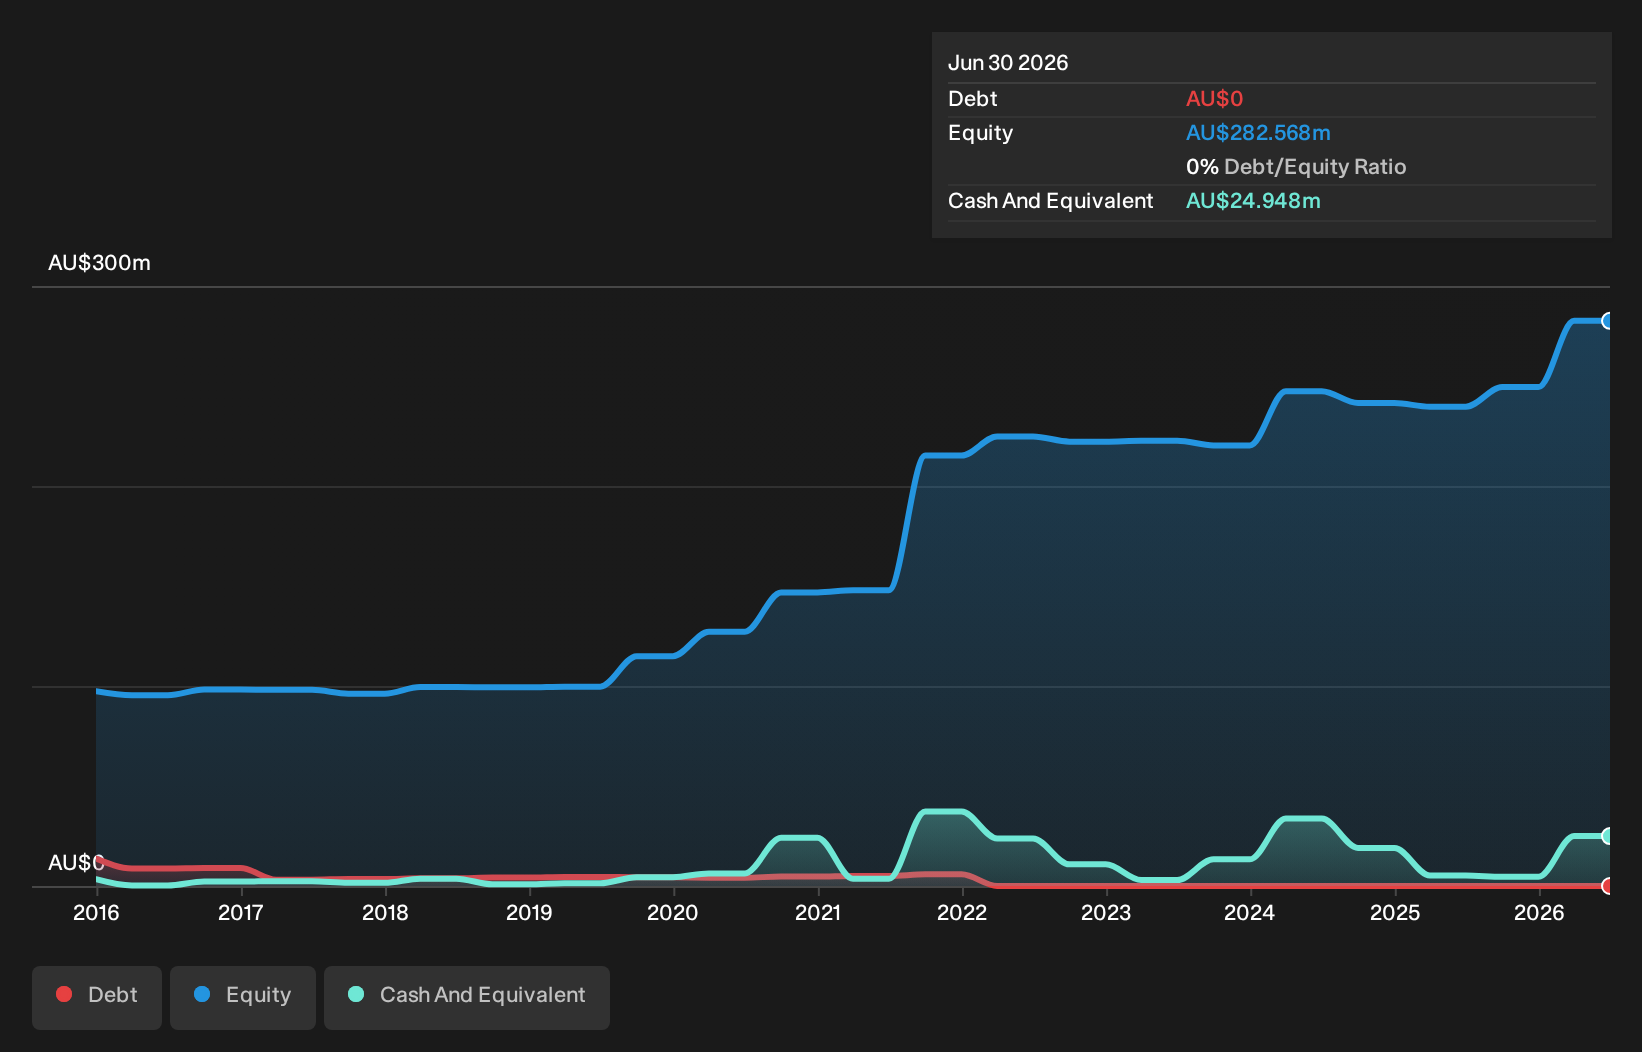
See our latest analysis for Hot Chili
How Is Hot Chili's Cash Burn Changing Over Time?
Because Hot Chili isn't currently generating revenue, we consider it an early-stage business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. Over the last year its cash burn actually increased by 2.1%, which suggests that management are increasing investment in future growth, but not too quickly. However, the company's true cash runway will therefore be shorter than suggested above, if spending continues to increase. Clearly, however, the crucial factor is whether the company will grow its business going forward. So you might want to take a peek at how much the company is expected to grow in the next few years.
Can Hot Chili Raise More Cash Easily?
While its cash burn is only increasing slightly, Hot Chili shareholders should still consider the potential need for further cash, down the track. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Hot Chili has a market capitalisation of AU$259m and burnt through AU$32m last year, which is 12% of the company's market value. As a result, we'd venture that the company could raise more cash for growth without much trouble, albeit at the cost of some dilution.
Is Hot Chili's Cash Burn A Worry?
As you can probably tell by now, we're not too worried about Hot Chili's cash burn. In particular, we think its cash burn relative to its market cap stands out as evidence that the company is well on top of its spending. While its cash runway wasn't great, the other factors mentioned in this article more than make up for weakness on that measure. There's no doubt that shareholders can take a lot of heart from the fact that at least one analyst is forecasting it will reach breakeven before too long. Considering all the factors discussed in this article, we're not overly concerned about the company's cash burn, although we do think shareholders should keep an eye on how it develops. Readers need to have a sound understanding of business risks before investing in a stock, and we've spotted 3 warning signs for Hot Chili that potential shareholders should take into account before putting money into a stock.
Of course Hot Chili may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.