
SCA (OM:SCA B) Q3 Earnings Reveal A Margin Squeeze Beneath Growth
Svenska Cellulosa Aktiebolaget came into Q3 2026 earnings priced for perfection, trading on a rich 40.6x trailing P/E after a flat month and a 19.2% rise over 90 days. The fresh report delivered what the long term thesis demands: solid pulp and paper cash generation, with SEK 6,047m in sales and SEK 772m in net profit, yet the market response was muted.
For a stock already carrying a premium multiple, the real story is the margin squeeze. Trailing net profit margin sits at 9.3%, well below last year, which puts every krona of earnings quality under the microscope.
Like the quality of Svenska Cellulosa Aktiebolaget’s pulp and paper engine but uncomfortable with paying a rich 40.6x P/E while margins feel tight? Check out a shortlist from our screener of list of solid balance sheet and fundamentals stocks (204 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): SEK 6,047m vs. SEK 5,587m (up around 8%)
- Net Income (Q3 2026 vs Q3 2025): SEK 772m vs. SEK 832m (down around 7%)
- Basic EPS (Q3 2026 vs Q3 2025): 1.10 SEK vs. 1.19 SEK (down around 8%)
- Net Profit Margin, Trailing 12 Months (Q3 2026 vs prior year): 9.3% vs. 15.7% (compressed by around 6 percentage points)
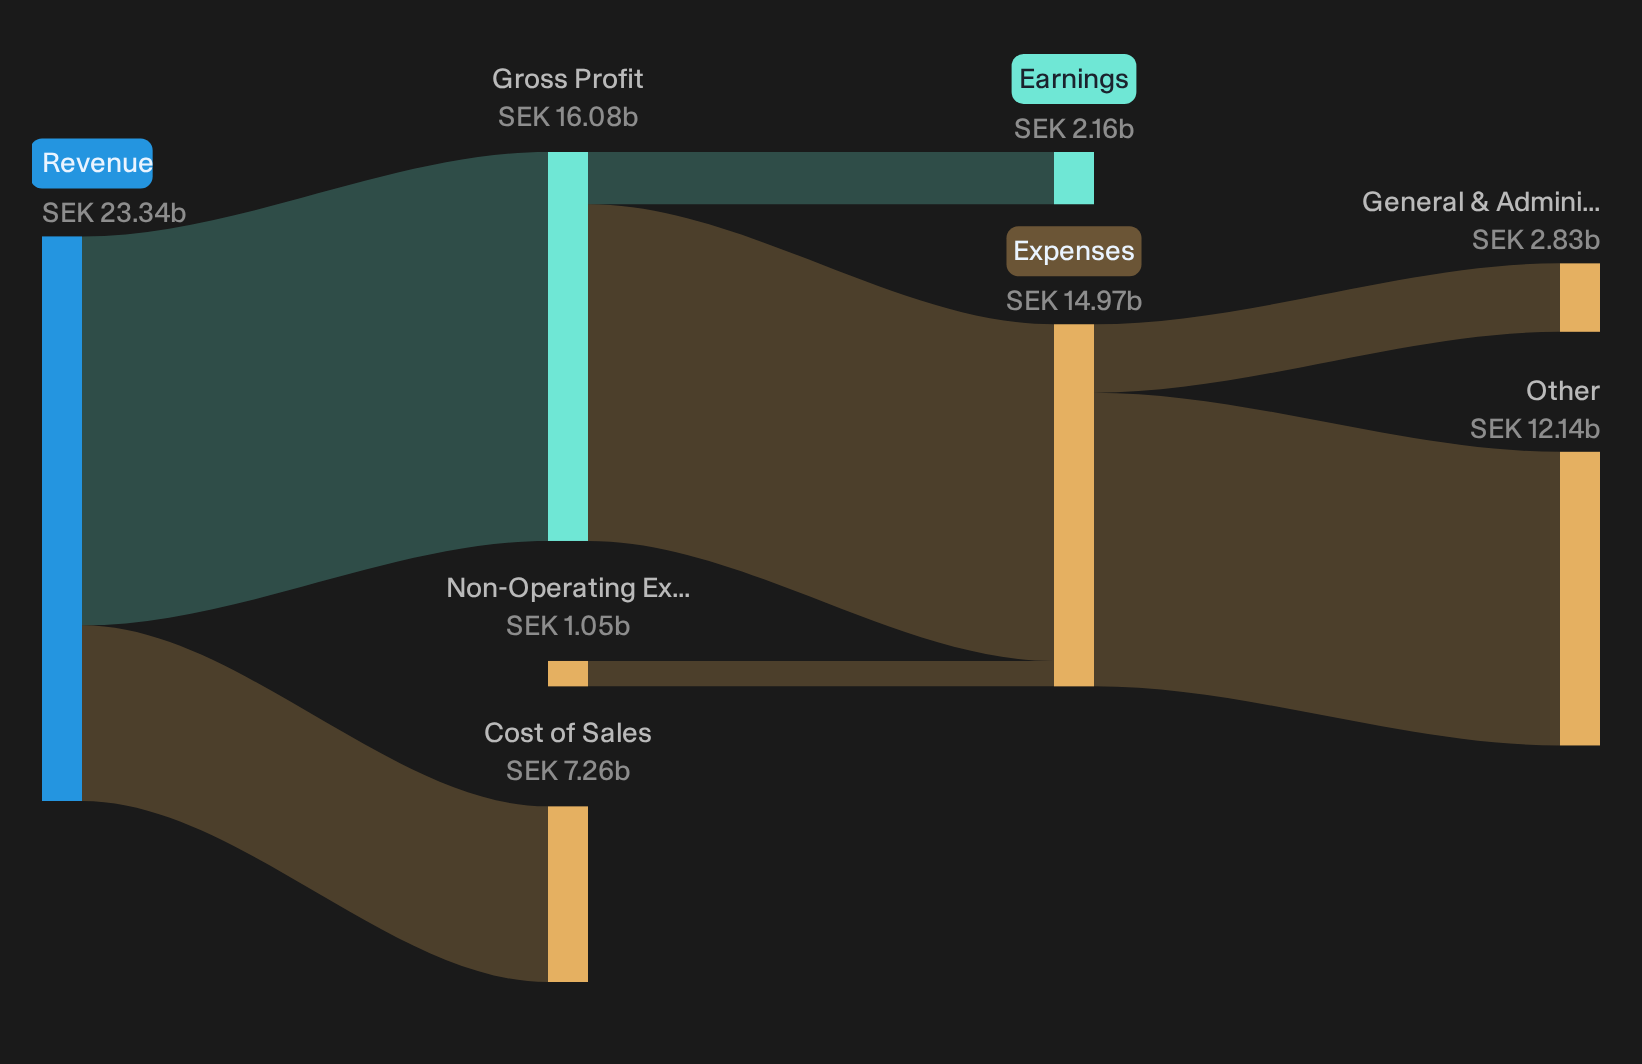
Svenska Cellulosa Aktiebolaget: Capacity Story Meets Mixed Reality
The bullish story on Svenska Cellulosa Aktiebolaget hinges on turning finished capex into higher earnings rather than pursuing additional projects.
"The completion and ramp up of major industrial projects such as Obbola, Ortviken, the Gothenburg biorefinery and new wind assets, with incremental volumes currently sold into marginal markets, creates optional upside if tighter European demand later allows a shift from low margin export tonnes to higher margin regional contracts."
Q3 shows parts of that playbook working. Containerboard delivered SEK 446m EBITDA with a 23% margin and double digit sales growth as higher kraftliner prices gained traction. Renewable Energy posted a 42% margin on SEK 201m EBITDA, indicating that wind and biofuels are now meaningful. Forest, Wood and Pulp remain a drag, so the capacity story is only partly validated so far.
One Narrative disagrees with today's price. → See where this Narrative says Svenska Cellulosa Aktiebolaget should trade.
Svenska Cellulosa Aktiebolaget: Bear Fears On Utilisation Still Lingering
The key worry is that Svenska Cellulosa Aktiebolaget’s pulp capacity looks impressive on paper but struggles to run flat out when power markets turn against it.
"Although the new capacity at Ortviken is in place, the pattern of running CTMP at roughly half utilisation when power prices spike and only returning to higher loads when demand and pricing improve suggests future periods of forced curtailment that could cap pulp revenue and keep segment EBITDA volatile."
Q3 pulp volumes were described as strong, yet EBITDA margin sat at 11% and management still referenced weak pricing. That combination keeps the concern about volatile utilisation and earnings active rather than resolved.
Hunt For Mispriced Capacity Stories
Svenska Cellulosa Aktiebolaget reports steady operations while investors react to pressure on margins. The real opportunity may be in stocks where capacity changes are not yet fully reflected in sentiment.
- Company 1 - 23% below our estimate - expands higher value healthcare components and integrates a capsule acquisition into a more focused manufacturing footprint.
- Company 2 - 34% below our estimate - converts large artificial intelligence infrastructure contracts and multicloud database deals into subscription oriented workloads on its own platforms.
- Company 3 - 26% below our estimate - shifts from fixed price shipbuilding toward integrating underwater systems and digital equipment for defence and dual use contracts.
Three companies from the same screener. Open the full list of 195 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com