
Alpine Income Property Trust (PINE) Stock Drops As Q3 Results Lift AFFO
Alpine Income Property Trust came into this Q3 2026 report under a cloud, with the stock already weak over the past quarter and then dropping another 7.2% today to about US$16. Traders saw risk. The results told a different story. Adjusted funds from operations, or AFFO, reached roughly US$0.55 per share for the quarter and management lifted full year 2026 AFFO guidance to around US$2.20 to US$2.22. The gap that matters now is not between earnings and forecasts. It is between a sliding share price and a net lease REIT posting double digit AFFO per share growth.
Love Alpine’s rising AFFO profile but uneasy about a share price that keeps slipping anyway? Benchmark it against our list of solid balance sheet and fundamentals stocks (25 results) to see other income focused stocks where cash flow and balance sheet strength align more clearly.
Q3 2026 Earnings Summary
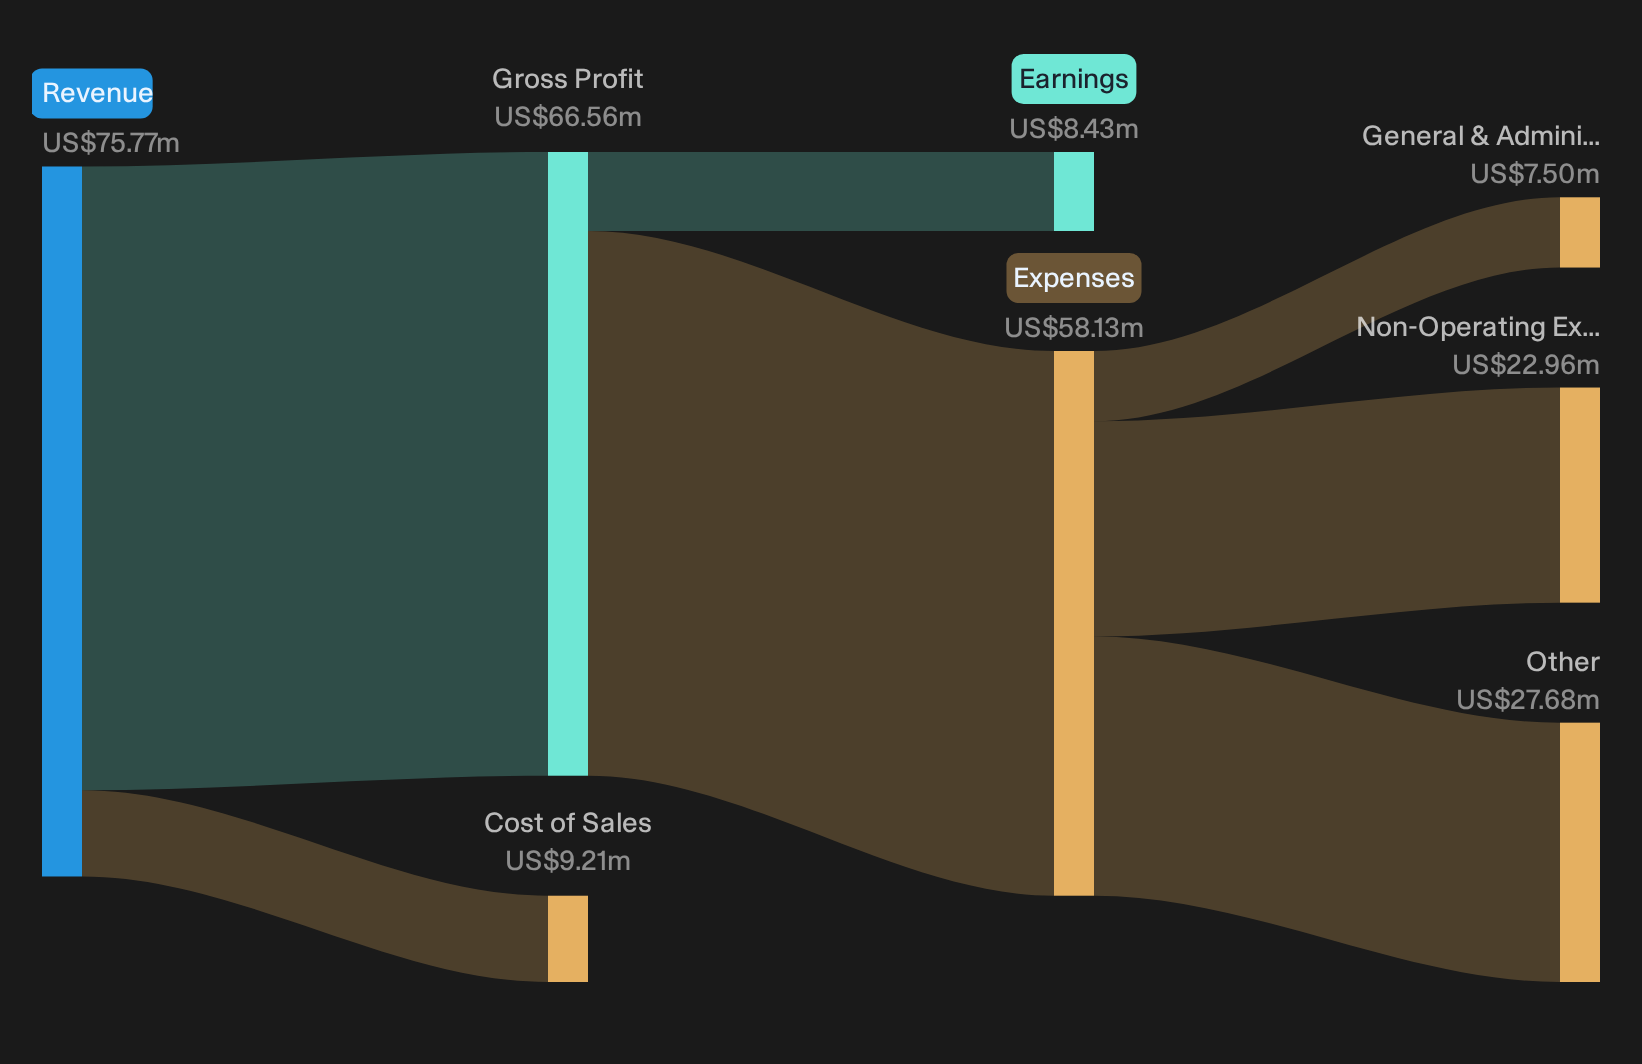
- Total Revenue (Q3 2026 vs. Q3 2025): US$20.46 million vs. US$14.56 million (higher year on year)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$3.44 million vs. a loss of US$1.31 million (moved from loss to profit)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.19 per share vs. a loss of US$0.09 per share (returned to positive earnings per share)
- Funds From Operations (FFO) per Share (Q3 2026 vs. Q3 2025): US$0.55 vs. US$0.50 (higher funds from operations per share)
Alpine lifted AFFO guidance again after a record year of deals. Ask Charlie what’s driving Alpine’s record investment pace this year.
Alpine’s High-Yield Mix Put To The Test
The bullish story says Alpine Income Property Trust can lean on its loans and higher yielding assets to support recurring cash generation.
"The build out of Alpine Income Property Trust's high coupon commercial loan book at about 20% of total undepreciated asset value, with US$167 million of loans at a 13.2% weighted average coupon by Q2 2026 and ongoing recycling of lower yielding payoffs into higher yielding loans, is expected to support interest income and funds from operations."
Q3 interest income of US$7.6 million on US$20.5 million of total revenue, a 13.4% loan coupon and approximately 20% loan allocation, plus AFFO per share of US$0.55 and raised 2026 AFFO guidance, all align with that playbook so far.
Bear Case Focuses On Dilution And Fragile Funding
On the other hand, skeptics argue that this same growth model could quietly cap per share progress if funding costs climb and equity issuance continues.
"Alpine Income Property Trust relies on high coupon commercial loans and high yielding acquisitions to support funds from operations, and the material shows that higher swap rates and a larger share count are already reducing the underlying AFFO per share run rate compared with the reported figure, which could limit future earnings growth."
Q3 still shows US$70 million raised year to date via ATM programs, new term debt that will be swapped near 4.75%, and known swap roll ups from 2027. AFFO per share is growing today, but the mechanics critics highlight are already in motion.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Spot Test Your Yield Ideas
Alpine Income Property Trust recently reported a strong quarter while its share price declined. The real opportunity lies in finding stocks that may be undervalued before the market responds.
- Company 1 - 36% below our estimate - uses added capacity and high horsepower engine projects to pursue long term power demand contracts.
- Company 2 - 30% below our estimate - rides constrained vessel availability to negotiate higher contract day rates for marine support on offshore projects.
- Company 3 - 42% below our estimate - extends a solar tracking platform into storage and inverter projects that strengthen ties with large power developers.
That is three of the list. See every one of the 27 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com