
How Fertilizer Demand Swings Will Impact Nutrien (TSX:NTR) Investors
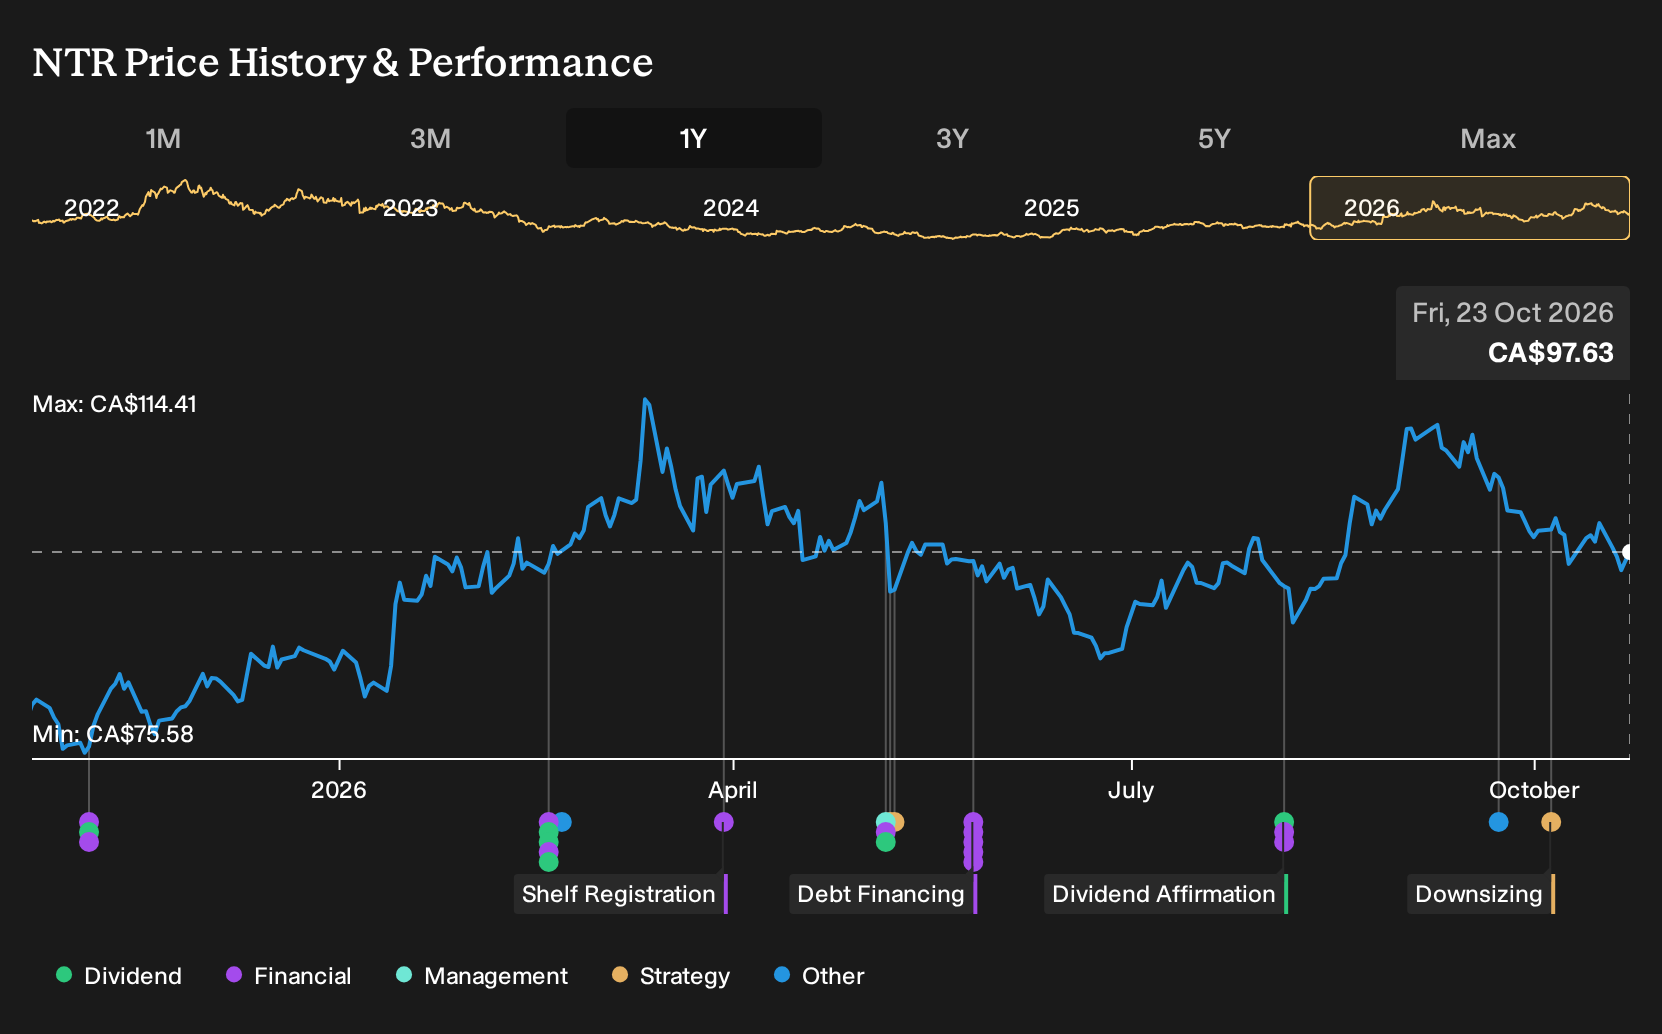
- Nutrien recently saw a 1.524% share price decline, reflecting market concern around fertilizer demand, agricultural commodity pricing, and rising input and energy costs that influence farmers’ purchasing decisions.
- The reaction highlights how sensitive Nutrien’s earnings outlook is to swings in fertilizer prices, natural gas expenses, and trade restrictions that can reshape global farming economics.
- We will now look at how Nutrien's investment narrative holds up against short term pressure from fertilizer demand and input costs.
Scan beyond Nutrien and see how other fertilizer exposed producers and input suppliers are positioned right now with the curated list of solid balance sheet and fundamentals (7 results).
Nutrien Investment Narrative Recap
Nutrien appeals to shareholders who think long term about global food demand and see fertilizer as a critical input rather than a discretionary extra. The recent 1.524% share price move looks like a sentiment reaction to softer fertilizer demand and cost worries rather than a change in that bigger food story. The more important near term swing factor is fertilizer pricing and volumes relative to input costs such as natural gas.
The biggest current risk is that earnings forecasts already point to a gradual decline of about 2.7% a year over the next three years while Nutrien carries a meaningful debt load. If fertilizer prices stay weaker for longer or regulatory costs rise, that combination could pressure margins and limit flexibility just as the business is working on efficiencies and portfolio optimization.
There have not been fresh company announcements tied directly to this latest share price move, so the most relevant reference point is the existing analyst view on Nutrien’s earnings path. Forecasts call for relatively flat revenue growth at about 0.1% a year and softer profitability, with earnings expected to reach about US$2.1b by 2029 compared with US$2.4b today.
That backdrop sets expectations for modest top line progress and tighter margins, which helps frame the latest pullback. For you as an investor, the key question is whether Nutrien’s execution on cost reduction, precision agriculture offerings, and capital allocation can offset the forecast decline in earnings and the sector risks around regulation and changing crop nutrition practices.
Nutrien's current analyst narrative points to revenue of US$27.7b and earnings of US$2.1b by 2029, with revenue described as fairly flat over the next three years and earnings expected to fall by US$0.3b from US$2.4b today.
Uncover why Nutrien's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bearish twist on Nutrien focuses on how weaker Retail fertilizer volumes could linger. The lowest analysts were already modeling revenue of about US$26.5b and earnings around US$1.8b by 2029 before this 1.524% drop, which is far more cautious than consensus. Use that gap to explore how your own view might shift as new data lands.
Explore 4 other Nutrien fair value estimates, including one that suggests it could be worth just CA$98.51.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nutrien research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nutrien. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nutrien's overall financial health at a glance.
Looking for more investment ideas beyond Nutrien?
If Nutrien has sharpened your thinking about risk, earnings paths, and balance sheet strength, use that same framework to scan for other businesses that fit your preferences. The Simply Wall St Screener can help you quickly narrow the field to opportunities that line up with your income needs, risk tolerance, and focus on quality.
- If you want holdings with staying power, start by reviewing a curated 8 resilient stocks with low risk scores that score well on resilience and financial robustness.
- For investors who care about quality at a reasonable price, filter for companies on the 2 high quality undervalued stocks and compare their fundamentals with your thesis on Nutrien.
- If you prefer to fish where fewer people are looking, scan through a 9 high quality undiscovered gems that pair strong metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com