
Why International Business Machines (IBM) Is Back In Focus Today
International Business Machines (IBM) just delivered its third quarter 2026 report, putting fresh numbers around revenue, profit and cash flow, while also reaffirming guidance and its long running dividend stream.
Investor attention has swung back toward International Business Machines after a sharp drop in July and a stronger third quarter, with a 90 day share price return of 18.38% and a 1 year total shareholder return that is still down 15.39%. The 5 year total shareholder return of 156.94% points to momentum that has built over a longer stretch rather than just this earnings week.
Capitalize on International Business Machines' renewed AI and infrastructure focus by lining it up against 55 AI infrastructure stocks to see which peers share similar momentum and multi-year investment themes.International Business Machines now appears to be a stronger, more focused software and infrastructure story after this quarter. However, after an 18% rebound in 90 days, the question remains: is that quality already fully reflected in the price, or not yet?
Most Popular Narrative: 1% Undervalued
International Business Machines closed at $253.56, while the most followed narrative on the stock sees fair value closer to $256.08. This frames the recent rebound as only partly pricing in the AI and infrastructure story.
IBM represents a defensive growth technology investment transitioning into a software and AI-led enterprise platform company. While topline growth remains moderate, improving mix (software), strong margins, and durable cash flows underpin a long-term investment case, particularly for investors seeking exposure to enterprise AI with lower volatility than pure-play SaaS peers.
See why 54 investors see International Business Machines as 1% undervalued.
Result: Fair Value of $256.08 (UNDERVALUED)
Still, International Business Machines faces two clear swing factors: slower than expected AI adoption among enterprise clients and any setback in high margin software execution.
Find out about the key risks to this International Business Machines narrative.
Another View On International Business Machines' Valuation
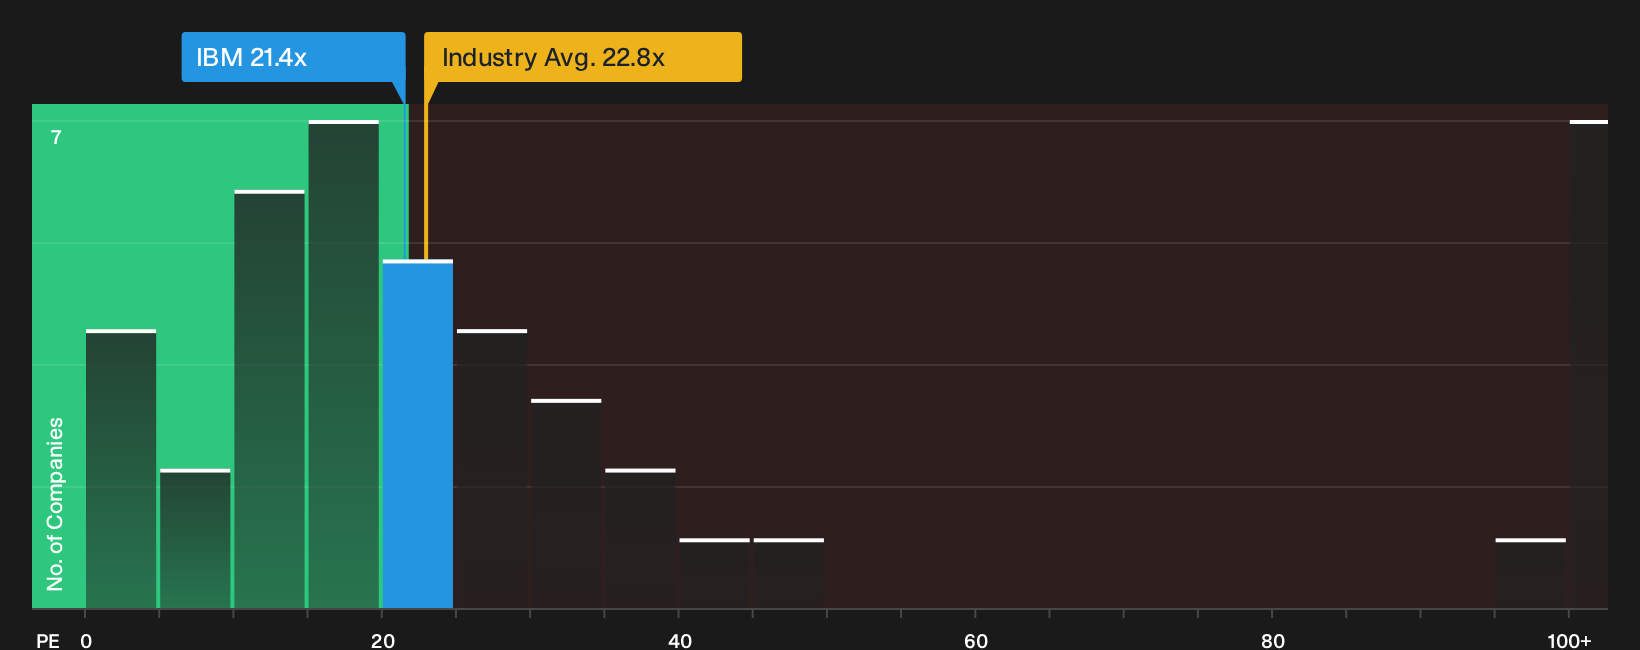
The SWS fair ratio paints a different picture for International Business Machines. The current P/E is 21.4x, while the fair ratio sits at 35.7x and the wider US IT group averages 22.8x with peers closer to 17x. That mix of discount and premium raises a simple question: Is this a margin of safety, or a value trap in disguise?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around International Business Machines is mixed, with clear concerns sitting beside real bright spots, so it pays to review the details yourself and act before views harden. To see both sides laid out in one place, take a close look at the balance of 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond International Business Machines?
Do not stop your research with IBM. Broader context across other opportunities often sharpens your view on what really belongs in your portfolio.
- Hunt for quality at a discount by scanning companies that currently screen as 27 high quality undervalued stocks and line them up against International Business Machines.
- Strengthen the foundation of your holdings by running through a list of solid balance sheet and fundamentals (25 results) that can complement a core position like International Business Machines.
- Spot potential future leaders before the crowd by filtering for 21 high quality undiscovered gems that match the kind of fundamentals you want beside IBM.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com