
Symbotic (SYM) Dropped, So What Is Drawing Fresh Attention?
Symbotic (SYM) has moved back into focus after analysts raised earnings estimates, while management kept near term revenue guidance steady and acknowledged slower sales growth. That mix of optimism and caution is shaping how investors reassess the stock.
Over the past year, Symbotic’s share price return has fallen 39.45%, with a 30 day share price decline of 10.09% and a modest 7 day gain of 1.32% that hints at fragile momentum around the current US$39.28 level.
Spot potential Symbotic lookalikes in warehouse automation and robotics by scanning our curated list of 95 robotics and automation stocks.Symbotic’s slide, followed by a small bounce and steady guidance, presents a straightforward choice: lock in today’s reset price, or wait and risk missing a better valuation setup.
Most Popular Narrative: 38% Undervalued
On the most followed view of Symbotic, a fair value of $62.86 versus the recent $39.28 share price points to a wide valuation gap that rests heavily on how the warehouse automation rollout plays out over the next few years.
The acceleration of global e-commerce adoption and the resulting push for retailers and wholesalers to overtake legacy distribution models with automation is fueling strong demand for Symbotic's advanced warehouse systems, as evidenced by their record $22.4B backlog and expanding inbound pipeline. This supports long-term revenue growth.
Persistent challenges with labor costs and shortages in logistics continue to drive supply chain players to seek automation, positioning Symbotic's rapid deployment next-generation storage structure as an attractive solution. This is expected to improve both customer acquisition rates and topline revenue.
See why 146 investors see Symbotic as 38% undervalued.
Result: Fair Value of $62.86 (UNDERVALUED)
Still, customer concentration with Walmart and execution risk around the next generation storage rollout could quickly weaken the bullish Symbotic narrative if projects slip.
Find out about the key risks to this Symbotic narrative.
Another View On Symbotic’s Valuation
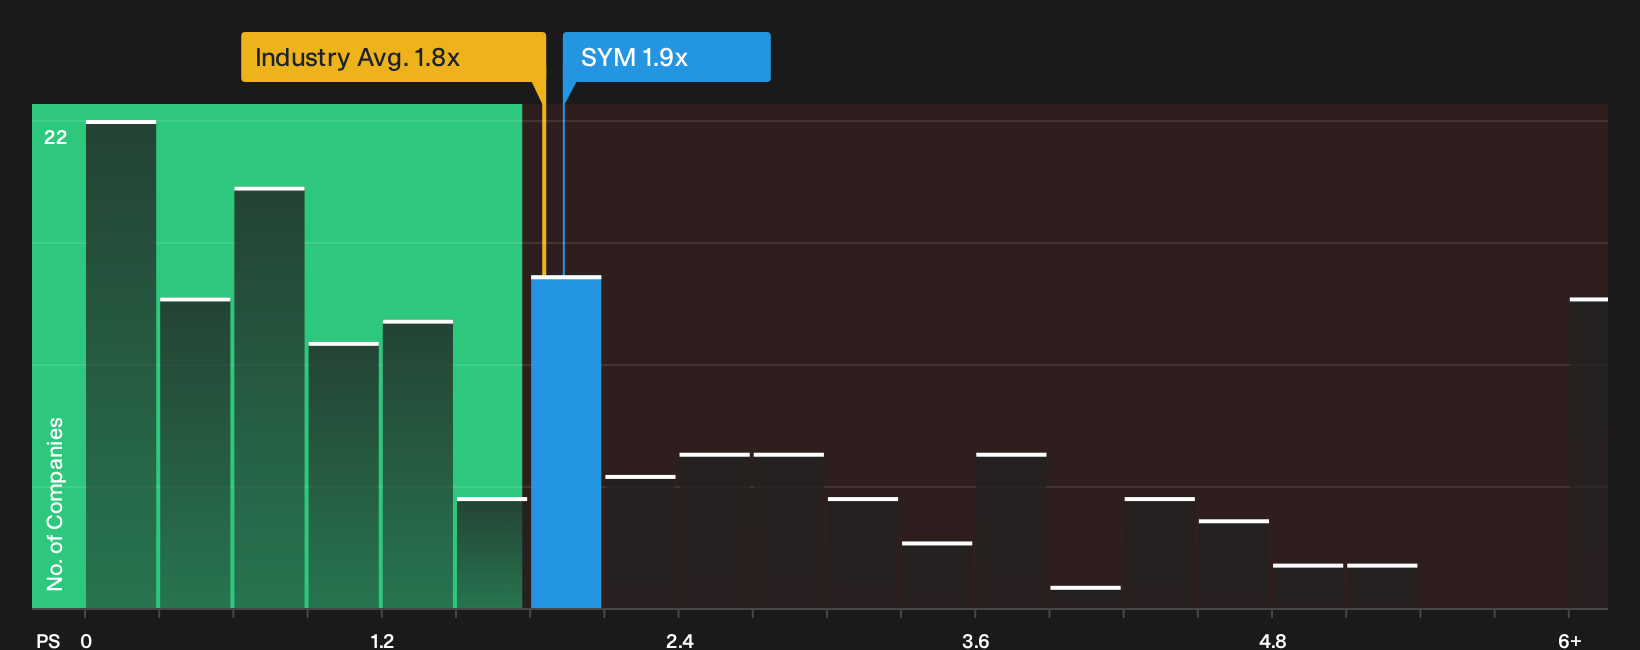
There is a different signal when you look at Symbotic through its P/S ratio. The stock trades at 1.9x sales, slightly richer than the US Machinery industry at 1.8x, yet well below a 3.3x peer average and a 4.4x fair ratio that the market could move toward. That mix hints at room for re rating but also highlights how much depends on whether Symbotic earns its way closer to that fair ratio over time. Which side of that trade do you want to be on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Symbotic’s valuation and execution risk naturally split opinion, so move quickly, test the numbers yourself, and weigh both the upside and the warning signs in 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Symbotic?
Once you have an opinion on Symbotic, do not stop there. Use fresh watchlist ideas to pressure test your thinking and broaden your opportunity set.
- Target potential mispricings by scanning a curated pool of 27 high quality undervalued stocks that combine solid fundamentals with what our data flags as discounted prices.
- Prioritise resilience by reviewing a 30 resilient stocks with low risk scores that tilts toward businesses with stronger balance sheets and fewer red flags.
- Hunt for future leaders early through a focused 21 high quality undiscovered gems that spotlights quality companies still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com