
Brookdale Senior Living (BKD), What Is Behind The Fresh Attention?
Why Brookdale Senior Living’s latest real estate moves matter
Brookdale Senior Living (BKD) has pushed further into owning the buildings it operates. The operator just closed on 17 previously leased communities and agreed to buy the real estate of 30 more.
For Brookdale Senior Living’s shareholders, the real estate push lands at an interesting moment. The share price has fallen about 33% over the past 90 days and is down almost 10% over the past month, yet the 1 year total shareholder return of 14.16% and 3 year total shareholder return of about 15x still point to a strong longer term payoff profile. This suggests the latest property deals are being weighed against changing views on risk and cash flow quality rather than a simple reversal in the broader story.
Capitalize on Brookdale Senior Living’s real estate shift by weighing it against other operators with steadier unit ownership and rent profiles in our curated list of solid balance sheet and fundamentals (25 results).Brookdale Senior Living is swapping rent checks for mortgages, yet the share price has already reset hard. Does that mix of heavier ownership and recent drawdown still tilt the risk reward toward buyers at this price?
Most Popular Narrative: 41% Undervalued
Brookdale Senior Living’s most followed narrative pins fair value at $17.00 against a last close of $10.08, which frames the latest real estate purchases as part of a wider debate about cash conversion, leverage, and what investors are willing to pay for that profile.
The main factor that has to go right is that Brookdale converts its regional operating model, portfolio reshaping, and community reinvestment into sustained occupancy and RevPAR gains that more than offset higher facility expenses and the revenue impact of asset sales.
The current numbers on RevPAR growth, improving adjusted EBITDA, positive adjusted free cash flow, and ongoing deleveraging point to a share price that does not fully reflect the company’s progress on margins, balance sheet repair, and concentration in higher-performing owned assets.
See why 1 investors see Brookdale Senior Living as 41% undervalued.
Result: Fair Value of $17.00 (UNDERVALUED)
Still, if Brookdale Senior Living continues to outperform on adjusted EBITDA and free cash flow, and deleverages faster than expected, that bearish $17 narrative could unravel quickly.
Find out about the key risks to this Brookdale Senior Living narrative.
Another View on Brookdale Senior Living’s Valuation
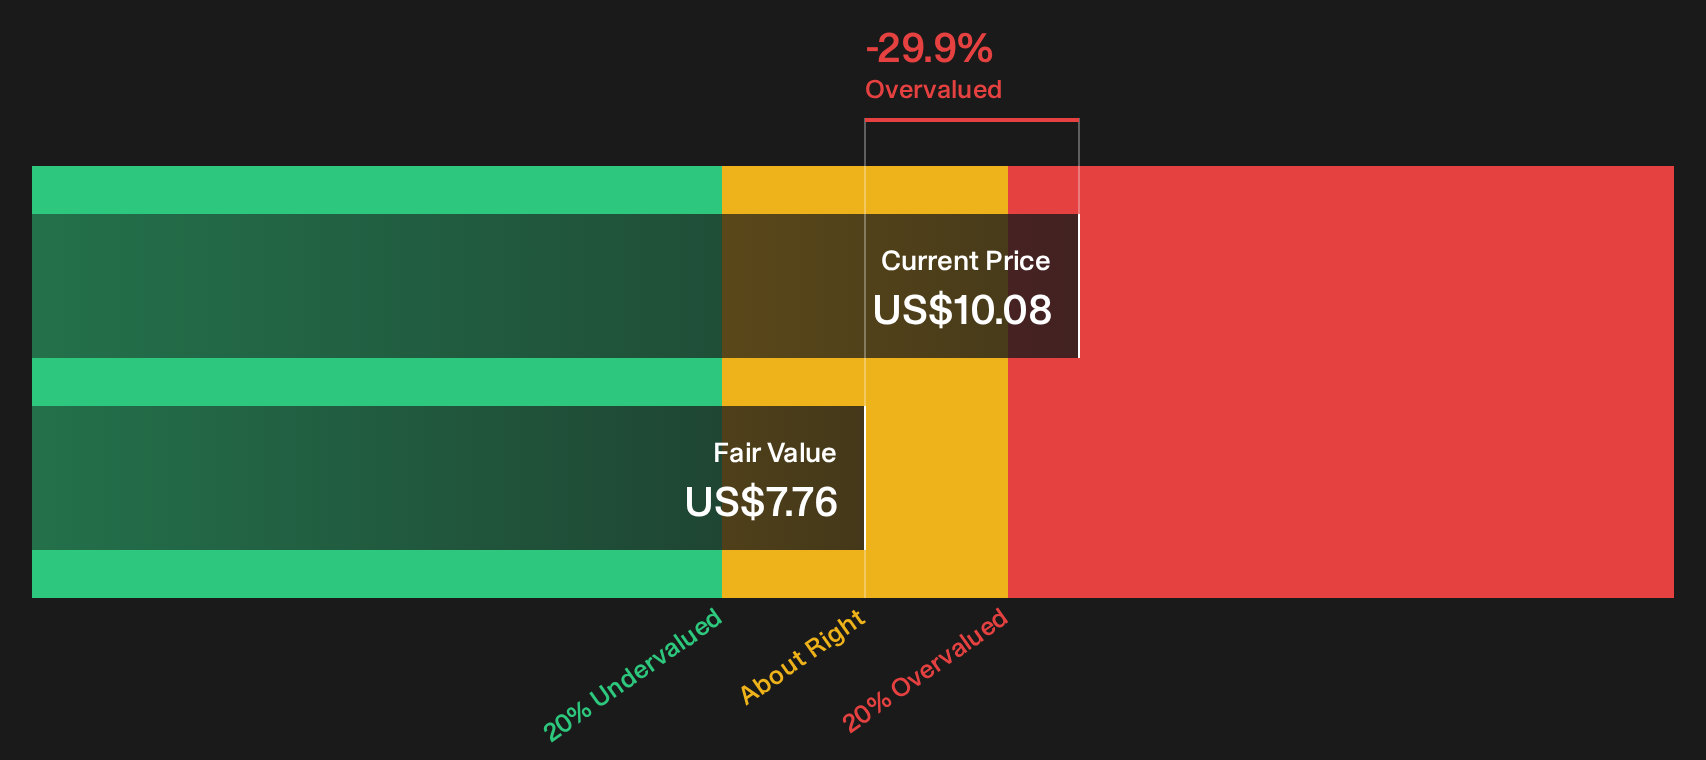
The narrative fair value of $17.00 paints Brookdale Senior Living as undervalued, yet our DCF model points the other way. On a future cash flow basis, BKD at $10.08 is trading above an estimated value of $7.76, which signals an overvalued setup instead. Which lens do you trust more for a business still reporting losses?
For a closer look at how this future cash flow estimate is built and where the key assumptions sit, Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed about Brookdale Senior Living after all that? Act quickly, review the full breakdown, and weigh the 2 key rewards and 1 important warning sign for yourself.
Looking for more investment ideas beyond Brookdale Senior Living?
If Brookdale Senior Living has you rethinking risk, cash flow, and balance sheet quality, then widening your opportunity set with a few focused screens can help clarify your next move.
Do not wait for the market to spell it out for you. Use the Simply Wall Street screener to hunt for ideas that fit your risk tolerance and time horizon.
- Target potential value opportunities by scanning a curated pool of companies that appear financially robust and potentially mispriced through the 27 high quality undervalued stocks.
- Prioritise resilience under pressure by filtering for businesses that carry stronger financial foundations and cleaner debt profiles using the list of solid balance sheet and fundamentals (25 results).
- Focus on lesser known companies with solid fundamentals that appear underfollowed through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com