
Why ALK-Abelló (CPSE:ALK B) Is Getting Attention Today
Why ACARIZAX trial results in China matter for ALK-Abelló stock
ALK-Abelló (CPSE:ALK B) just reported positive phase 3 ACARIZAX data in Chinese patients with house dust mite allergy, clearing a key efficacy and safety hurdle agreed with local regulators.
The trial exceeded its predefined success criterion on symptom control and treatment use, while also supporting a consistent safety profile. Together, these findings strengthen the case for a future regulatory submission in China.
The latest ACARIZAX readout lands after a sharp 30-day share price return of 22.63%, on top of a 7.15% year-to-date share price gain. Total shareholder return over three years is already more than triple, which signals that momentum has been building rather than fading.
Spot 615 high quality undiscovered gems that, like ALK-Abelló after these ACARIZAX results, sit at the intersection of specialised medicine and expanding global patient demand.ALK-Abelló now has fresh clinical proof and a sharply higher share price. The business looks stronger. After this run, does the current valuation still provide enough comfort regarding what you are paying for it?
Most Popular Narrative: 17% Undervalued
ALK-Abelló closed at DKK242.8, while the most followed narrative anchors fair value at DKK291. This gap and the ACARIZAX progress in China frame the valuation debate around how far the current allergy franchise and pipeline can carry earnings.
Recent successful launches and positive momentum for pediatric indications of ACARIZAX and ITULAZAX respiratory tablets are expanding ALK-Abelló's addressable patient pool among children and adolescents, with around 4,500 prescribers having used these products by Q2 2026 and children nearing 30% of new tablet patients, which directly supports continued revenue growth from high tablet volumes.
See why 22 investors see ALK-Abelló as 17% undervalued.
That view uses a discount rate of 5.5% and a fair value of DKK291, which implies the current share price sits at a material discount if those cash flow paths and margins occur as outlined. The same narrative also highlights tablet manufacturing investments, anaphylaxis products and food allergy programs as key swing factors that could either support that fair value or leave the stock looking fully priced if execution or market access disappoint.
Result: Fair Value of DKK291 (UNDERVALUED)
Still, higher mandatory prescription rebates in Germany from 2027 and slower than hoped uptake of EURneffy could quickly challenge the ALK-Abelló undervaluation story.
Find out about the key risks to this ALK-Abelló narrative.
Another Take On ALK-Abelló’s Valuation
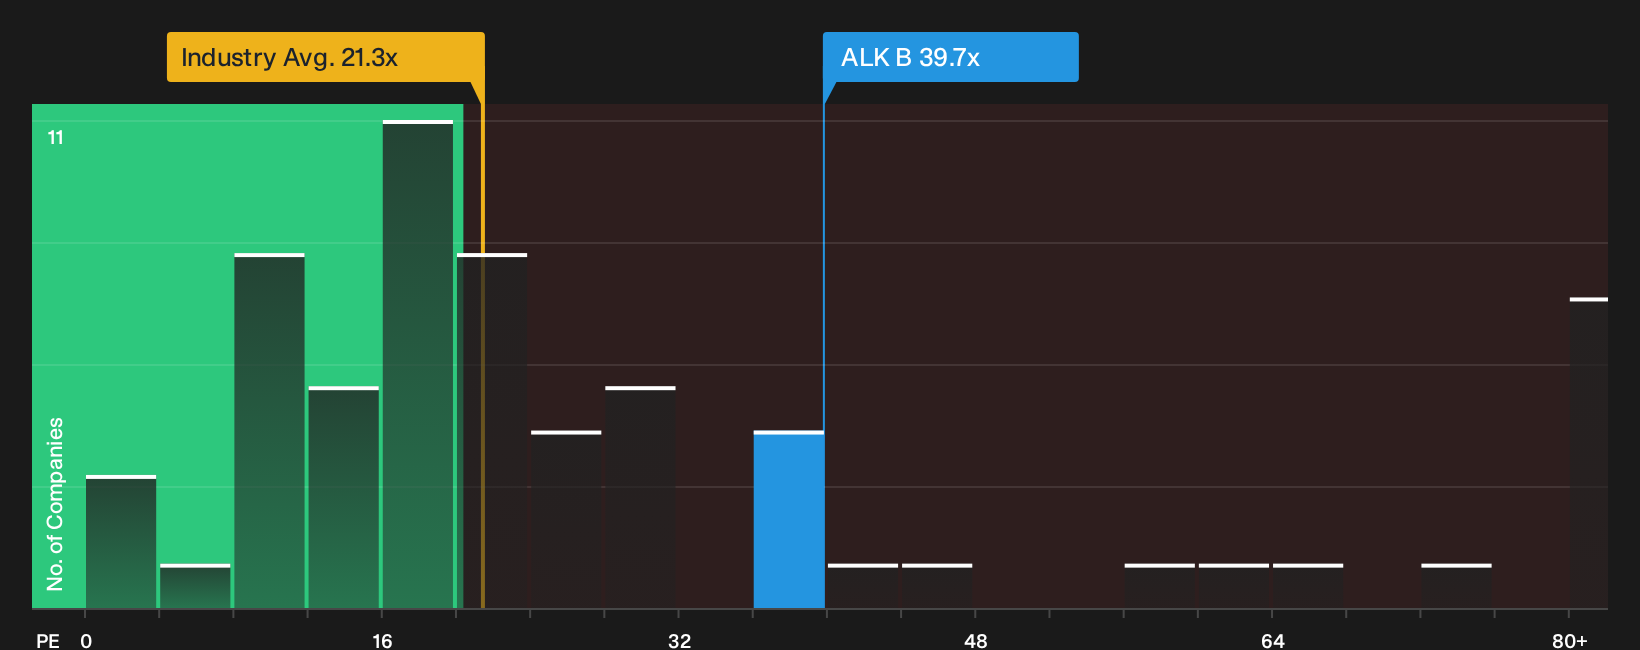
The narrative says ALK-Abelló is undervalued at DKK242.8 versus a DKK291 fair value, yet the current P/E of 39.7x is far above the European pharmaceuticals average of 21.3x, the peer average of 16.3x, and even a fair ratio of 21.8x. Is the market pricing in too much optimism already?
To see how that richer P/E profile compares with the underlying earnings assumptions, and what the numbers imply for future re rating risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all sounds upbeat, use that as a prompt to stress test the numbers yourself and see if the optimism holds. To see which potential upsides our work has flagged and pressure test your own thesis on ALK-Abelló, start with 3 key rewards.
Looking for more investment ideas beyond ALK-Abelló?
If ALK-Abelló has sharpened your focus on quality opportunities, do not stop here. Broader idea hunting can help you avoid concentration risk and spot fresh potential.
- Target potential mispricings by scanning our 192 high quality undervalued stocks and see which businesses the market may be pricing too cautiously today.
- Prioritise resilience by checking the 221 resilient stocks with low risk scores so you can focus on companies with steadier profiles when conditions get bumpy.
- Hunt for possible future standouts early using the 615 high quality undiscovered gems and avoid hearing about compelling opportunities only after they are already crowded.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com