
Lumentum (LITE) Stock May Be Overvalued After AI Connectivity News
Lumentum Holdings has seen its stock price move sharply in recent years, which puts a spotlight on whether the current valuation can be supported by its sales. With that kind of backdrop, the key issue for you is how much revenue strength is already baked into today's share price.
- Over the past 3 years the share price has delivered a very large gain, so a lot of past optimism may already be reflected in how the market values each dollar of sales.
- The recent focus on PCIe over optics for AI rack scale connectivity suggests investors may be tying Lumentum's sales outlook to demand for higher bandwidth data center infrastructure, which can influence how much they are willing to pay for future revenue.
- The analysts covering Lumentum Holdings have run their own numbers. See what analysts think Lumentum Holdings's shares could be worth.
The issue now is whether the current market value of Lumentum is adequately supported by its sales performance and prospects.
If you want to test this same sales based valuation question beyond Lumentum Holdings, compare it to a wider set of 55 AI infrastructure stocks.
Does Lumentum Holdings Look Pricey on Sales?
P/S fits Lumentum Holdings because investors are mainly paying for its ability to turn optical and AI connectivity demand into future revenue rather than near term accounting earnings.
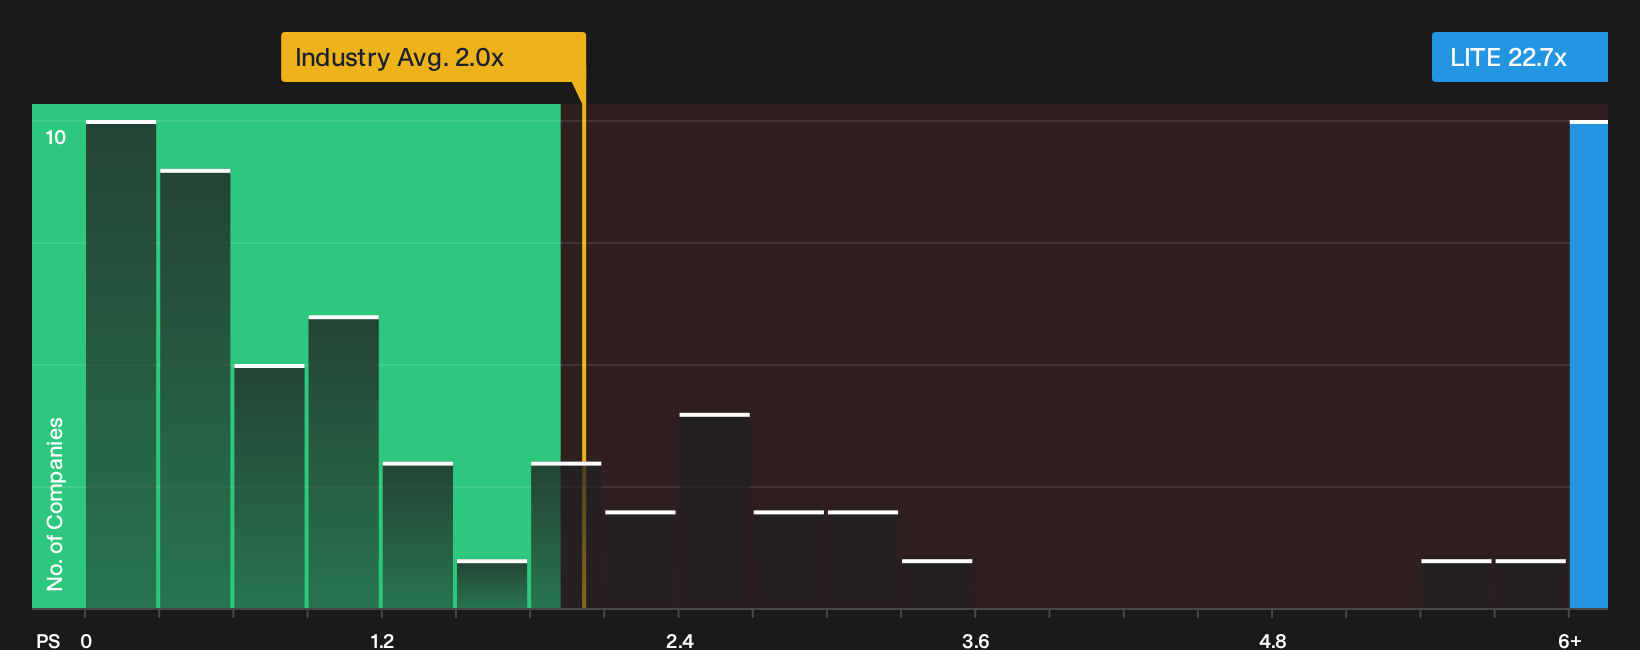
The stock trades on a P/S of 22.7x, which is far above the Communications industry average of 2.0x and also above the peer group on 11.4x. That gap suggests buyers are already assigning a heavy premium to each dollar of Lumentum's sales compared with similar businesses. The model based fair multiple, which looks at the company’s growth profile, profitability, size and risk, sits below the current P/S, so the shares screen as overvalued on this measure.
Because Lumentum is working with partners like Astera Labs and Corning on PCIe over optics for AI rack scale systems, enthusiasm around that opportunity may be helping to support this rich revenue multiple even relative to the tailored fair value anchor. For you as a shareholder or potential buyer, the question is whether the commercial payoff implied by a 22.7x P/S feels realistic given your own expectations for future sales and execution. Explore the numbers behind Lumentum Holdings's P/S valuation.
The Lumentum Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Lumentum Holdings link the rich P/S multiple you have just seen to explicit assumptions about future growth, margins and earnings, so you can see what would need to happen for the stock to be worth materially more or materially less than it is today on the market. Each narrative sets out the key levers behind its fair value view in a clear way, which lets you track those assumptions against Lumentum Holdings' actual results over time. Narratives sit on Simply Wall St's Community page, where you can weigh those different paths against your own expectations before deciding how much risk around that 22.7x sales multiple feels acceptable.
One of the top community narratives on Lumentum Holdings: 85% undervalued
"The numbers look dramatic, revenue has surged, gross margins have vaulted into the mid 40s, and the market now values Lumentum at US$73.67b..."
Discover why this Narrative puts Lumentum Holdings at 85% undervalued.
Lumentum Holdings’ valuation still leaves one crucial piece out
The price on Lumentum Holdings only tells part of the story, because the people directing capital and how they are rewarded can pull outcomes in very different directions. See who runs Lumentum Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com