
How Investors May Respond To Amalgamated Financial (AMAL) Record Earnings Outlook Raise
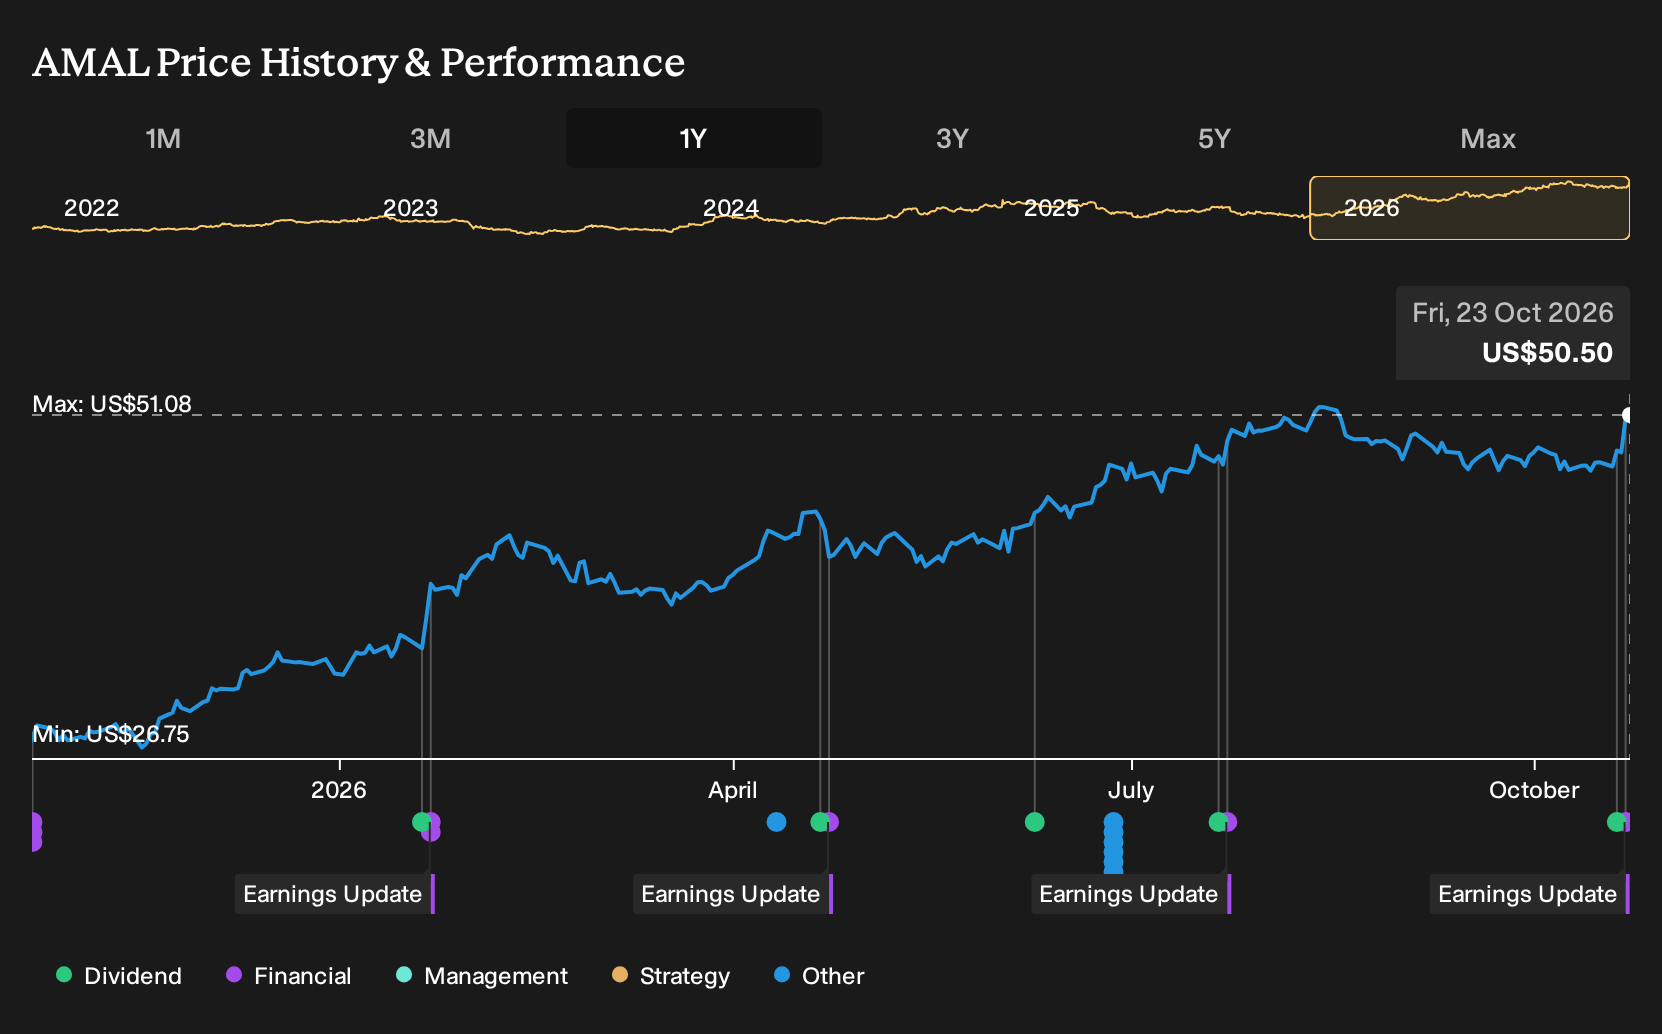
- Amalgamated Financial reported Q3 2026 net income of US$36.43 million and basic EPS of US$1.22, with nine month net income reaching US$96.42 million and basic EPS of US$3.23, alongside a regular US$0.17 per share dividend declared for November 2026.
- The latest results show Amalgamated Financial pairing record profitability with ongoing capital returns through dividends, while also emphasizing technology spending, higher yielding commercial and PACE lending, and share repurchases as key priorities.
- We will now examine how Amalgamated Financial's investment narrative could be influenced by its record quarterly earnings and raised full year outlook.
See how Amalgamated Financial's latest earnings story compares with other high quality banks and lenders by reviewing 27 high quality undervalued stocks, which is built around solid cash flows and balance sheets.
Amalgamated Financial Investment Narrative Recap
To own Amalgamated Financial, you need to be comfortable with a bank that relies on mission-aligned, often election-sensitive deposits, while also increasing its exposure to higher-yielding commercial and PACE lending. The Q3 2026 report, with record earnings and net revenue above US$100 million, indicates that credit costs and net interest margin are currently tracking within management commentary.
The key near-term swing factor is how quickly political balances run off into Q4 and how that funding is replaced. Management has already flagged modest margin compression tied to this deposit shift, so the latest quarter largely confirms that risk rather than altering it. Credit concentration in specific renewable and multifamily relationships remains a key watchpoint.
The raised full-year outlook for net interest income and core pre-tax, pre-provision earnings is the clearest operational takeaway from the earnings announcement. For a shareholder, that guidance may matter more than the near-term share price reaction, because it connects the stronger Q3 to loan mix, fee income and expense control over the next few quarters.
At the same time, that upgraded outlook exists alongside ongoing risks in credit quality and deposit mix. Higher-yielding commercial and C PACE loans and ongoing technology spending may support returns if execution remains disciplined, but larger-than-modeled political deposit outflows or additional problem credits could offset that potential benefit. Analysts currently frame Amalgamated Financial as a Hold, which highlights that trade-off.
Analysts suggest Amalgamated Financial could reach US$501.8 million in revenue and US$169.8 million in earnings by 2029. This would imply forecast revenue growth of 14.6% per year and an earnings increase of about US$56.4 million from current earnings of US$113.4 million.
Uncover why Amalgamated Financial's fair value points to a 7% potential upside to its current price. This gap could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view on Amalgamated Financial focuses on rising operating costs rather than political deposits. The most cautious analysts were penciling in about US$505.8 million of revenue and US$176.2 million of earnings by 2029, yet still applied a lower 11.0x P/E. That signals a more pessimistic narrative you may want to compare against the strong Q3 update.
Explore another Amalgamated Financial fair value estimate, including one that suggests it could be worth just $54.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amalgamated Financial research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Amalgamated Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amalgamated Financial's overall financial health at a glance.
Looking for more Amalgamated Financial style ideas?
If the Amalgamated Financial story has sharpened your view on banks and lenders, it can help to benchmark it against other opportunities that share some of the same financial traits without the same deposit profile or lending mix.
- If you want income with fewer surprises, you could focus on businesses that combine higher yields with balance sheets built to withstand stress tests by starting with 5 dividend fortresses.
- If resilience matters more to you than excitement, you could concentrate on companies that pair sturdy finances with lower risk scores through the 30 resilient stocks with low risk scores.
- If you are hunting for underfollowed opportunities backed by real fundamentals rather than hype, you could widen your search with the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com