
Getinge (OM:GETI B) Could Be 6% Overvalued After Strong Q3 Margins
Getinge (OM:GETI B) moved back into focus after its Q3 2026 report, as investors weighed higher adjusted EBITA margins, stronger net income, and heavier recurring revenue against tariff, China, and quality cost pressures.
Recent trading reflects that story. Getinge’s 1 month share price return of 8.9% and 90 day share price gain of 16.2% suggest momentum has picked up. At the same time, a 1 year total shareholder return of 23.2% and 3 year total shareholder return of 50.7% point to a recovery that is still working through earlier long term underperformance, including a 5 year total shareholder return that is down 23.1%.
Scan other hospital equipment stocks showing similar earnings resilience and recurring revenue support with our curated list of 192 high quality undervalued stocks.
Bulls point to Getinge’s recurring revenue and margin gains, while bears focus on tariffs, China and quality costs. After the recent share price jump, which side does the valuation now reward?
Most Popular Narrative: 6% Overvalued
Against a last close of SEK267.7, the most widely followed valuation view for Getinge points to a fair value of SEK252.2. This frames the recent share price strength as running ahead of that reference point. That gap puts the spotlight squarely on whether recurring revenue and margin work can offset tariff, China and quality overhangs already built into that narrative.
The current valuation suggests that Getinge is fairly valued and already reflects a mix of continued margin progress, growth in franchises such as Sterile Transfer and Acute Care Therapies, and manageable pressure from China and tariffs.
See why 8 investors see Getinge as 6% overvalued.
Result: Fair Value of SEK252.2 (OVERVALUED)
Still, higher tariffs and stubborn cost inflation, especially in China and long term contracts with fixed pricing, could quickly challenge that consensus on Getinge.
Find out about the key risks to this Getinge narrative.
Another View: Getinge Through The P/E Lens
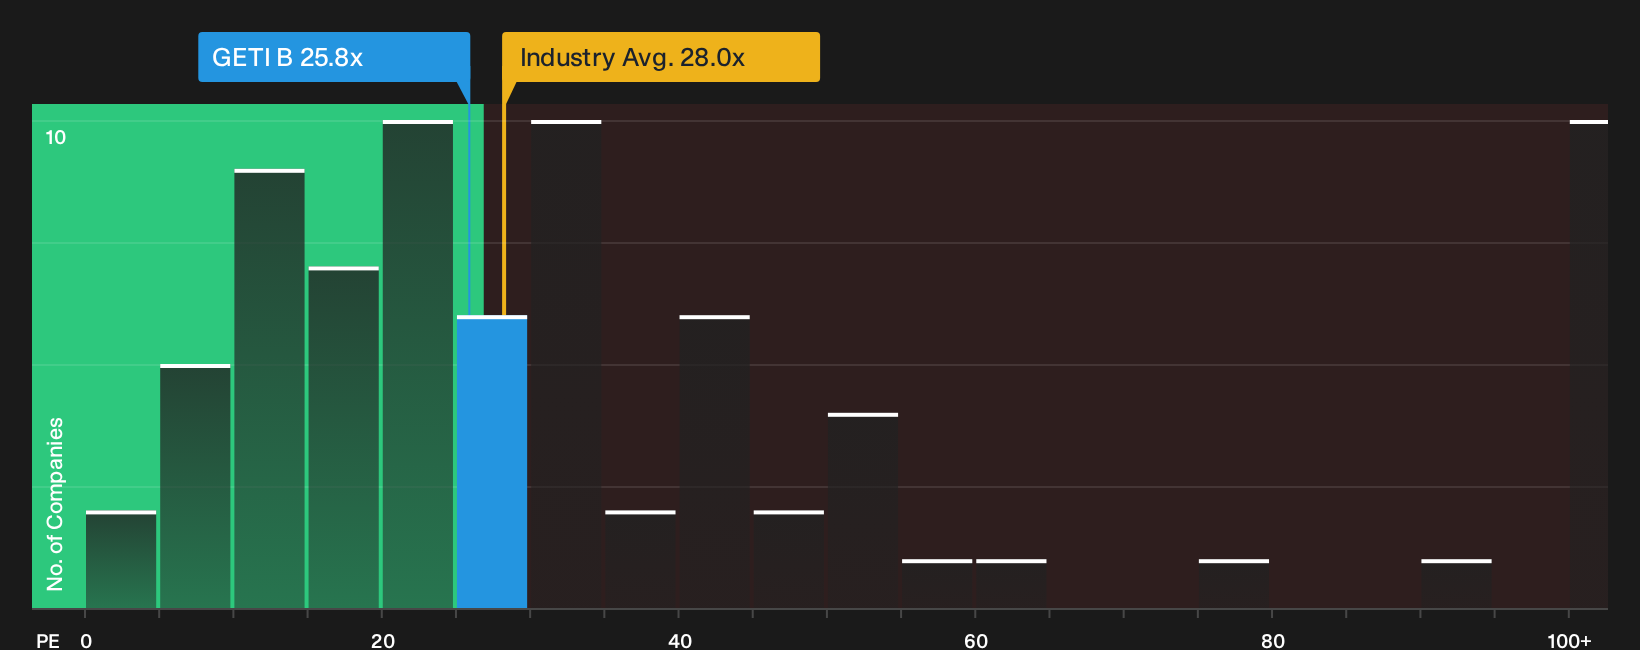
Analysts flag Getinge as about 6% above their SEK252.2 fair value, yet the current P/E of 25.8x sits below both the European Medical Equipment group at 28x and peers at 30.2x, and under its own 29.1x fair ratio. Is the earnings multiple hinting at less downside than the target price implies?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of cautious and optimistic views on Getinge feels familiar, consider acting promptly and examining the data for yourself. Start by weighing 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Getinge?
You have seen how one stock’s story can shift fast. Do not stop here. Broaden your watchlist so you can compare Getinge against fresh ideas.
- Target stronger income potential by reviewing dependable payers in the 226 dividend fortresses.
- Spot financially resilient businesses by scanning the list of solid balance sheet and fundamentals (204 results).
- Get ahead of the crowd by tracking future contenders in the 615 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com