
What KB Home (KBH)'s Earnings Beat Means For Shareholders
- KB Home reported fiscal Q3 2026 earnings and revenue that beat forecasts despite year over year declines, supported by a higher mix of Built to Order homes and sequential margin improvement.
- The opening of Sebastian Oaks in St. Augustine adds fresh Florida product with ENERGY STAR certified designs and buyer personalization, reinforcing KB Home’s focus on efficiency, health oriented features and value in a tougher housing backdrop.
- We will look at how KB Home’s investment narrative is affected by its earnings beat and heavier Built to Order mix.
KB Home Investment Narrative Recap
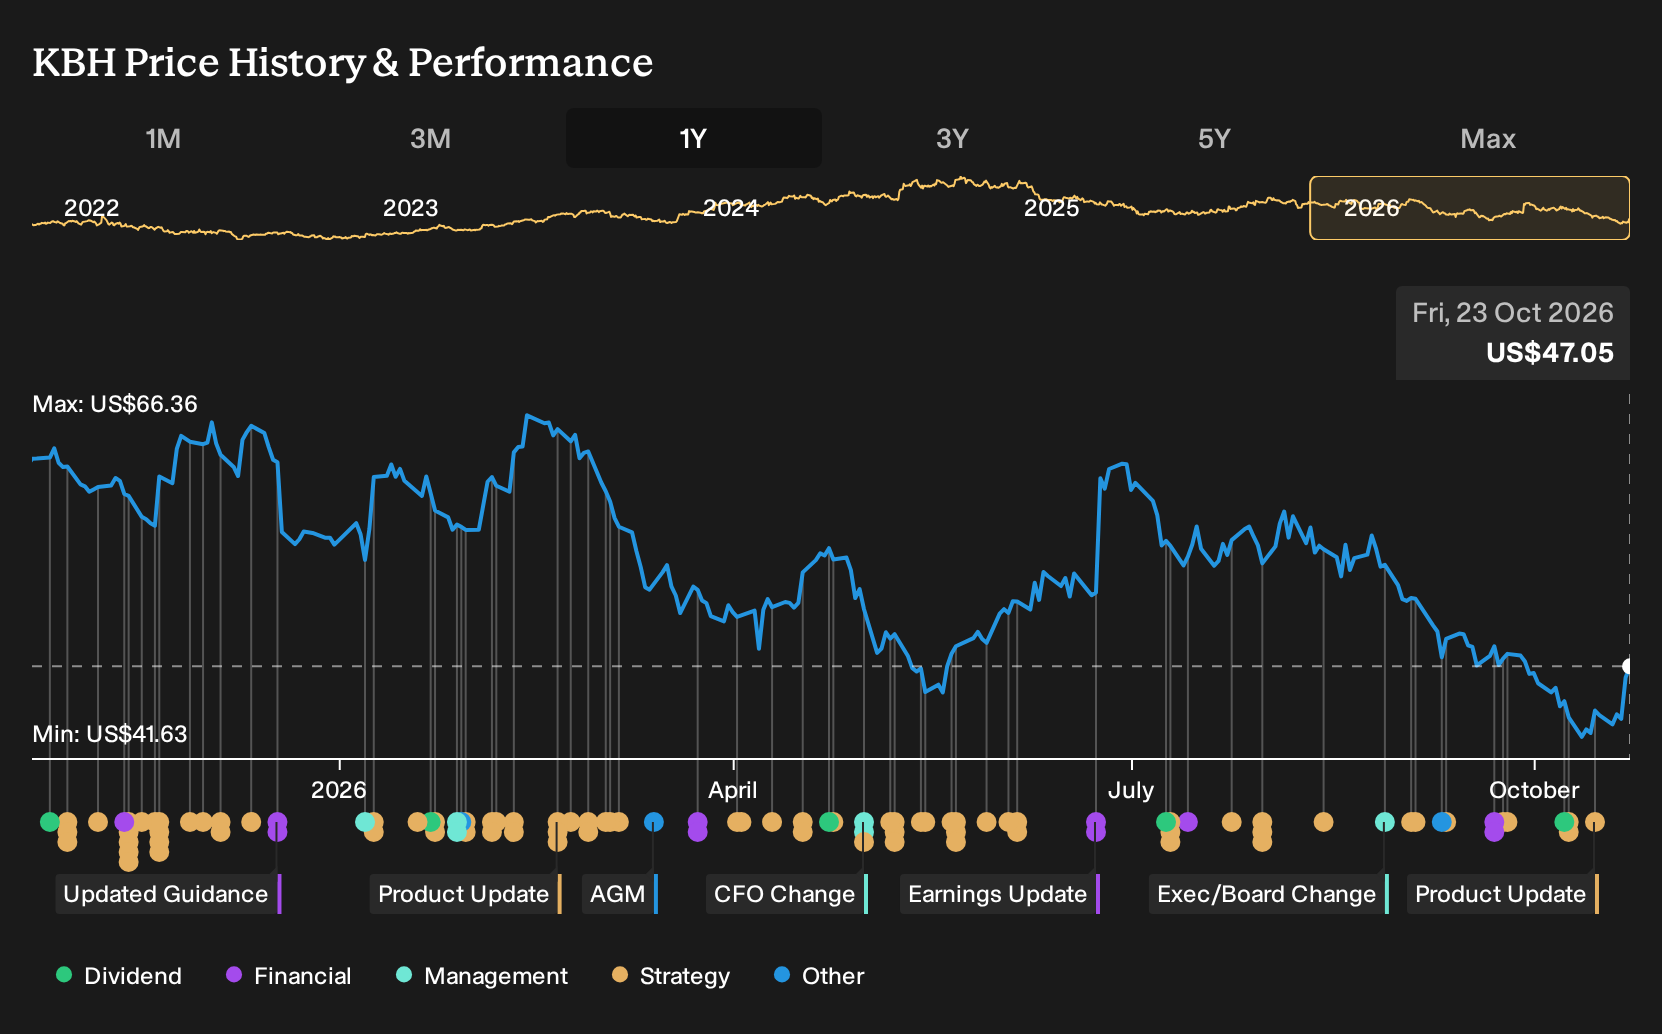
To own KB Home, you need to believe the Built to Order engine, faster build times and a deep lot pipeline can offset softer demand, pricing pressure and higher mortgage costs. The latest quarter did beat earnings expectations, yet revenue and profit still declined, which keeps the focus on execution rather than momentum.
Near term, the key swing factor is whether KB Home can hold housing gross margin as resale inventory and incentives rise around it. The biggest risk remains a further drop in buyer confidence that forces deeper discounts or lower deliveries, which could pressure both margins and cash generation.
The Sebastian Oaks launch in St. Augustine is the clearest operational tie in to that margin and growth story. It adds another Florida community with ENERGY STAR certified product, personalization through the Design Studio and price points starting in the low US$300,000s, all aligned with KB Home’s value and efficiency pitch.
For catalysts, what matters is less the marketing language and more that Sebastian Oaks taps an existing lot base, feeds the Built to Order mix and relies on standardized, efficient construction. Execution risk sits in how quickly homes there convert to firm orders without heavy discounting, especially with broader housing demand already under pressure.
What The KB Home Forecasts Assume
Analysts sketch a KB Home path that leans on modest expansion rather than a sharp rebound. Consensus assumptions point to revenue rising by 2.1% a year over the next three years, supported by a small lift in profit margins from 4.4% today to 5.0% by 2029.
Earnings today are pegged at US$226.4 million, with forecasts calling for US$275.1 million by 2029. That implies an increase of roughly US$48.7 million in profit over the period, with upside scenarios that reach as high as US$334.0 million if more optimistic views prove accurate.
On these numbers, the stock would need to trade on a P/E of 13.5x 2029 earnings, up from 11.6x now and above the current 12.7x multiple for the wider US Consumer Durables group. That gap indicates analysts are incorporating some improvement in execution and capital allocation beyond what the broader peer set is pricing today.
KB Home's narrative projects revenues of US$5.5b and earnings of US$275.1 million by 2029. This rests on analysts assuming 2.1% yearly revenue growth and an earnings increase of about US$48.7 million from US$226.4 million today.
Uncover why KB Home's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a different angle, focus on the bullish catalyst. The most optimistic analysts see KB Home’s heavier Built to Order and higher priced markets as a springboard, with revenue growth assumptions of 4.1% a year and earnings reaching about US$340.6 million by 2029. These views were set before Sebastian Oaks, so you may want to revisit how this new community could shift those expectations, either up or down, as fresh data comes through.
Explore 2 other KB Home fair value estimates, including one that suggests as much as 10% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your KB Home research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for KB Home. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KB Home's overall financial health at a glance.
Looking For More Investment Ideas Beyond KB Home?
If KB Home has sharpened your view on housing and capital discipline, it can be useful to widen the lens and see how other businesses stack up on balance sheet strength, income potential and valuation quality using the Simply Wall St Screener.
- For resilience first investors, filter for conservative leverage and ample liquidity with the 30 resilient stocks with low risk scores.
- If you care more about dependable income streams, scan for payout strength and yield support using the 5 dividend fortresses.
- When you want quality at a reasonable price, start with companies that pair solid fundamentals with appealing valuations through the 27 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com