
TriMas (TRS) Could Be 12% Undervalued On Its Fresh Dividend Declaration
TriMas (TRS) set its next shareholder payout in motion as the Board declared a quarterly cash dividend of $0.04 per share, with a record date of November 5 and a payment date of November 12, 2026.
TriMas shares trade at $39.60, with a 7-day share price return of 2.19% and a year to date share price gain of 9.12%, while the 1-year total shareholder return is slightly negative at 0.46% and the 3-year total shareholder return of 69.89% points to stronger, longer-run momentum.
Scan beyond TriMas and line up other dividend-paying industrials with resilient balance sheets using our handpicked list of solid balance sheet and fundamentals (25 results) for comparison.
The share price has strengthened and TriMas trades below the average analyst target, yet its own intrinsic value estimate suggests a different picture. Is the market simply being cautious, or is it reflecting risks investors should consider?
Most Popular Narrative: 12% Undervalued
TriMas last traded at $39.60, while the most followed narrative pegs fair value at $45, so the current dividend sits against a valuation gap that centers on how the business uses its Aerospace sale proceeds and executes on cost savings.
The main thing that has to go right is that TriMas successfully deploys its more than US$1.2b of Aerospace divestiture proceeds into disciplined M&A, share repurchases, and organic investments, while delivering the planned US$15 to US$16m of annual cost savings and improved execution at Norris Cylinder.
See why 1 investors see TriMas as 12% undervalued.
Result: Fair Value of $45 (UNDERVALUED)
Still, the TriMas story can break if Packaging faces tougher sustainability rules that compress margins, or if Norris Cylinder’s operational issues drag on longer than expected.
Find out about the key risks to this TriMas narrative.
Another View: TriMas Through The Cash Flow Lens
The first fair value story for TriMas leans on earnings and analyst targets, yet the SWS DCF model paints a sharply different picture. In this framework, TRS at $39.60 trades far above an estimated future cash flow value of $4.52, which flags a wide gap between price and implied cash generation. For investors weighing these models, the key question is which risk matters more: paying up for cash flows today or relying on the earnings path that underpins the $45 narrative.
For a closer look at how this cash flow view is built and where the key sensitivities sit, Look into how the SWS DCF model arrives at its fair value.
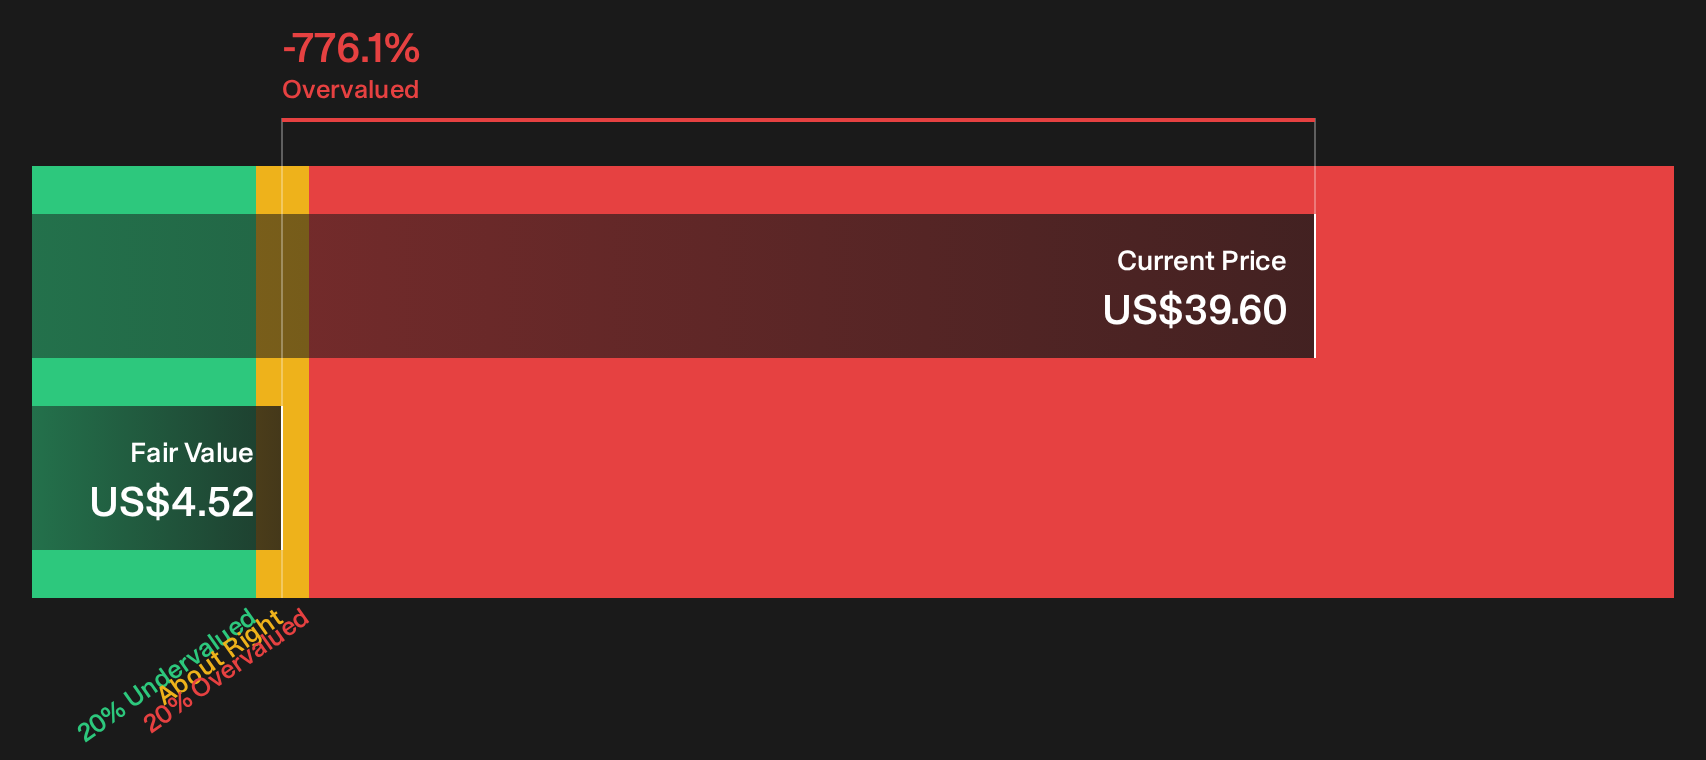
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TriMas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
TriMas presents mixed signals so far, with both risks and rewards on the table. Pressure test the numbers yourself and then weigh the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond TriMas?
TriMas gives you one angle on income and valuation. Do not stop there. Broaden your watchlist with a few focused idea sets that match different goals.
- Target steady cash generators by scanning 5 dividend fortresses built around companies prioritizing income strength and payout resilience.
- Hunt for tomorrow's potential standouts through 21 high quality undiscovered gems where strong fundamentals meet lower market attention.
- Dial down portfolio stress by filtering companies through 30 resilient stocks with low risk scores that emphasise balance sheet resilience and cleaner risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com