
Is Profit Warning Altering The Investment Case For Carrefour (ENXTPA:CA)?
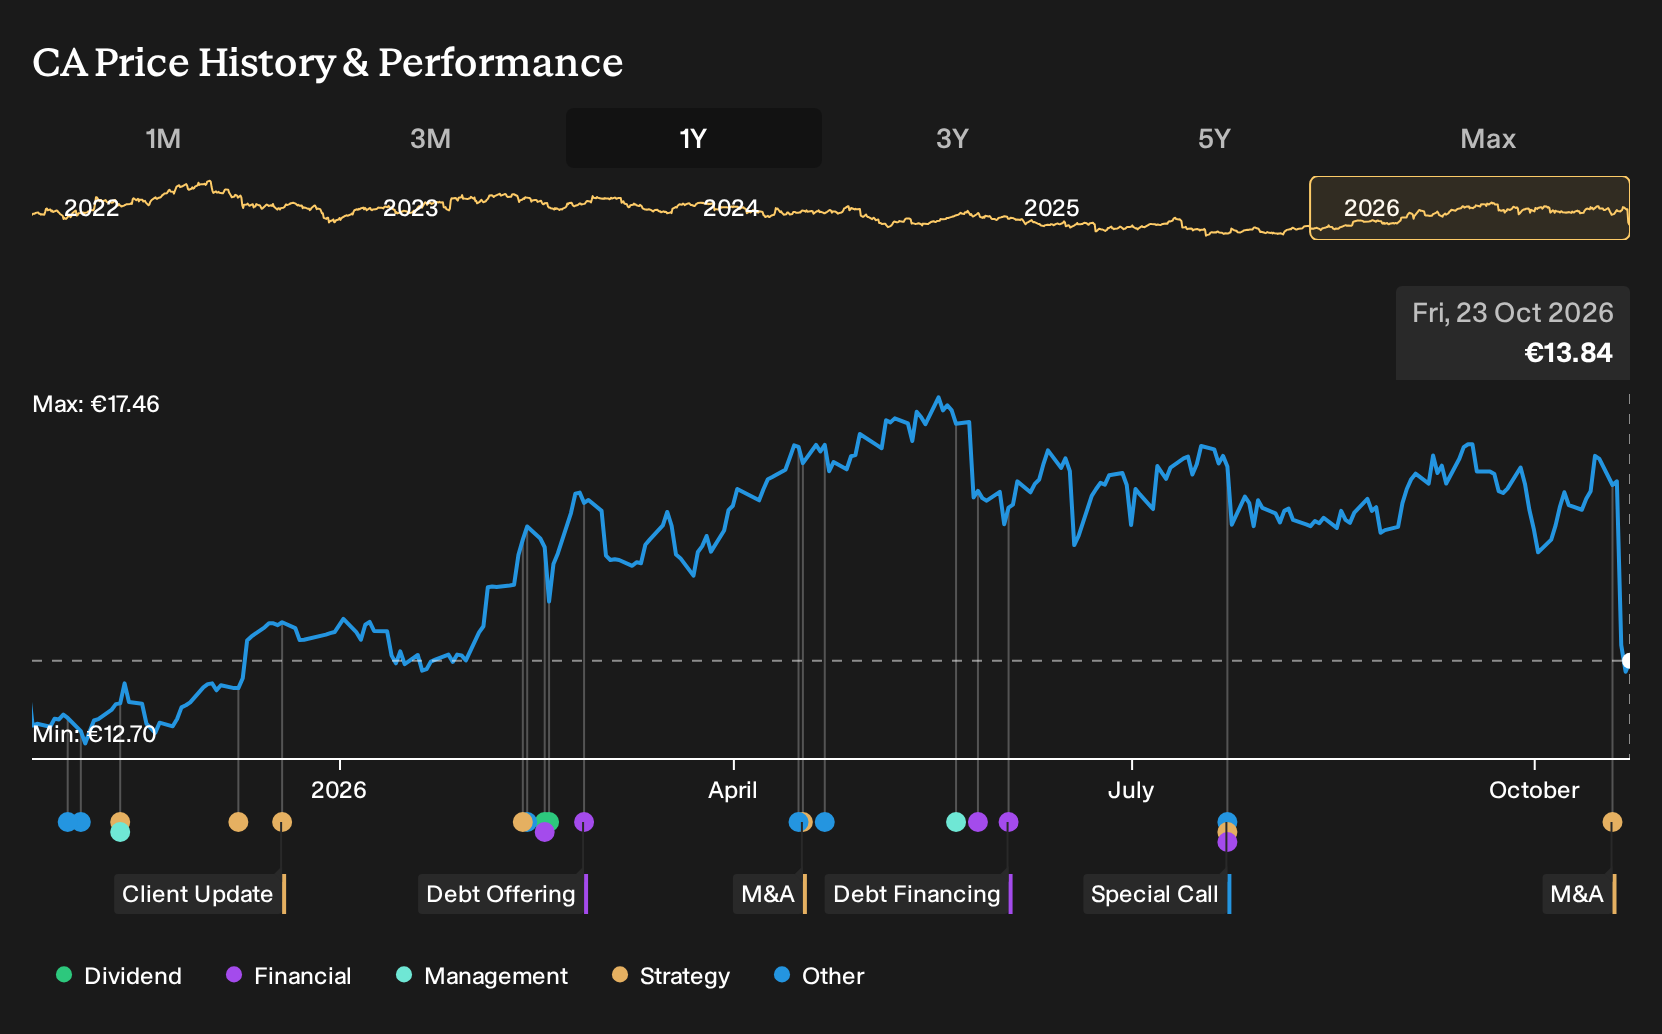
- Carrefour issued a profit warning after unrest in France weighed on September trading and created pressure on earnings expectations for the key fourth quarter.
- The episode highlights how concentrated exposure to the French food retail market can quickly strain Carrefour's profitability when local demand or operations are disrupted.
- We will now explore how Carrefour's investment narrative aligns with this profit warning linked to French unrest and weaker near term visibility.
Carrefour Investment Narrative Recap
To own Carrefour today, you need to believe the retailer can keep French food retail profitable while offsetting pressure with cost savings, e commerce growth and international operations like Brazil and Spain. The recent French unrest and weak September trading have clouded near term visibility on volumes and pricing, especially in its largest market.
The key short term catalyst is whether Carrefour can stabilise fourth quarter trading in France while holding margins through its €1.2b cost reduction plan and store revamps. The biggest current risk is that softer French consumption and competitive pricing in Europe persist, which would keep profit margins and earnings under pressure.
The most relevant update tied to this setback is the profit warning that led several brokers to trim their fair value estimates for Carrefour and lower earnings forecasts. UBS now expects 2026 earnings per share of €1.62 instead of €1.72, pointing to lower operating profit and market share assumptions after the disruption in France.
For you as a shareholder, the catalyst to monitor is how actual operating profit for the next year lines up against that revised earnings path, given analysts see potential French unrest impact of €80 million to €200 million on operating profit. Execution on cost savings and portfolio review matters more now that external demand shocks have tested Carrefour’s resilience.
Carrefour’s consensus narrative points to revenues of €86.2b and earnings of €1.2b by 2029, based on analyst assumptions that revenue stays broadly flat and profit margins rise from 1.1% today to 1.4%. That path implies earnings would need to increase by about €289m from current earnings of €911.0m.
Uncover why Carrefour's fair value points to an 18% potential upside to its current price, which could narrow faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic Carrefour analysts were banking on AI and store digitalization as the real swing factor, backing scenarios with revenue of about €91.9b and earnings near €1.5b by 2029. You can now compare that upbeat story with today’s profit warning and consider how far those forecasts may need to shift.
Explore 2 other Carrefour fair value estimates, including one that suggests there could be as much as 69% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Carrefour research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Carrefour. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Carrefour's overall financial health at a glance.
Looking for more investment ideas beyond Carrefour?
Once you have a view on Carrefour, it can help to balance your portfolio by scanning for other businesses that fit your preferred risk and income profile using the Simply Wall St Screener.
- For investors who want potential upside with strict quality filters, review a carefully curated 615 high quality undiscovered gems that screens for strong fundamentals and cleaner balance sheets.
- If capital preservation and steadier profiles matter most, consider a focused 221 resilient stocks with low risk scores aimed at resilient companies with lower risk scores.
- Income focused readers can zero in on reliable payers through a targeted 226 dividend fortresses that highlights higher yield opportunities with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com