
3 Undervalued Stocks Trading Up To 48% Below Fair Value
AI euphoria has cooled sharply after OpenAI cut its valuation by US$150b, reminding investors that big themes can get too crowded and too expensive. That kind of reset often leaves solid businesses trading well below what their future cash generation could justify. This article focuses on US companies where projected cash flows look attractive relative to current prices and highlights three standouts from this undervalued cash flow screen.
The three companies highlighted below are just a starting sample, as the full Undervalued Stocks Based On Cash Flows screen surfaced 90 more businesses with cash profiles and valuation gaps that look equally compelling but are not covered in this article.
To size up the full opportunity set quickly, head straight into the Undervalued Stocks Based On Cash Flows screener to identify potential mispriced cash generators, analyze their DCF outputs, and focus on the ideas that best fit your own conviction.
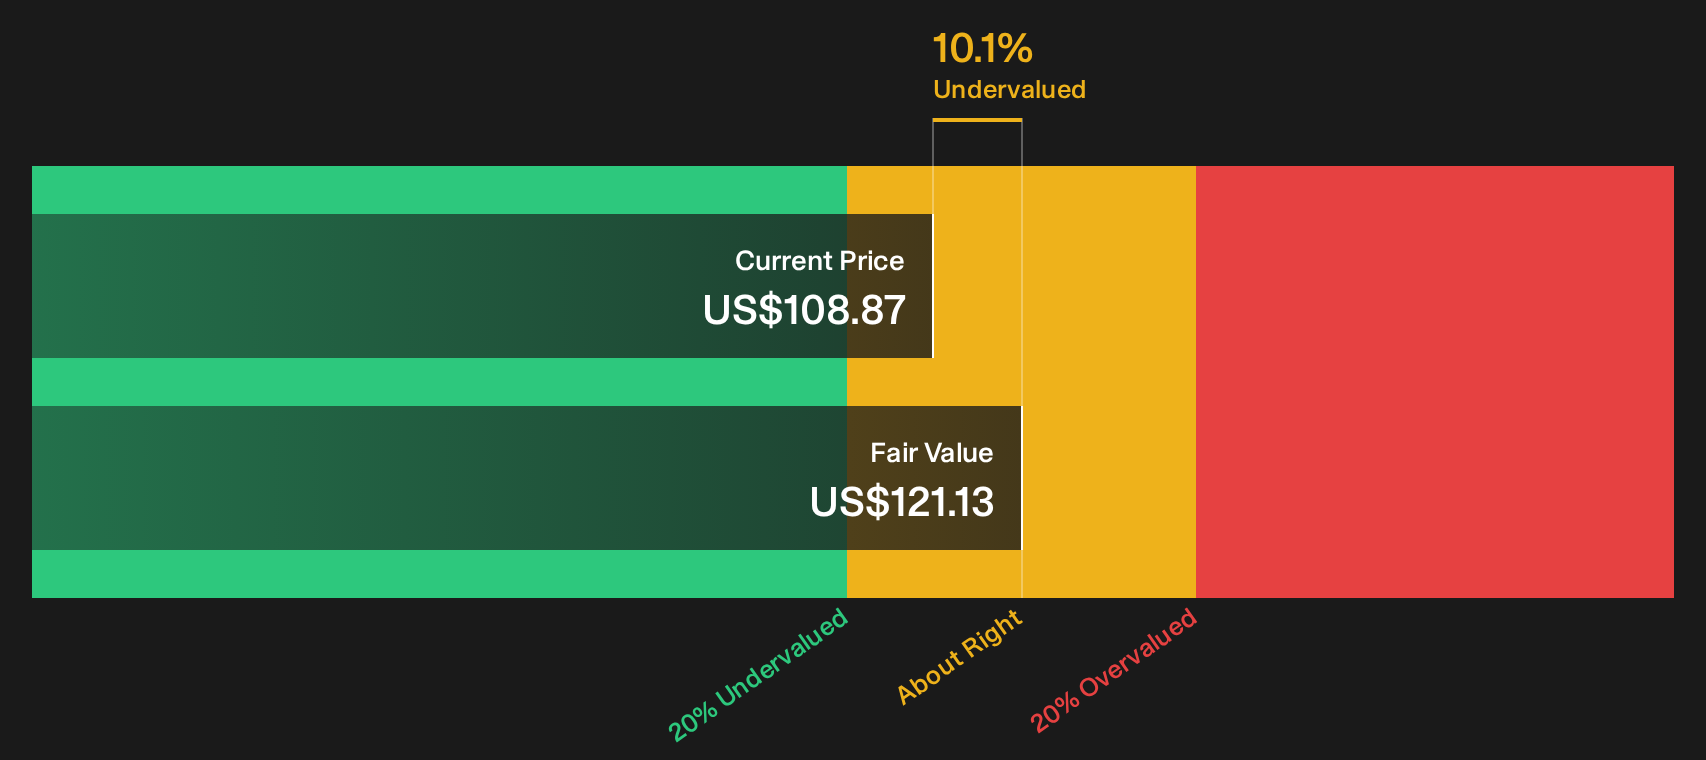
Newmont (NEM)
Overview: Newmont is a US based gold producer that mines, processes, and sells gold globally, with additional exposure to copper and other metals.
Market Cap: US$118.9b
Newmont matters for this cash flow focused screen because its large gold portfolio generates significant operating cash. The DCF work suggests the market is not fully pricing this in today.
"Newmont's focus on operational stability, cost discipline, and productivity enhancements (e.g., at Lihir, Boddington, and across its core assets) is expected to drive lower operating costs and improved EBITDA margins, positioning the company for margin expansion and stronger net income over time."
What happens to that margin story if a single pressure on future gold pricing and project delivery does not break Newmont’s way?
If that risk swing matters to you, read the full narrative for Newmont to see how Newmont’s cash engine could still accelerate even if gold prices wobble.
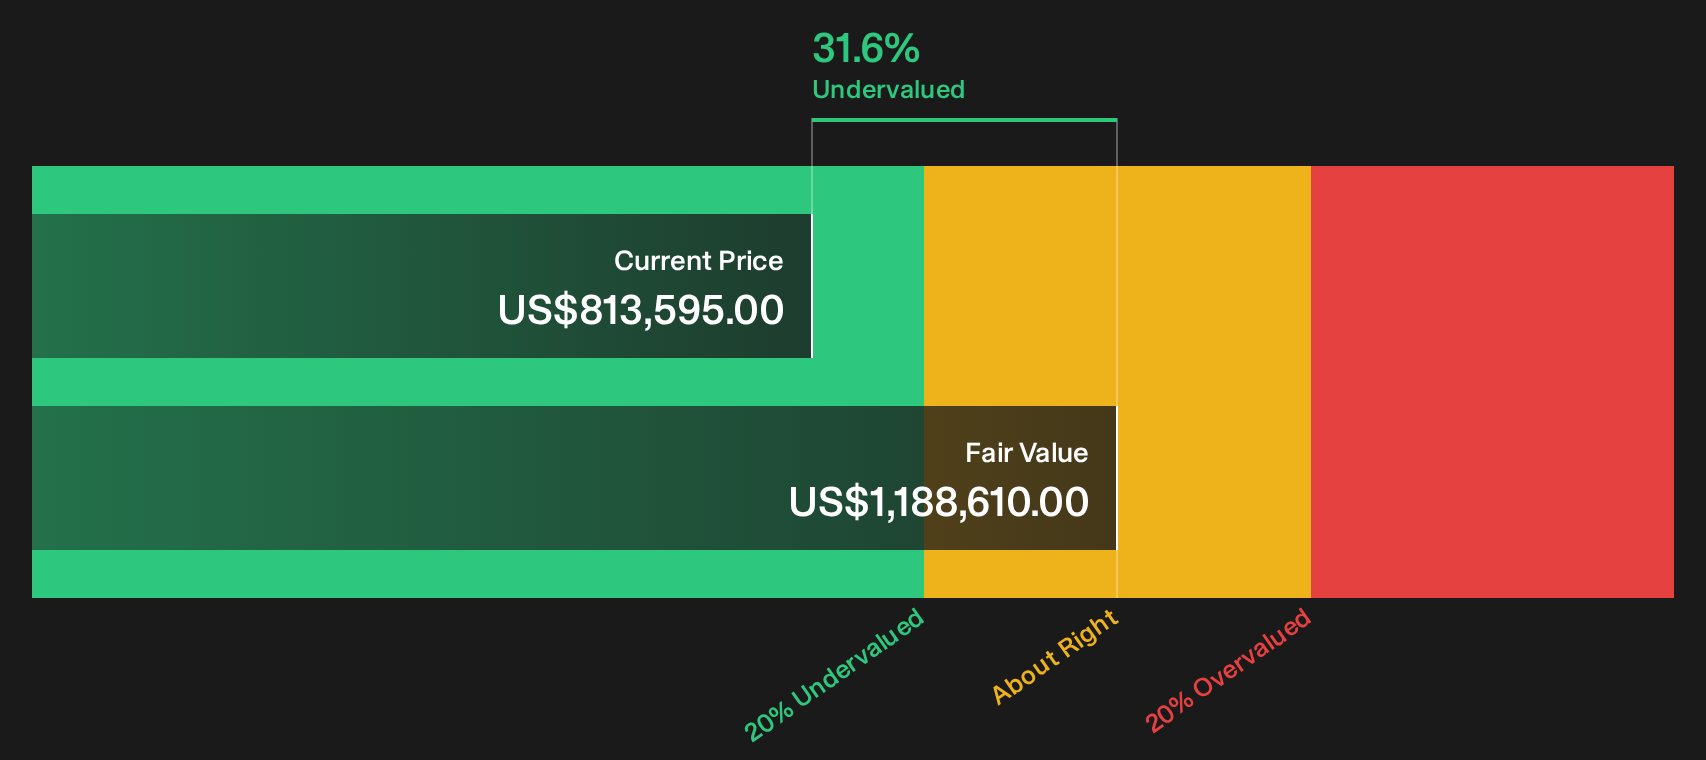
Berkshire Hathaway (BRK.A)
Overview: Berkshire Hathaway is a diversified US holding company whose insurance operations generate large recurring cash flows that fund rail, energy, manufacturing, and retail businesses.
Operations: The group earns most of its revenue from Manufacturing at US$82.99b, with sizeable contributions from GEICO at US$45.14b and other insurance units.
Market Cap: US$1.17t
Berkshire Hathaway matters for this cash flow focused screen because its insurance float and investment portfolio create a significant cash engine that can be redeployed into rail, energy, housing, and equity stakes when prices look attractive.
"The company's cash and short-term Treasuries hit $397.4 billion. They may continue deploying capital into Treasury bills and could wait for opportunities to adjust stakes in high-conviction positions such as Occidental Petroleum (OXY) and Chubb (CB), or to pursue a large energy infrastructure acquisition."
What happens to Berkshire’s cash compounding story if a single assumption about future reinvestment opportunities and pricing power fails to hold?
If that reinvestment risk sits on your mind, read the full narrative for Berkshire Hathaway to see how Berkshire Hathaway’s cash pile could accelerate or stall future compounding.
Amazon.com (AMZN)
Overview: Amazon.com runs global online and physical retail stores, subscriptions, advertising, and AWS cloud services that generate substantial cash flows.
Operations: The business generates US$453.7b from North America, US$173.6b from International, and US$148.4b from AWS cloud services.
Market Cap: US$2.7t
Amazon.com matters for this cash flow focused screen because AWS throws off high quality cash from cloud and AI services that supports the DCF signal while retail and advertising add extra profit pillars around it.
"AWS remains the primary value driver. After the optimization cycle of 2023 to 2024, AWS reaccelerated through 2025 with roughly 20% year-over-year growth, exiting the year with an annualized revenue base exceeding $130 billion."
What happens to Amazon.com’s earnings power if a single assumption about how quickly that AI heavy cloud spend pays back does not hold?
That uncertainty is exactly why the full narrative for Amazon.com digs into how Amazon.com’s cash machine could keep accelerating even if AI heavy cloud paybacks stall.

Seeking Fresh Alternatives Beyond These Cash Machines
The next wave of breakout ideas often moves before the crowd even notices. Scan fresh cash generators while valuations still look grounded and sentiment has not fully caught up. Consider exploring potential opportunities early.
- Track high yielders before income hunters pile in by scanning 5 dividend fortresses that focus on payouts which may help support portfolios when prices swing.
- Spot early AI momentum where earnings already back the story by checking 39 profitable AI stocks that aren't just burning cash that filter for businesses generating real cash instead of just burning capital.
- Review potential resource catalysts by looking at 35 elite gold producer stocks that group established producers with balance sheets structured to handle volatile commodity cycles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com