
Should Öland Bridge Contract Require Action From NCC Stock Investors?
- NCC has reported several new projects, including a SEK 680 million Swedish Transport Administration contract to refurbish the Öland Bridge while it remains in use, plus building and renovation assignments in Helsinki and Örkelljunga.
- The cluster of infrastructure and social-building wins adds volume across NCC Infrastructure and Building Nordics, highlighting how public-sector demand is feeding into the order book.
- We will now look at how NCC's investment narrative is affected by the Öland Bridge refurbishment win and related project awards.
NCC Investment Narrative Recap
To own NCC, you need to believe the contractor can turn a solid order pipeline into healthier margins while working through dispute costs, weak Property Development earnings and high debt. The short term swing factor remains how well the core construction units execute higher quality projects without new large loss making contracts dragging on already thin 0.1% profit margins.
The new bridge, school and leisure projects help support the contracting backlog but do not change the key near term risk. Legal disputes tied to terminated work and a dividend that is not well covered by earnings and free cash flow still put pressure on cash generation, while the NCC Industry divestment and future property disposals remain central catalysts.
The Öland Bridge refurbishment extension looks most relevant for NCC right now. It provides a SEK 680 million infrastructure contract running from 2027 to 2030 that lands in the order book in Q4 2026 and fits cleanly with management’s push toward a more focused contracting profile after the planned NCC Industry sale.
This kind of long duration public infrastructure work can help support the order backlog that already grew by SEK 5.2 billion over six months in early 2026. For you as a shareholder, the interest is less about the headline amount and more about whether projects like this help stabilise earnings while dispute costs persist, Property Development remains muted and Green Industry Transformation is still scaling up.
NCC Earnings And Revenue Implied By Consensus
NCC's narrative projects SEK 44.0 billion revenue and SEK 1.6 billion earnings by 2029. This requires revenue to decline by 6.6% per year and earnings to increase by about SEK 1.5 billion from SEK 78.0 million today.
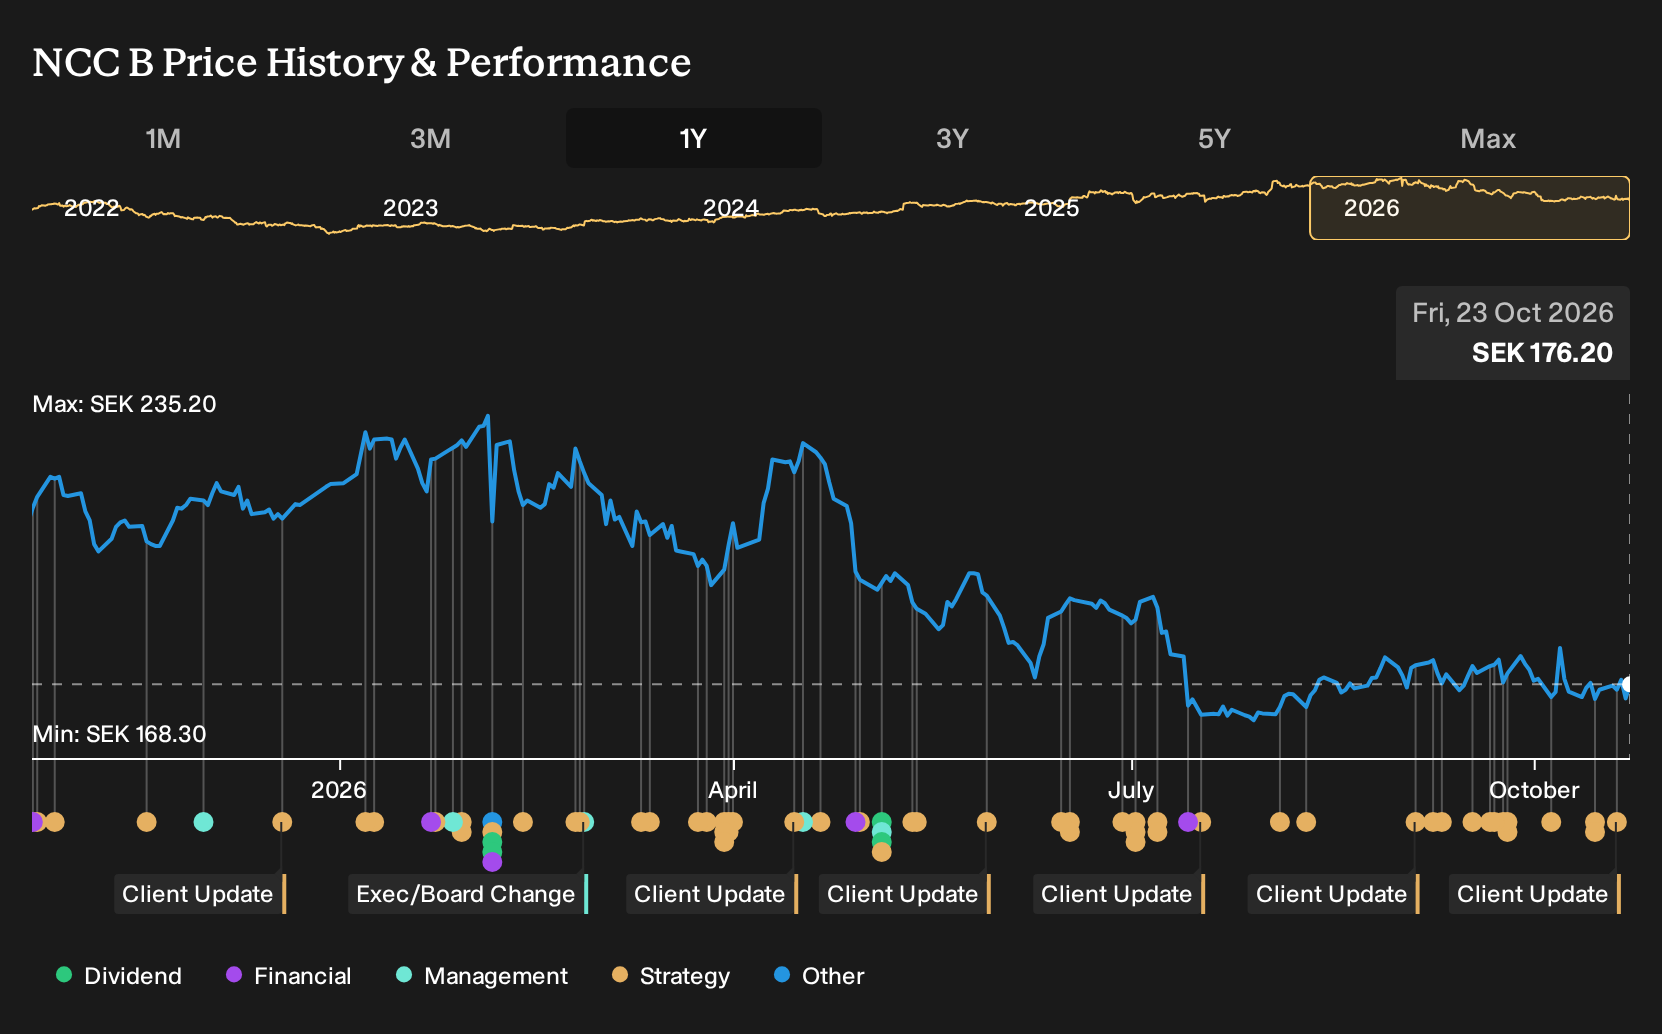
Uncover why NCC's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts already framed NCC as a future higher margin contractor, with revenue around SEK 46.5b and earnings near SEK 1.5b by 2029. You can now ask whether wins like the Öland Bridge and Helsinki school contracts push that upbeat story even further, or force a rethink in either direction.
Explore 2 other NCC fair value estimates, including one that suggests up to 16% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NCC research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for NCC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCC's overall financial health at a glance.
Looking For More Investment Ideas Beyond NCC?
If NCC is on your radar, it can help to compare it with other companies that match different risk, income and quality profiles. The Simply Wall St Screener gives you a way to quickly scan for stocks that fit the type of portfolio you are trying to build.
- If you care most about valuation and business quality, start with companies that combine stronger fundamentals with what looks like a discounted price by reviewing the 192 high quality undervalued stocks.
- If reliable income is a priority, focus on businesses with higher yields that still aim for resilience by checking the 226 dividend fortresses.
- If capital preservation matters more than chasing maximum upside, narrow your search to steadier operators by using the 221 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com