
Will Earnings Beat Hopes Change Roblox (RBLX) Stock Narrative
- Roblox is set to report its September 2026 quarter on 29 October, with analysts expecting a quarterly loss of $0.41 per share on revenues of $1.63b and a year over year decline in both metrics.
- Despite those projected pressures on earnings and sales, upgraded estimates and a positive Earnings ESP are highlighting investor focus on Roblox's monetization progress and user engagement rather than near term profitability.
- We will look at how Roblox's investment narrative is affected by rising earnings expectations despite forecasts for a loss and softer revenue.
Scan how Roblox's earnings story compares with other platforms focusing on engagement and monetization shifts by reviewing the hand-picked 21 high quality undiscovered gems for potential alternatives on your watchlist.
Roblox Investment Narrative Recap
To own Roblox, you need to believe its large, global user base can be converted into a healthier digital economy over time, even while the company reports losses. The near term story is still about engagement and how effectively new formats like digital goods and ads turn usage into bookings without pushing users away.
The upcoming quarter, with an expected loss and softer revenue, does not materially change that core bet. The key catalyst is still proof that monetization per user can trend higher. The biggest risk remains rising creator payouts and infrastructure spending outpacing what Roblox can earn from its community.
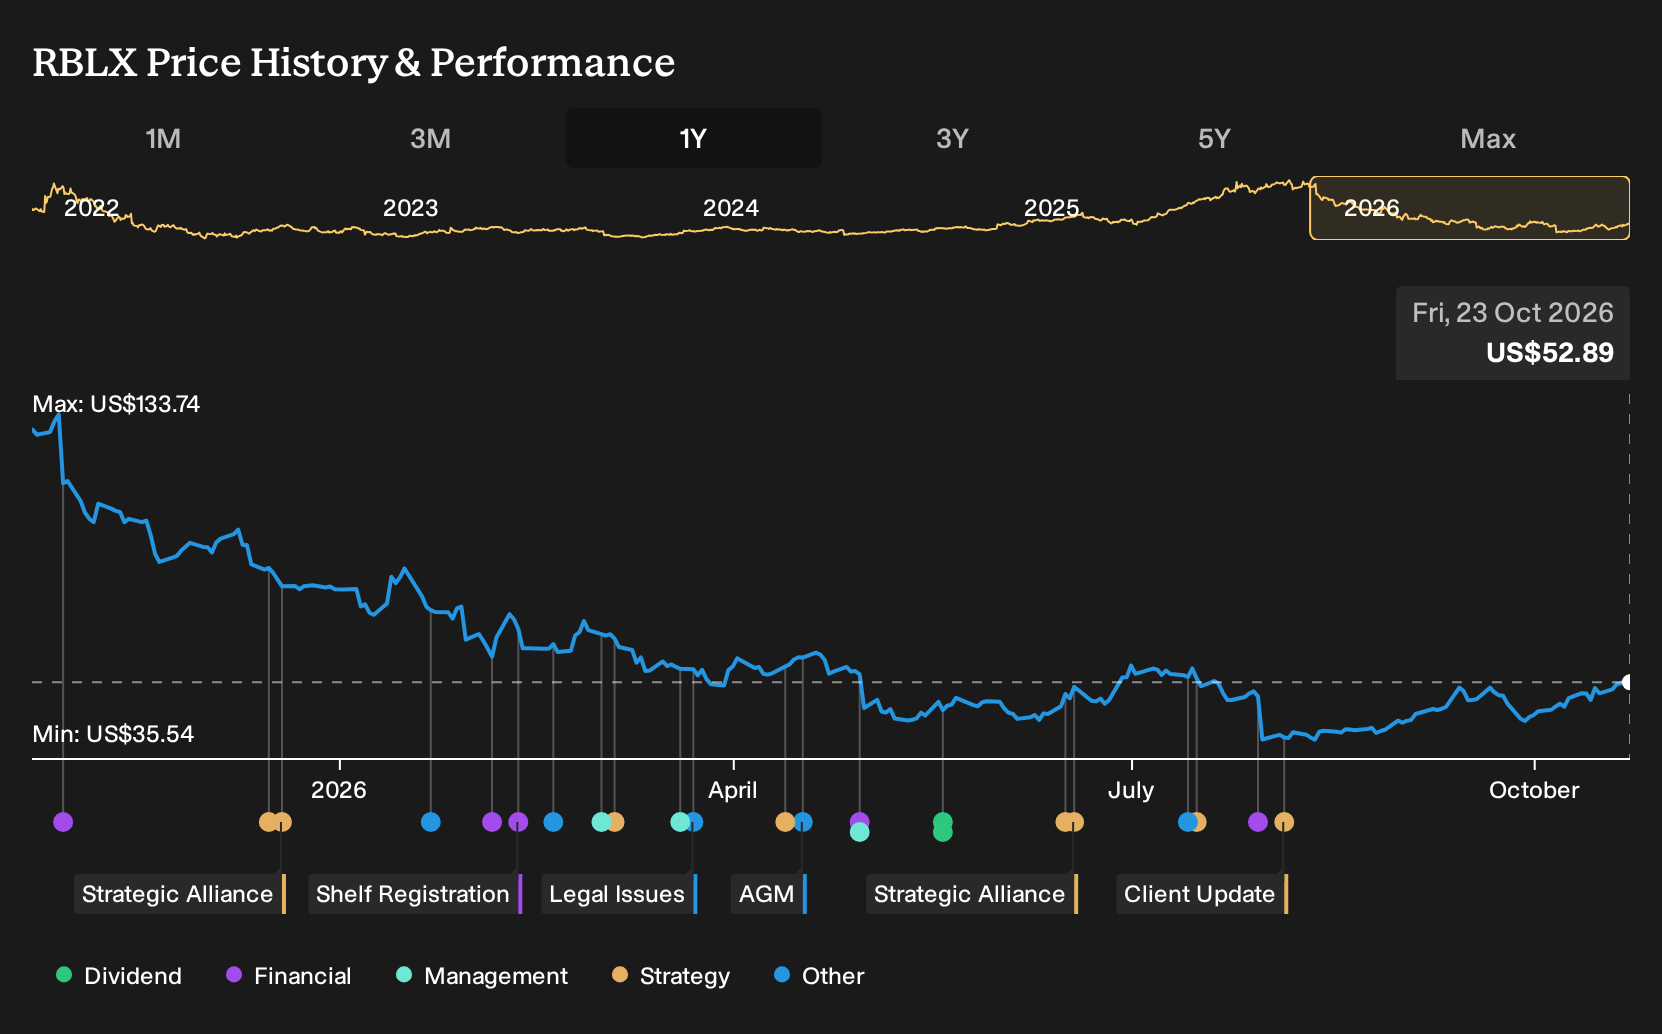
The most relevant datapoint right now is the higher earnings estimate heading into the September 2026 report, which has driven an Earnings ESP of 8.54%. That revision reflects a shift in expectations about how efficiently Roblox is monetizing activity on the platform, even in a quarter where revenue and EPS are expected to decline year over year.
If the company shows that formats like digital goods and ads can support that improving earnings profile without cutting back on safety, infrastructure, or creator payouts, it strengthens the case that current investments are productive. If not, higher DevEx and heavy capex could keep profitability under pressure while competition in immersive platforms continues to build.
Roblox's longer term setup assumes revenues can reach US$10.2b and earnings can get to US$1.2b by 2029. That path is based on analysts modeling 21.3% annual top line growth and an earnings swing of about US$2.2b, from an earnings loss of roughly US$1.0b today.
Uncover why Roblox's fair value indicates a 6% potential downside to its current price, reflecting a valuation premium that leaves little room for error.
Exploring Other Perspectives
One alternate view on Roblox puts regulatory and safety costs front and center. The most bearish analysts were penciling in revenue of about US$8.7b and earnings of roughly US$1.0b by 2029, compared with the higher consensus, and saw today’s share price as rich if safety and age verification keep dragging on bookings. Those projections were set before the latest earnings setup, so you may want to compare both stories and decide which set of assumptions feels closer to your own.
Explore 5 other Roblox fair value estimates, including one that suggests as much as 59% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Roblox research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Roblox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Roblox's overall financial health at a glance.
Looking For More Ideas Beyond Roblox?
Once you have a view on Roblox, it can help to compare that thesis with other opportunities that fit different risk, income, or balance sheet profiles. The Simply Wall St Screener lets you do that quickly by filtering the market down to a focused shortlist that aligns with what you want your portfolio to look like.
- If you care most about financial resilience, start with companies that show stronger balance sheets and fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
- If value is your priority, weigh Roblox against stocks that combine quality fundamentals with more modest pricing by reviewing the 27 high quality undervalued stocks.
- If lower volatility matters more to you than aggressive upside, narrow the field to businesses with more resilient profiles using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com