
How Investors Are Reacting To OEM International (OM:OEM B) Strong Quarterly Earnings
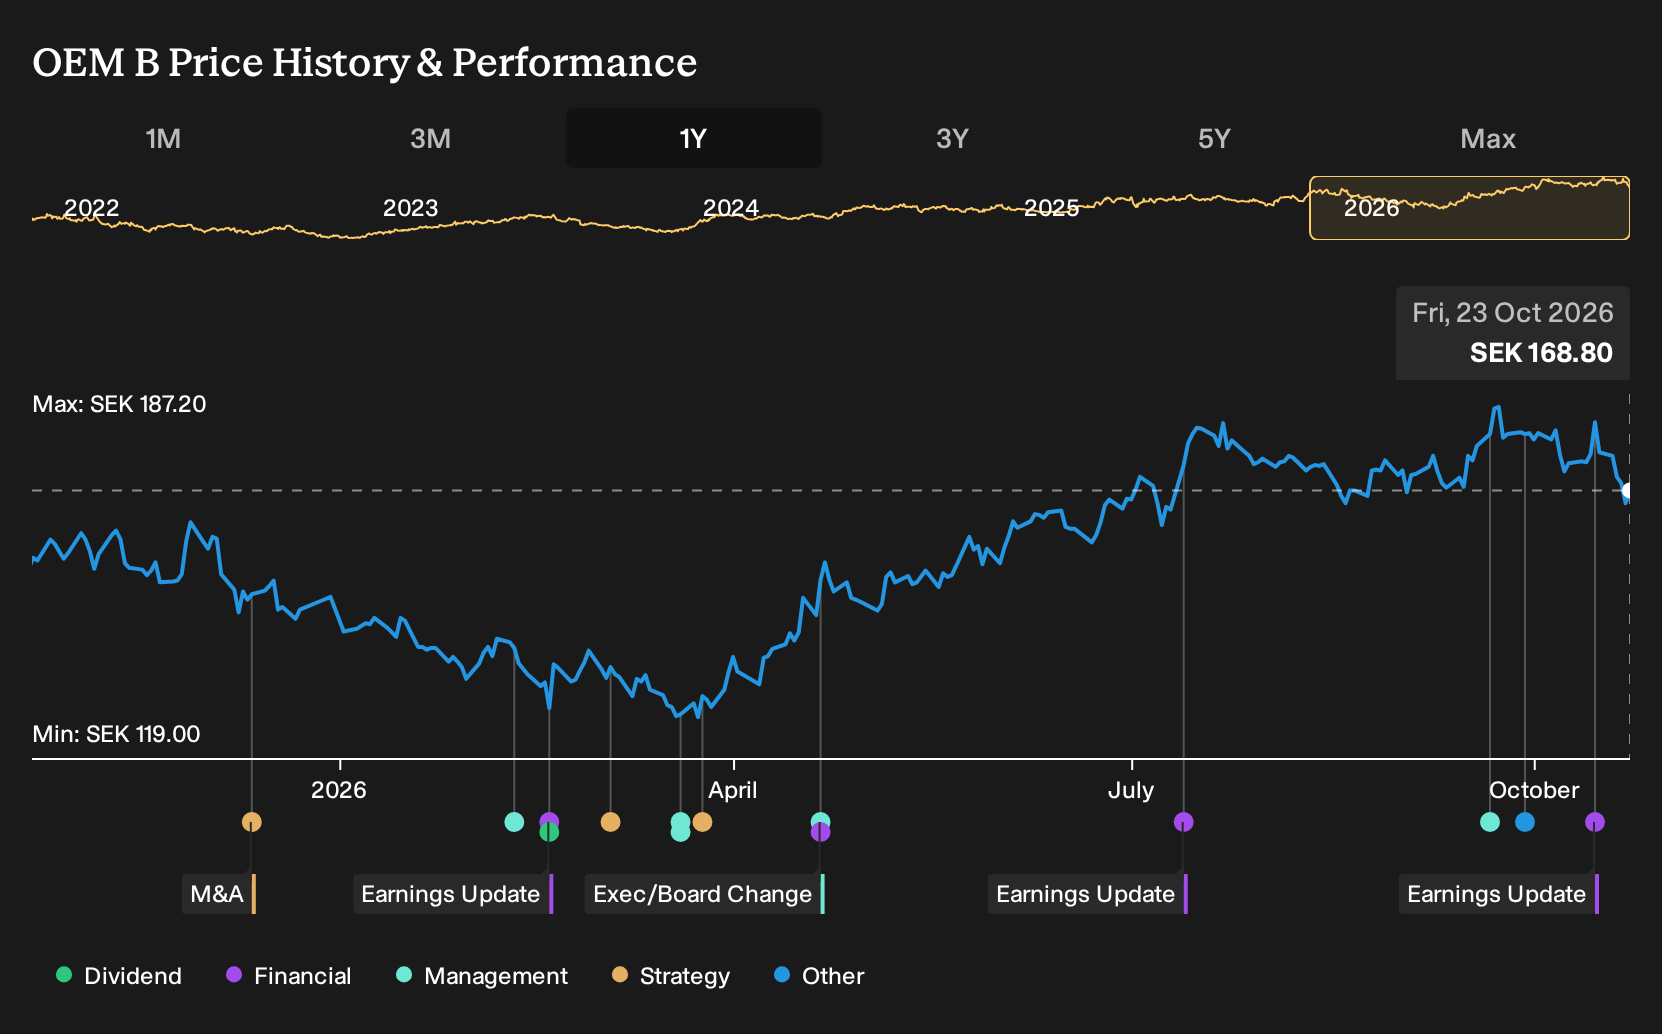
- OEM International reported third quarter 2026 sales of SEK 1,582 million and net income of SEK 201 million, with nine month figures of SEK 4,614 million in sales and SEK 562 million in net income compared with the prior year. An Extraordinary General Meeting in October 2026 elected Patrik Andersson as Chairperson alongside new Board member Simon Tillmo.
- The combination of stronger reported sales and earnings for both the quarter and year to date, together with refreshed Board leadership, highlights how OEM International is balancing operational delivery with governance changes that could influence future capital allocation and execution priorities.
- The next step is to consider how OEM International's reported quarterly earnings might influence the investment narrative that investors focus on.
What Is OEM International's Investment Narrative?
To own OEM International, you need to be comfortable with a fairly simple story. This is a distributor of industrial automation components that depends on healthy machinery and appliance production, consistent execution in its supply chain, and sensible pricing discipline in niche markets across Europe and China. The recent earnings print, with SEK 1,582 million in quarterly sales and SEK 201 million in net income, suggests the current demand backdrop is supporting that model and that the business is converting revenue to profit at a solid clip.
In the short term, the key swing factors are order momentum from manufacturing customers, the capital needed to keep inventory in step with that demand, and how OEM International balances reinvestment against shareholder returns. The appointment of Patrik Andersson as Chairperson and Simon Tillmo to the board adds a fresher governance layer that could influence capital allocation decisions, although any financial impact is likely to show up gradually rather than in the next quarter or two. At the same time, you are paying a P/E of 33.1x, which is higher than both industry and internal fair value estimates, so belief in the quality and durability of these earnings really matters.
Even so, there is a less comfortable angle to the story once you start looking closely at how quickly the boardroom and top team have been turning over...
There's only one way to know the right time to buy, sell or hold OEM International. Head to Simply Wall St's company report for the latest analysis of OEM International's Fair Value.
Exploring Other Perspectives
Simply Wall St Community members have only contributed two fair value estimates for OEM International so far, clustered tightly between SEK 181 and SEK 202 per share. That narrow band sits alongside fresh data on new leadership and the latest SEK 201 million quarterly net income, which you may judge could shift community views quite meaningfully.
Explore another OEM International fair value estimate, including one that suggests as much as 19% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your OEM International research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for OEM International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OEM International's overall financial health at a glance.
Looking For More Investment Ideas Beyond OEM International?
Once you have a view on OEM International, it can help to compare it with other opportunities that fit different goals, whether you care most about value, resilience, or balance sheet strength.
- For investors who prioritise a margin of safety, use the 192 high quality undervalued stocks to see which opportunities currently trade below their estimated worth.
- If capital preservation and steadier profiles matter more to you, filter for defensiveness first with a 221 resilient stocks with low risk scores that screens for sturdier businesses.
- When financial strength is non negotiable, start with a list of solid balance sheet and fundamentals (204 results) and focus on companies that pair healthier leverage with fundamental support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com