
Middlesex Water (MSEX) Has Investors Looking Closer, What Is Behind The Attention?
Dividend increase puts Middlesex Water in focus
Middlesex Water (MSEX) just raised its quarterly cash dividend to $0.38 per share, a 5.56% step up that extends the company’s streak to 54 consecutive years of dividend increases.
The higher payout lifts the indicated annual dividend to $1.52 per share, with the new rate scheduled for payment on December 1, 2026, to shareholders of record on November 16.
The dividend move comes after a mixed stretch for Middlesex Water’s investors. The share price is up 11.46% year to date and the 7-day share price return is 2.64%. However, the 5-year total shareholder return declined 43.75%, indicating that longer-term holders are still under water.
Compare Middlesex Water’s long dividend track record with a hand-picked 5 dividend fortresses built for investors who care about consistent income.
The dividend hike and modest share rebound put Middlesex Water at an interesting crossroads. Is this pricing a sturdier utility business, or a short burst of renewed optimism that valuation has not fully caught up to yet?
Price-to-Earnings of 22.1x: Is it justified?
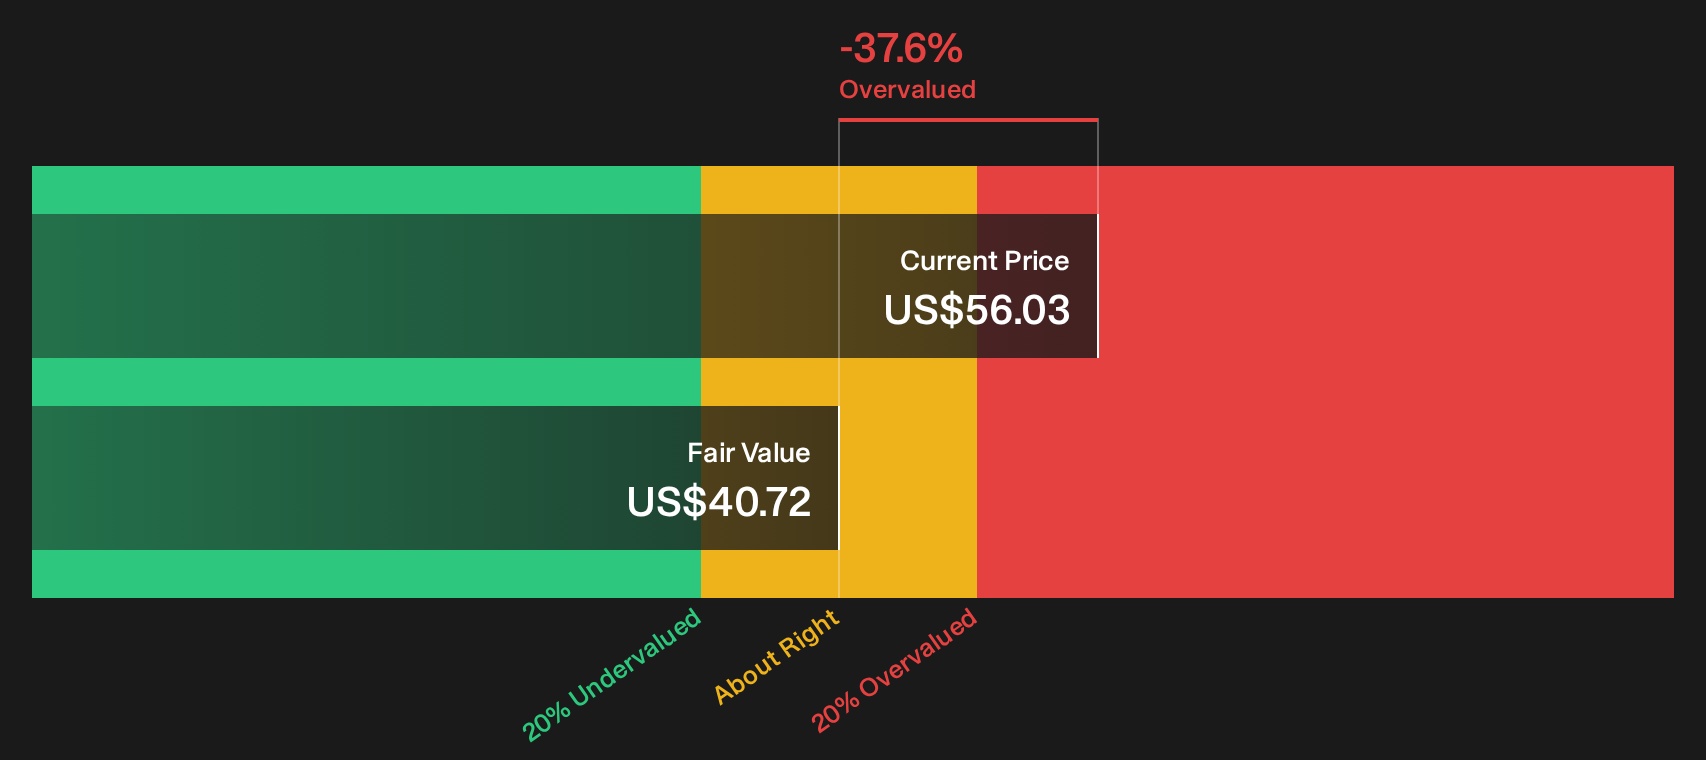
Middlesex Water now trades at a P/E of 22.1x, while the SWS DCF model values the shares at $40.72 compared with the last close of $56.03. That combination points to investors paying a premium price relative both to earnings and to an estimated future cash flow value.
The P/E ratio compares what the market is willing to pay today for each dollar of current profit. For a regulated water utility such as Middlesex Water, that yardstick often reflects how dependable investors think earnings are, and how steady they expect future profit growth to be over time.
Here, the picture is mixed. Earnings grew 10.6% over the past year and have risen 3.4% per year over the last 5 years, with current net profit margins at 23.2% compared with 22.1% a year earlier. Yet earnings are forecast to expand 9.44% per year, which is slower than the broader US market expectation of 17.2%, and the stock is described as expensive versus both a fair P/E estimate of 18x and the SWS DCF fair value of $40.72. That suggests the current multiple leaves less room for error if growth or cash generation comes in below expectations.
The premium looks even clearer when stacked against peers. The current P/E of 22.1x is higher than the peer average of 20.5x and well above the global Water Utilities group on 16x. Compared with the estimated fair P/E of 18x, the current ratio looks stretched and could be a level the market moves toward if sentiment cools or if results track forecasts rather than surprising to the upside.
Explore the SWS fair ratio for Middlesex Water.
Result: Price-to-Earnings of 22.1x (OVERVALUED)
Still, if Middlesex Water faces weaker regulated returns or higher infrastructure spending than expected, investors paying a premium P/E might reassess this recent optimism.
Find out about the key risks to this Middlesex Water narrative.
Another view on Middlesex Water valuation
The SWS DCF model adds a second lens for Middlesex Water. It pegs future cash flow value at $40.72 per share, well below the current $56.03 price, which points to the stock screening as overvalued on this metric too. If both earnings and cash flows signal a premium, where is the cushion for disappointment?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Middlesex Water for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Middlesex Water valuation and income can pull you in both directions, so move quickly to review the full picture of risks and potential upsides yourself with 2 key rewards and 2 important warning signs.
Looking for more Middlesex Water investment ideas?
If Middlesex Water has your attention, do not stop here. Use these curated stock lists to pressure test your thesis and uncover alternatives you might be overlooking.
- Scan for quality at a discount by reviewing companies in the 27 high quality undervalued stocks that pair healthy fundamentals with prices below estimated worth.
- Shield your portfolio from shocks by focusing on resilience in the 30 resilient stocks with low risk scores that highlights businesses with stronger risk profiles.
- Spot potential future leaders early through the 21 high quality undiscovered gems where lesser known stocks with solid financials sit off most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com