
Is Upcoming ARR And AI Update Altering The Investment Case For Guidewire Software (GWRE)?
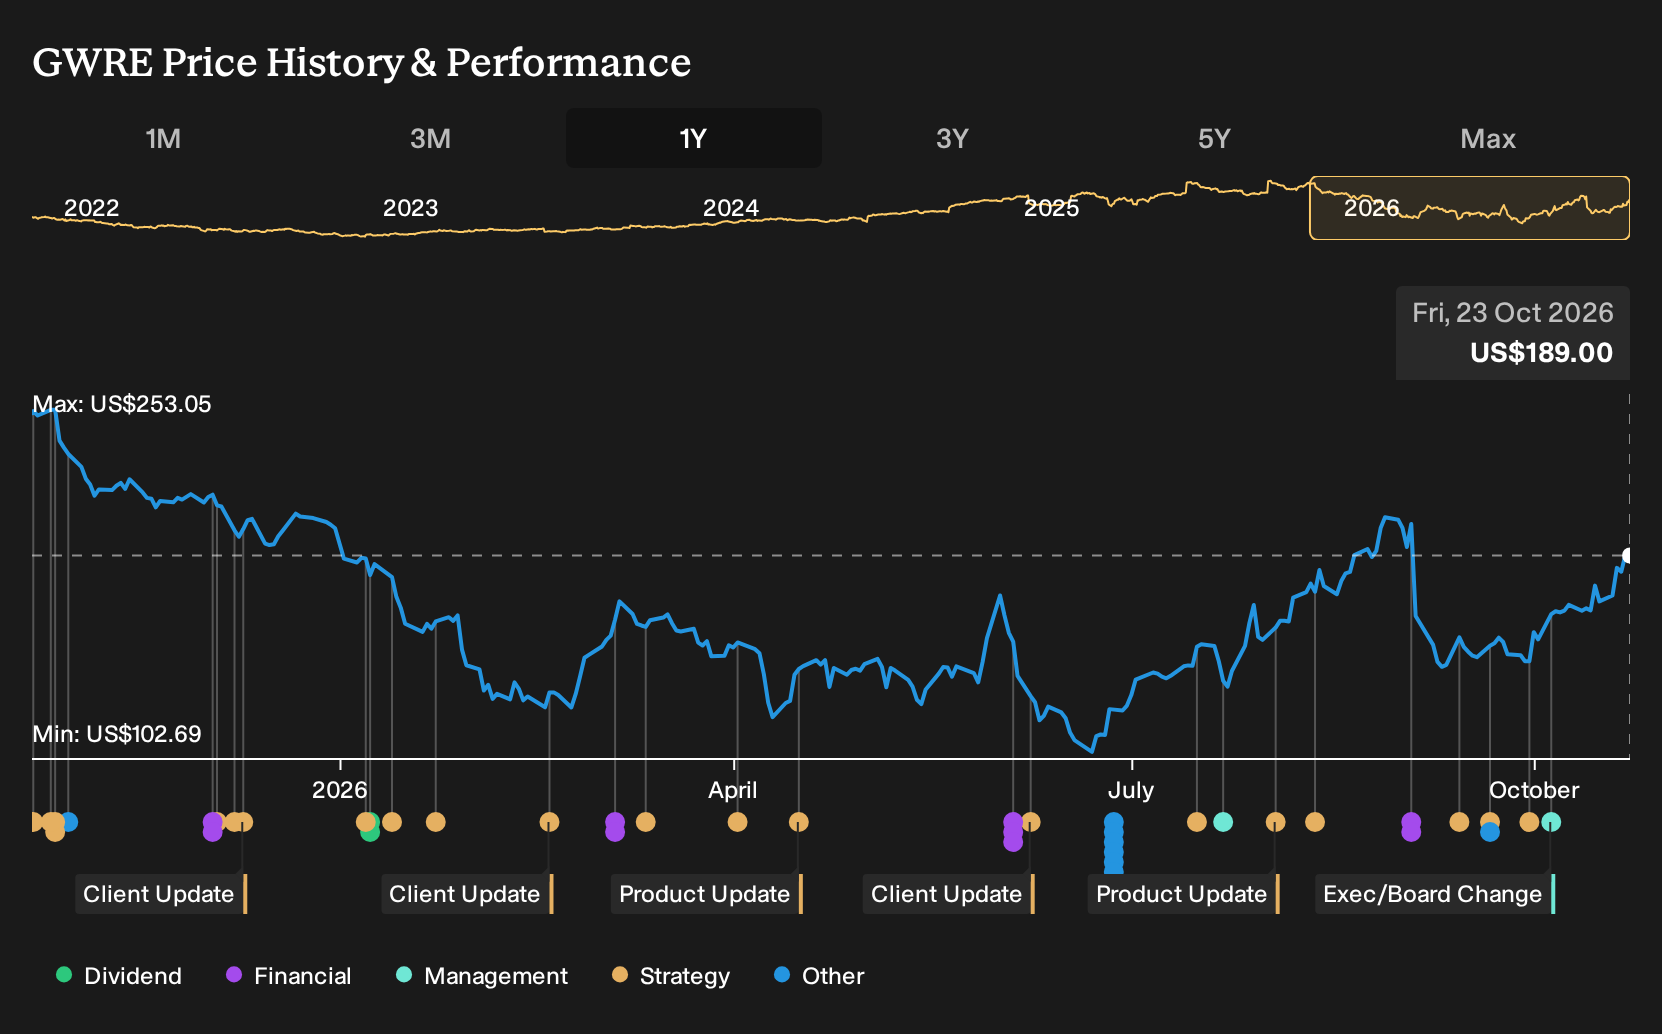
- Guidewire Software is preparing to brief investors at its late October user conference and Analyst Day on cloud ARR progress, AI initiatives, and adoption of newer tools such as PricingCenter and ProNavigator.
- The upcoming update on how insurers are using Guidewire Software’s AI capabilities within core systems and newer products could clarify demand durability and product breadth.
- Investors will soon see whether Guidewire Software’s investment narrative shifts as attention turns to the upcoming ARR and AI update.
Guidewire Software Investment Narrative Recap
To own Guidewire Software, you need to be comfortable that insurers keep shifting core systems to the cloud and leaning into embedded AI across policy, claims, and pricing. In the near term, the key question is whether management can show that cloud ARR and newer products are holding up as IT budgets move around. The upcoming update looks more like a proof point than a reset.
The biggest operational swing factor is execution on that cloud transition. Any sign that ARR momentum or the timing of fully ramped ARR is slipping would affect confidence in subscription leverage. On the risk side, the combination of a rich P/E multiple and a volatile share price means guidance quality and margin discipline matter a lot right now.
The scheduled late October user conference and Analyst Day is the key near term event. Guidewire Software plans to discuss ARR trends, the cloud roadmap, and how insurers are using AI tools such as ProNavigator and PricingCenter inside PolicyCenter and ClaimCenter. For investors, this is where the story around demand durability and product breadth either becomes clearer or remains uncertain.
RBC Capital Markets has highlighted interest in whether the fiscal 2028 ARR ambition of around US$1.7 billion still acts as a floor and how cloud customer expansion is tracking. That level of detail feeds directly into the core catalysts investors focus on, including cross selling newer modules, keeping churn low, and using AI powered tools to improve services efficiency and margins over time.
Guidewire Software’s current analyst narrative points to about US$2.3b of revenue and US$359.7 million of earnings by 2029, based on an assumed 15.7% yearly revenue growth rate and an earnings increase of roughly US$220 million from about US$139.3 million today.
Uncover why Guidewire Software's fair value indicates a 13% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Guidewire Software’s bullish analysts focus on one big swing factor. They see AI driven cloud contracts turning into a much steeper earnings ramp, with prior top end forecasts around US$2.5b of revenue and US$434.5 million of earnings by 2029. You can read that as a far more optimistic story. It may shift once the upcoming ARR and AI updates land, so treat it as one of several viewpoints to compare.
Explore 3 other Guidewire Software fair value estimates, including one that suggests there could be as much as 35% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Guidewire Software research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Guidewire Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Guidewire Software's overall financial health at a glance.
Looking for more ideas beyond Guidewire Software?
If the Guidewire Software story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you zero in on different types of opportunities that fit your own risk and return preferences.
- For investors who care most about resilient balance sheets and steady fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results) that filters for financial strength and staying power.
- If you are hunting for potential mispricings where quality and valuation intersect, cast a wider net with a focused 27 high quality undervalued stocks built to surface candidates that may warrant a closer look.
- Income focused readers who want yield backed by underlying resilience can scan a targeted 5 dividend fortresses that concentrates on higher payout opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com