
Is Red Rock Resorts (RRR) Undervalued As Its Share Price Slide Sharpens Focus On Fair Value?
Red Rock Resorts (RRR) has caught investor attention after recent trading left the stock down about 2% over the past month and roughly 22% over the past 3 months, sharpening focus on fundamentals.
Despite the recent slide, Red Rock Resorts shares at US$49.61 still reflect a longer track record where the 3 year total shareholder return is up 41.65%, even as the year to date share price return has declined 21.22% and nearer term momentum has faded.
Spot opportunities beyond Red Rock Resorts by scanning our hand picked 27 high quality undervalued stocks with solid cash flows and balance sheets that may offer stronger risk reward trade offs than this single casino operator.
Red Rock Resorts has given holders a strong 3 year run, yet the recent slide from earlier highs hints that much of that gain may already be in the rearview mirror. How much upside does the current valuation still suggest?
Most Popular Narrative: 32% Undervalued
Against the last close at $49.61, the most followed narrative on Red Rock Resorts points to a fair value around $73.39, placing the current slide in a different light and tying the share price closely to long dated cash flow expectations built on Las Vegas locals demand and a heavy capex slate.
The current valuation implies the share price already reflects record Las Vegas revenue and adjusted EBITDA in 2025, the large capex pipeline through at least 2027, and the view that Red Rock Resorts is undervalued relative to its cash flow profile and capital returns.
See why 2 investors see Red Rock Resorts as 32% undervalued.
Result: Fair Value of $73.39 (UNDERVALUED)
Still, heavy renovation and construction spending, together with net debt of about US$3.5b and net leverage above 4x, could pressure Red Rock Resorts if project returns disappoint.
Find out about the key risks to this Red Rock Resorts narrative.
Another View On Red Rock Resorts Using Earnings Multiples
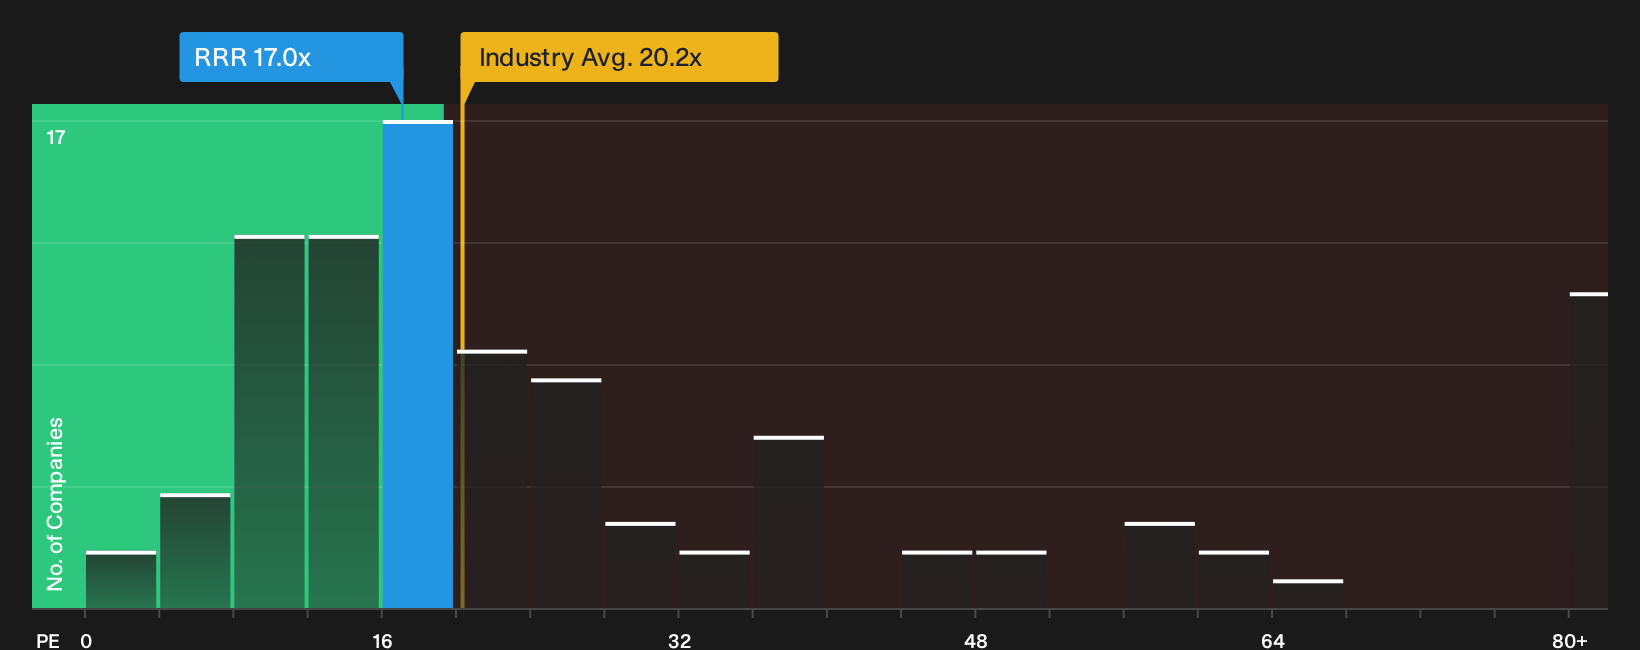
That 32% undervalued story leans heavily on long term cash flows. A simpler lens, the current P/E, tells something different. Red Rock Resorts trades on roughly 17x earnings against a peer average of 14.1x, while the fair ratio sits higher at 20.6x.
This combination of a richer tag than similar hospitality stocks, yet below the fair ratio level the market could move toward, leaves you weighing whether the gap signals potential upside or a margin of error if the Las Vegas locals thesis falls short.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Red Rock Resorts often create the most interesting setups, so move fast on your homework and weigh both sides using the 3 key rewards and 3 important warning signs.
Looking for more ideas beyond Red Rock Resorts?
If Red Rock Resorts has you thinking harder about valuation and risk, do not stop at one ticker. Broaden your watchlist with focused stock ideas built from clear rules.
- Target potential mispriced opportunities by scanning our hand picked 27 high quality undervalued stocks that pair quality fundamentals with discounted market prices.
- Secure more predictable income streams by reviewing a curated group of yield focused companies in the 5 dividend fortresses.
- Shield your portfolio from balance sheet stress by filtering for resilient businesses in the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com