
Is New GDIT President Altering The Investment Case For General Dynamics Stock?
- General Dynamics recently appointed Amy Johnson as president of its GDIT unit, effective 3 November 2026, after nearly three decades in senior engineering and leadership roles across cybersecurity, defense electronics, space and intelligence systems.
- Her promotion from leading Space, Cyber and Intelligence at General Dynamics Mission Systems puts a seasoned technical operator in charge of a business that depends on complex, long term technology contracts with federal and defense customers.
- We will now look at how General Dynamics' investment narrative could be influenced by Amy Johnson leading GDIT's technology operations.
General Dynamics Investment Narrative Recap
To own General Dynamics, you need to believe the business can turn its US$136.5b backlog and US$186.9b in total estimated contract value into consistent execution on long cycle defense, aerospace and technology programs. In the near term, an important swing factor is how effectively operations scale on submarines, Gulfstream jets, munitions and federal IT work without eroding margins.
Amy Johnson stepping in at GDIT looks more like continuity than disruption for that story. The bigger immediate risk still sits with execution issues such as the Mesquite artillery plant and the potential for legacy platforms or customer preferences to shift, which could demand heavier R&D spend and pressure profitability.
The appointment of Johnson to lead GDIT matters most when you connect it to Technologies segment catalysts already in motion. GDIT recently secured the up to US$1.3b ENOCS contract to modernize and defend Army National Guard networks, a long dated technology program that leans heavily on cybersecurity and network expertise.
That award puts execution in Johnson’s wheelhouse, given her 27 years across cyber, space and intelligence systems at General Dynamics. For you as a shareholder, the key question is whether GDIT can deliver on complex IT modernization, AI and cyber contracts like ENOCS while avoiding cost overruns and protecting the higher value software and services margins analysts are watching.
What The Analyst Forecasts Assume For General Dynamics
General Dynamics' narrative projects US$62.5b revenue and US$5.7b earnings by 2029. That profile lines up with analysts baking in 4.4% yearly revenue growth and an earnings increase of about US$1.2b from US$4.5b today.
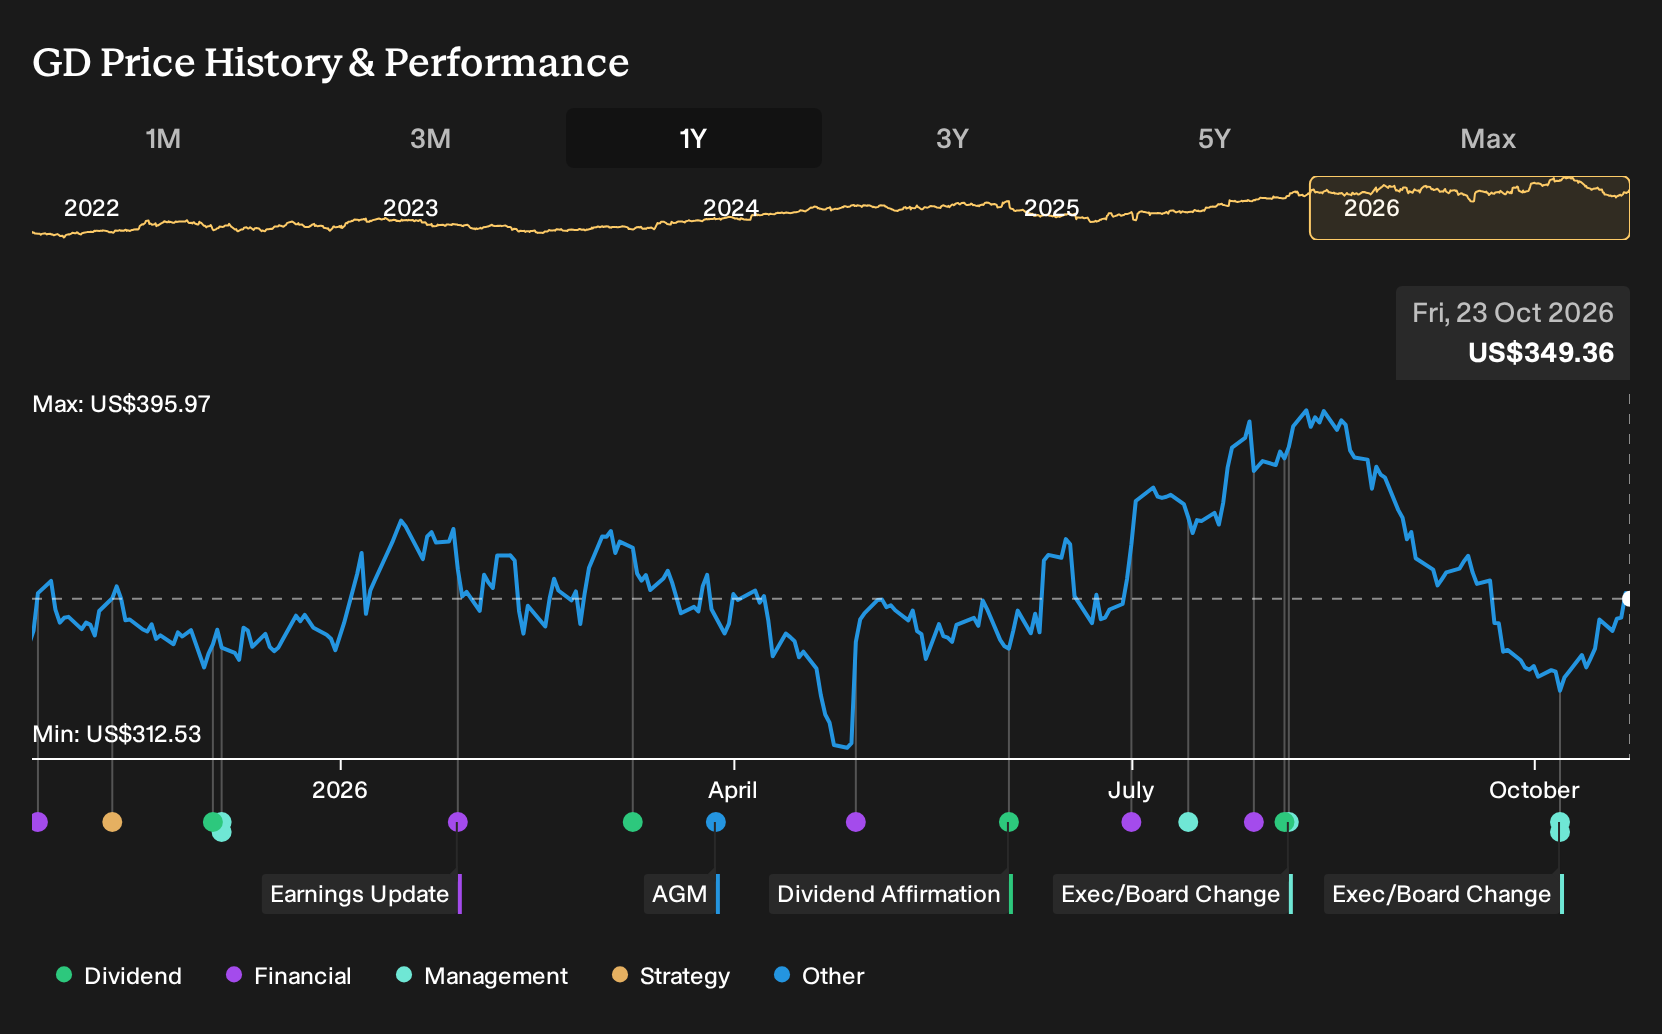
Uncover how General Dynamics' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community cluster between about US$371 and US$437 per share, so retail opinions on General Dynamics already span a wide valuation band. Use that spread as a prompt to stress test your own view against execution risks such as Mesquite or long term contract catalysts in submarines, Gulfstream and GDIT.
Explore 4 other General Dynamics fair value estimates, including one that suggests there could be as much as 25% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your General Dynamics research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for General Dynamics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate General Dynamics' overall financial health at a glance.
Looking For More Ideas Beyond General Dynamics?
Once you have a clear view on General Dynamics, it can help to benchmark that thesis against other businesses with different balance sheets, income profiles and risk levels. The Simply Wall St Screener is built for exactly that kind of comparison across sectors and market caps.
- If you want companies that aim for resilience first, filter for steadier profiles through our 30 resilient stocks with low risk scores and compare how their risk checks stack up against General Dynamics.
- For investors focused on income today rather than just future growth, scan higher yielding opportunities through our 5 dividend fortresses and see which payouts look more attractive relative to your view on General Dynamics.
- When you are hunting for quality that the wider market might be overlooking, source fresh watchlist ideas using our 21 high quality undiscovered gems and pressure test them against the General Dynamics narrative you have built.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com