
Cushman & Wakefield (CWK) Hires CBRE Team Following Chicago Push But Is The Stock Cheap
Cushman & Wakefield (CWK) has expanded its Chicago suburban office platform by hiring veteran producers Peter Adamo and Adam Lawler as Executive Managing Directors and bringing in Madeline Leland as Transaction Manager from CBRE.
Cushman & Wakefield’s recent hiring push and its October redemption of the remaining US$150 million of 6.75% Senior Secured Notes come against a mixed market backdrop. The share price is at US$11.83 after a 7 day gain of 4.69%, but a year to date decline of 25.32% and a 1 year total shareholder return down 30.74%. The 3 year total shareholder return remains positive at 77.10%, suggesting earlier momentum has cooled even as management actions and balance sheet moves continue to reshape the risk profile.
Compare Cushman & Wakefield’s leadership reshuffle and balance sheet moves with a hand picked list of solid balance sheet and fundamentals (25 results) that may offer similar resilience with different risk profiles.
For Cushman & Wakefield, a cleaner balance sheet and fresh senior talent arrive just as the share price has pulled back sharply. Are investors reassessing the business, or has sentiment moved further than the fundamentals justify?
Most Popular Narrative: 30% Undervalued
Cushman & Wakefield’s most followed valuation story puts fair value at $17, well above the recent $11.83 share price. This makes the gap between price and expectations hard to ignore for anyone tracking the stock.
High client retention and recurring services are now complemented by rapid growth in higher value offerings such as data center work. Revenue in this area was up 83% year to date by Q2 2026 and a quarter of the integrated facilities management pipeline is data center related, which together point to a mix shift that can support recurring revenue and cash flow.
See why 2 investors see Cushman & Wakefield as 30% undervalued.
Result: Fair Value of $17 (UNDERVALUED)
Still, Cushman & Wakefield’s reliance on cyclical leasing and capital markets fees, along with ongoing legal exposure at Pinnacle, could quickly challenge that 30% undervalued narrative.
Find out about the key risks to this Cushman & Wakefield narrative.
Another View: Cushman & Wakefield On Earnings Multiples
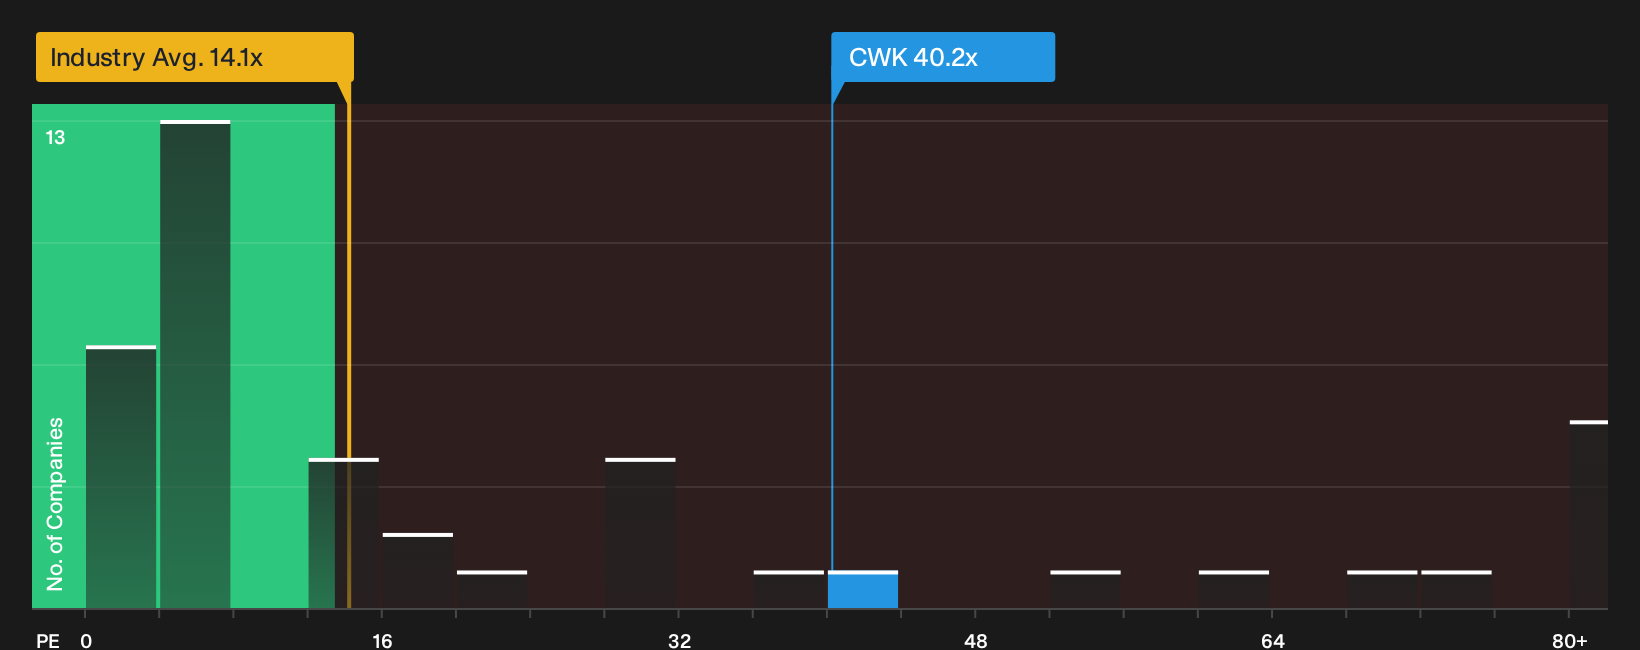
There is a very different message coming from Cushman & Wakefield’s valuation on earnings. The stock trades on a P/E of 40.2x, while the fair ratio sits at 30.8x and the wider US Real Estate group is closer to 14.4x. That combination suggests investors are already paying a steep price for future profit improvement, even as the DCF narrative points to upside. Which picture do you trust more when expectations are this split?
Before leaning on any single metric, it can help to see how that P/E premium compares across peers and how today’s ratio might move toward the fair ratio over time. This is unpacked in more depth in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these around Cushman & Wakefield do not wait for investors to decide. Take a closer look now and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cushman & Wakefield?
Do not stop with Cushman & Wakefield. Use this moment to scan fresh opportunities so you keep your watchlist packed with ideas that genuinely earn a closer look.
- Target potential upside with companies that look attractively priced on quality and fundamentals through the 27 high quality undervalued stocks.
- Strengthen the income side of your portfolio by reviewing the 5 dividend fortresses that focus on higher yielding and more robust payout profiles.
- Dial down portfolio stress and concentrate on durability by filtering for the 30 resilient stocks with low risk scores that score well on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com