
Learn Why The Bull Case For Wabtec Stock Could Change Following Earnings Beat
- Westinghouse Air Brake Technologies reported Q3 2026 results with US$3.12b in revenue, US$409m in net income, and basic EPS from continuing operations of US$2.43.
- The company paired this profit performance with continued 2026 revenue guidance of US$12.3b to US$12.6b and margin support from Freight, Transit, and fast growing Digital Intelligence operations.
- We will now look at how Westinghouse Air Brake Technologies' investment narrative is affected by its earnings beat and wider operating margins.
Scan how Westinghouse Air Brake Technologies compares with other rail and infrastructure peers that also show solid balance sheets and fundamentals using this curated list of solid balance sheet and fundamentals (25 results).
Westinghouse Air Brake Technologies Investment Narrative Recap
An investor in Westinghouse Air Brake Technologies needs to believe the rail equipment cycle, long term modernization programs and software driven services can keep feeding its multiyear backlog and margin profile. The latest quarter did that no harm. Q3 2026 showed wider operating margins, strong Digital Intelligence revenue and a backlog above US$31b that supports near term revenue visibility.
The most important near term catalyst is management execution on higher margin software and services while integrating past acquisitions. The key risk still sits in tariffs, input costs and a weaker services year from fewer modernizations. The continued 2026 revenue guidance and margin expansion make that risk feel better contained, but not removed.
The clearest supporting announcement for this story is the reaffirmed 2026 outlook. Management kept full year revenue guidance at US$12.3b to US$12.6b and raised adjusted EPS expectations after the Q3 earnings beat. That ties the short term narrative to operational delivery rather than financial engineering.
For you, this guidance update links straight to the main catalysts. A large, multi year order book, higher margin Digital Intelligence growth and integration benefits from roughly US$4.5b of deals since 2020 all need to flow reliably into earnings. Any setback around tariffs, debt costs or slower services revenue would test how durable that guidance really is.
Westinghouse Air Brake Technologies' narrative connects analyst expectations for about US$14.8b in revenue and US$2.4b in earnings by 2029 with a 7.3% yearly revenue growth outlook and an earnings increase of roughly US$1.1b from US$1.3b today.
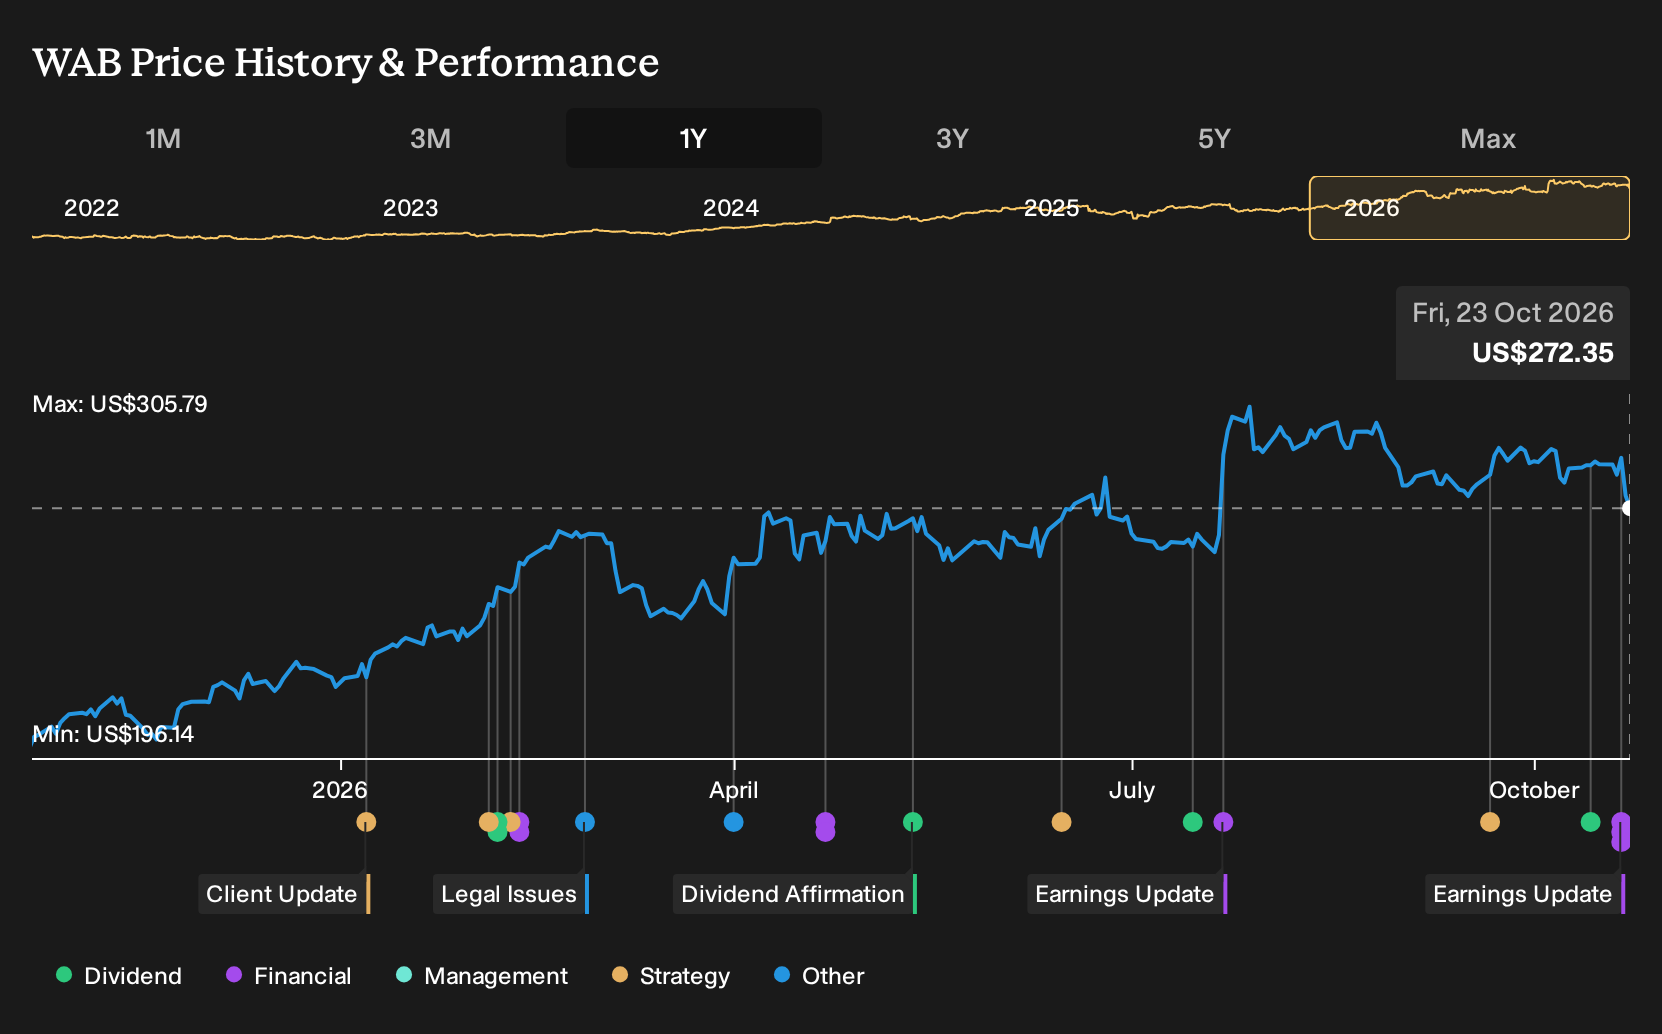
Uncover why Westinghouse Air Brake Technologies' fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$277 and US$330, which leaves plenty of room for disagreement around Westinghouse Air Brake Technologies after the Q3 beat and reaffirmed 2026 guidance. With tariff pressure, insider selling and the fresh universal shelf also in focus, investors may be considering genuinely different playbooks. Explore those viewpoints before deciding how the story fits your own expectations.
Explore another Westinghouse Air Brake Technologies fair value estimate, including one that suggests as much as 21% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Westinghouse Air Brake Technologies research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Westinghouse Air Brake Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westinghouse Air Brake Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Westinghouse Air Brake Technologies?
After weighing up Westinghouse Air Brake Technologies, it can help to line it up against a wider watchlist so you are not relying on a single story. The Simply Wall St Screener makes that easier by letting you filter for the traits you care about most, whether that is quality, balance sheet strength, income potential, or lower risk profiles.
- If you value capital preservation first, start with a basket of companies that our models flag as sturdier options through 30 resilient stocks with low risk scores.
- If income matters more to you than rapid growth, scan for higher yielding businesses that still clear basic quality hurdles with 5 dividend fortresses.
- If you want something a bit less crowded, check out financially solid stocks that have not yet attracted broad attention using 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com