
DRDGOLD (DRD) Could Be 44% Over Fair Value After Revenue Growth And New Guidance
What DRDGOLD’s latest quarter tells investors
DRDGOLD (DRD) reported quarterly revenue of ZAR 2,950.6 million and gold sales of 1,324 kg for the period to 30 September 2026, along with production guidance of 160,000 to 170,000 ounces for the 2027 financial year.
Against that operational backdrop, DRDGOLD’s share price has softened in the short term, with a 1 day move down of 1.56% and a 30 day share price return down 5.96% at a recent level of US$23.97. However, the 90 day share price return is up 14.47% and the 3 year total shareholder return is up 189.89%, which suggests recent weakness contrasts with a much stronger multi year record as investors weigh the latest production update and new guidance against prior gains.
Scan DRDGOLD alongside a curated group of peers by checking the hand picked 35 elite gold producer stocks that may also be reacting to fresh production updates and guidance.
DRDGOLD’s shares have cooled after a strong multi year run, even as the latest quarter showed higher revenue and production. Is most of the upside already in the price, or does the current tag still leave room?
Preferred P/E of 8.1x: Is it justified for DRDGOLD?
On simple earnings math, DRDGOLD looks inexpensive. The shares last closed at $23.97 while the stock trades on a P/E of 8.1x, which is materially lower than both the wider US market and its metals and mining peers.
The P/E ratio compares the price investors pay for each dollar of profit. For a producer like DRDGOLD, where earnings are a key output of metal prices, grades and costs, this measure gives a direct read on how the market is pricing today’s profitability against what has already been reported.
Here, the gap is wide. DRDGOLD’s P/E of 8.1x sits well below the US market average of 18.6x and also below the US metals and mining industry at 16.8x. That contrast suggests investors are paying a much lower multiple of DRDGOLD’s earnings than they are for both the broader market and sector peers.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 8.1x (UNDERVALUED)
Still, DRDGOLD faces real risks if tailings retreatment volumes disappoint or if gold prices soften, which could pressure earnings and challenge that low P/E story.
Find out about the key risks to this DRDGOLD narrative.
Another view on DRDGOLD’s valuation
A different lens on DRDGOLD points to a less generous picture. The SWS DCF model puts future cash flow value at $16.67 per share, while the stock trades at $23.97. That implies the shares are priced above this estimate. Is the low 8.1x P/E giving a false sense of comfort?
Look into how the SWS DCF model arrives at its fair value.
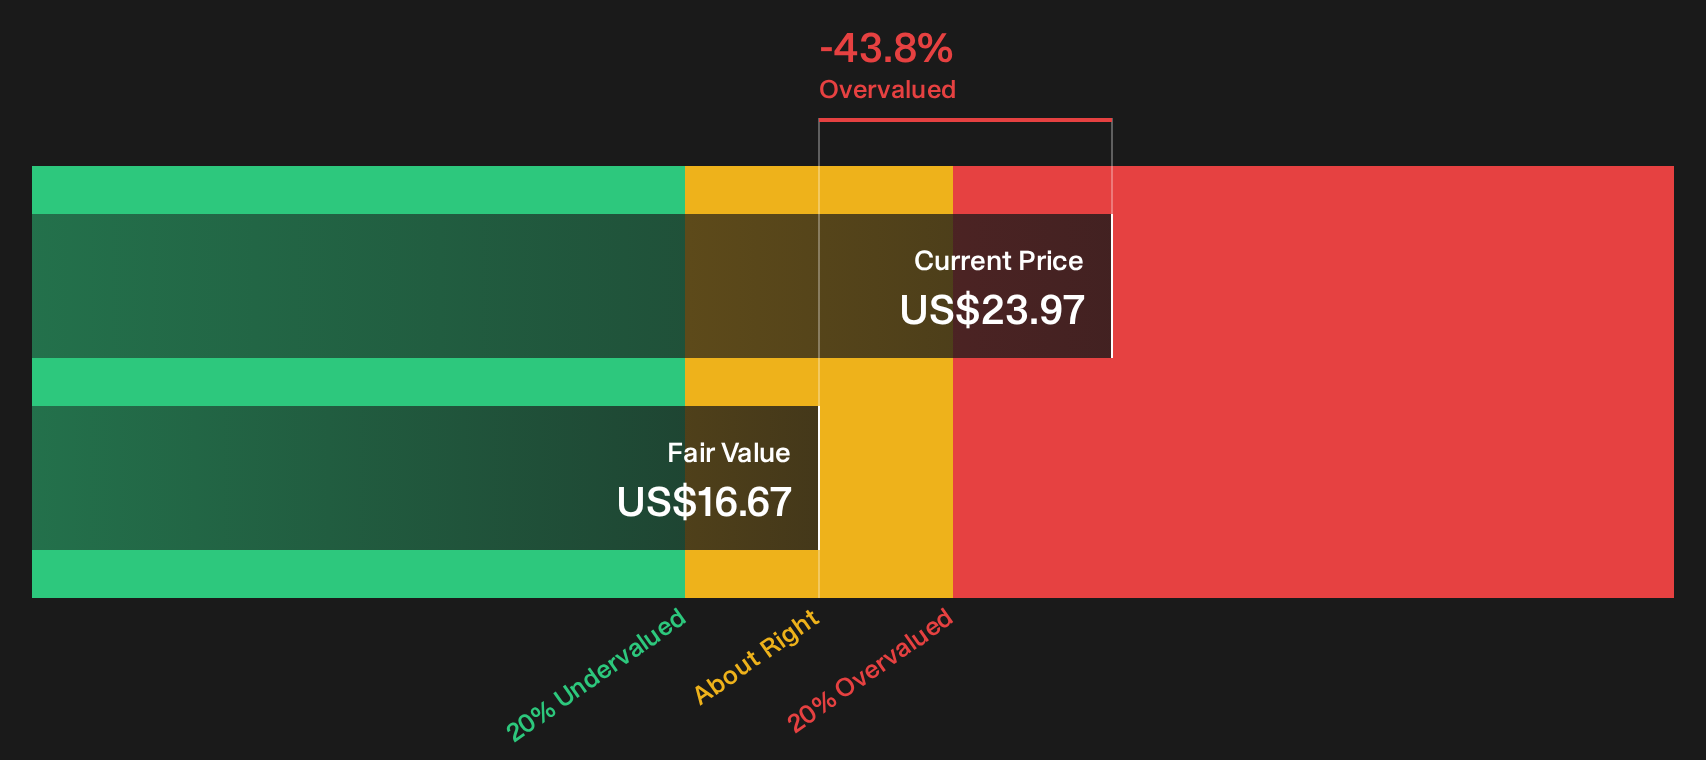
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DRDGOLD for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like these around DRDGOLD can split opinion, so move quickly, study the latest numbers in context, then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond DRDGOLD?
Once you have a handle on DRDGOLD, do not stop there. A few minutes with a focused screener can surface opportunities you would otherwise miss.
- Target resilience by scanning a 30 resilient stocks with low risk scores that highlights businesses with lower risk scores for investors who want fewer surprises in their portfolio.
- Hunt for mispriced quality through a 27 high quality undervalued stocks that filters for strong cash generation combined with balance sheets that can support future plans.
- Unearth lesser known opportunities using a 21 high quality undiscovered gems that focuses on under the radar companies with fundamentals that may not yet be widely appreciated.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com