
FirstEnergy (FE) Heads Into Q3 Earnings With Its Premium Valuation Under Review
Why FirstEnergy’s Upcoming Earnings Matter Now
FirstEnergy (FE) heads into its Q3 2026 earnings release with two forces pulling in opposite directions. Data center and industrial demand support the story, while higher operating and storm costs keep investors cautious.
FirstEnergy’s share price has moved to US$46.15 with a 30 day share price return of 5.73%, helping to offset a 90 day share price decline of 7.55%. The 3 year total shareholder return of 48.80% points to stronger longer run momentum than the last quarter suggests.
Compare FirstEnergy’s setup heading into Q3 with a curated 42 power grid technology and infrastructure stocks that are also exposed to data center demand and grid spending themes.
The share price rebound to US$46.15 reflects fresh optimism in FirstEnergy’s data center and grid story. After that move and a premium tag to peers, does the risk reward still skew toward buyers?
Most Popular Narrative: 10% Undervalued
FirstEnergy’s most followed valuation narrative points to a fair value of about $51.42, compared with the recent close at $46.15. That gap sets up the earnings release as a key test of whether the grid and data center story still supports that higher valuation anchor.
Large scale infrastructure modernization and grid hardening plans are being extended through a US$36b capital program from 2026 to 2030. This includes a reaffirmed US$6b 2026 plan and double digit transmission rate base growth, which together can support higher allowed returns on equity, better reliability metrics, and stronger net margins.
See why 16 investors see FirstEnergy as 10% undervalued.
Result: Fair Value of $51.42 (UNDERVALUED)
Still, the bullish FirstEnergy story collides with two pressure points: tight political scrutiny on customer bills and heavy grid spending that can strain cash flow if funding costs stay high.
Find out about the key risks to this FirstEnergy narrative.
Another View: FirstEnergy Through A P/E Lens
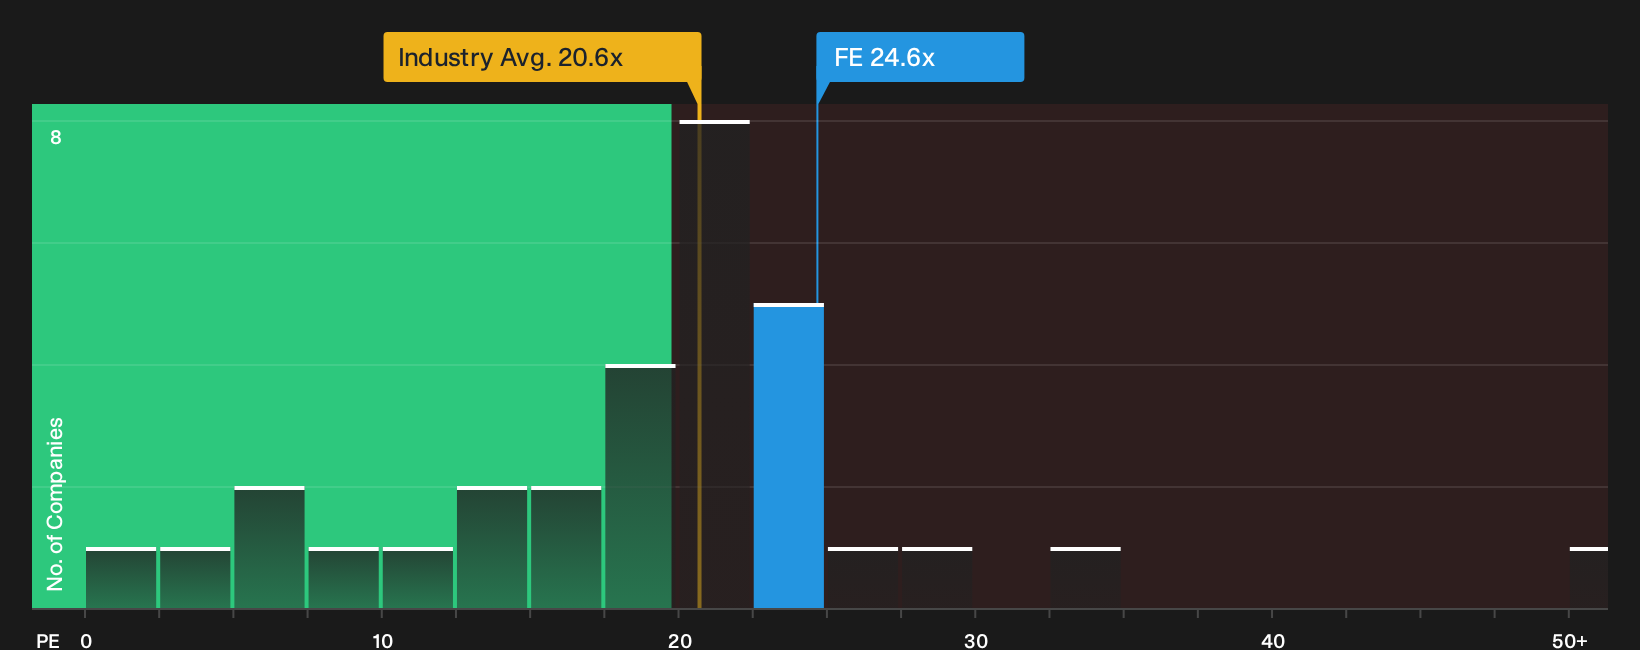
That 10% undervalued fair value of $51.42 sits awkwardly beside how FirstEnergy is actually priced on earnings. The stock trades on a P/E of 24.6x versus about 13.4x for peers and a fair ratio estimate of 21.5x, which points to a richer tag and less room for disappointment if growth or regulation soften.
Put differently, investors are paying a higher multiple than both the industry and the fair ratio suggest the market could move toward, which raises the question: Is that premium a reasonable price for FirstEnergy’s grid and data center narrative, or is it stretching what the fundamentals support?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around FirstEnergy feels familiar, consider acting while sentiment remains divided and review the key signals yourself. Start by weighing the 1 key reward and 2 important warning signs.
Looking for more ideas beyond FirstEnergy?
Do not stop at FirstEnergy. Use the screener to pressure test your thesis, compare other options, and avoid leaving better risk reward trades on the table.
- Target steadier compounding by scanning for companies with consistent fundamentals and a strong financial base through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality where business strength and valuation line up by reviewing the 21 high quality undiscovered gems.
- Stack your watchlist with candidates that balance upside potential with fewer red flags by checking the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com