
Is Installed Building Products (IBP) A Bargain On Its Debt Funding Move?
Debt move reshapes Installed Building Products’ funding mix
Installed Building Products (IBP) plans to increase its roughly $500 million Term Loan B by $250 million, a material financing step that changes its leverage profile and expands available capital for corporate uses.
Installed Building Products’ debt add on lands at a time when momentum in the share price has cooled, with the stock at US$199.12 after a 7 day share price return of 7.2% but a year to date share price decline of 25.6%, while the 3 year total shareholder return of 91.1% still points to a much stronger longer term record than the recent 1 year total shareholder return, which is down 24.8%.
Compare Installed Building Products’ funding shift with other construction and building suppliers by screening for list of solid balance sheet and fundamentals (25 results) that may handle leverage and cash flows very differently.
Installed Building Products has a long operating history and a wide set of services, and is now leaning harder on debt just as the share price has cooled. Are investors paying a fair price for that mix today?
Most Popular Narrative: 9.5% Undervalued
Installed Building Products is framed by the most followed narrative as worth $220.00 a share, compared with the recent $199.12 close. This puts the focus on whether its mix of growth projects and higher leverage can justify that gap.
Growing heavy commercial installation work, which recently posted around 16% same branch sales growth with record monthly revenue and rising backlog, could continue to shift Installed Building Products’ mix toward projects that support steadier revenue and operating margin contribution.
See why 5 investors see Installed Building Products as 9% undervalued.
Result: Fair Value of $220.00 (UNDERVALUED)
Still, Installed Building Products faces pressure if residential new single family weakness persists and if persistent cost inflation outpaces local pricing, squeezing margins and testing this upside case.
Find out about the key risks to this Installed Building Products narrative.
Another View: Installed Building Products Through A P/E Lens
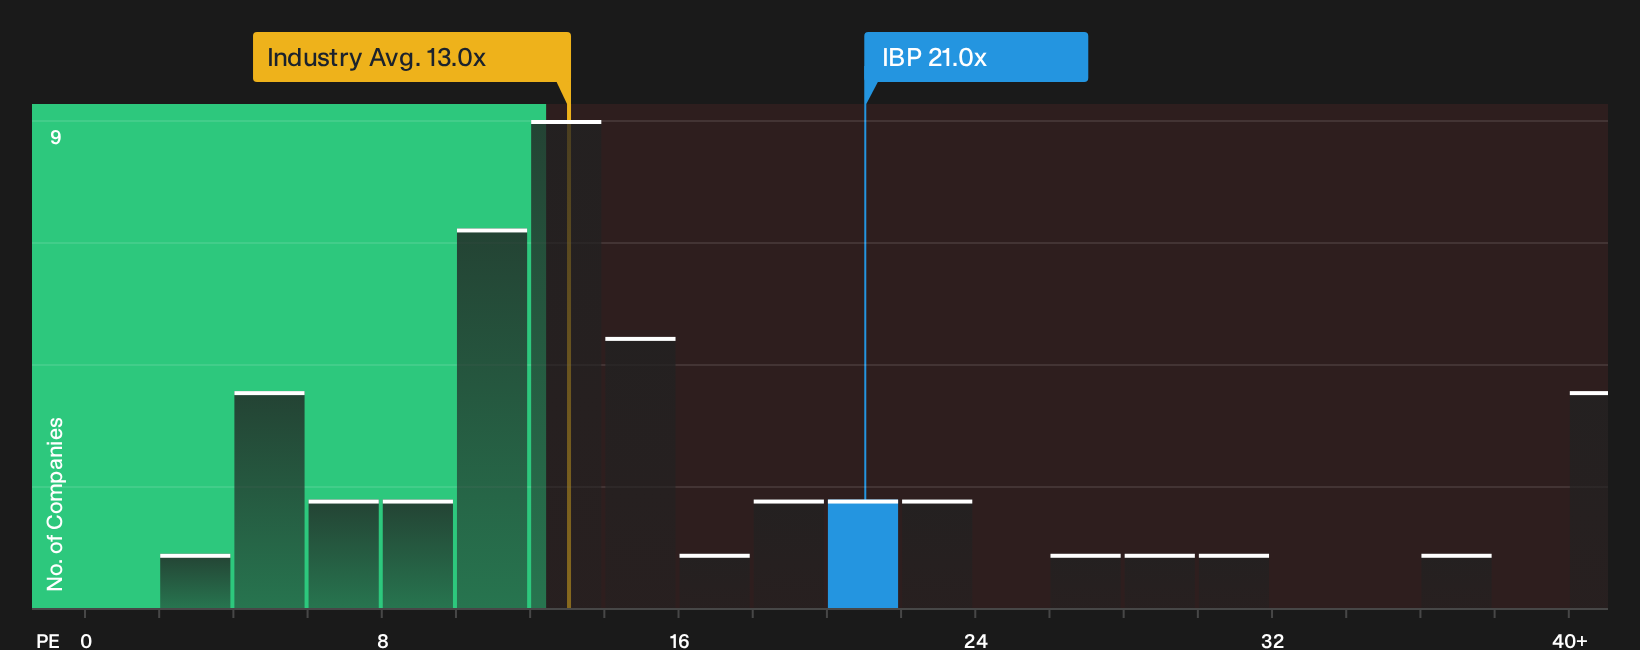
The SWS DCF model indicates that Installed Building Products is trading at a 17% discount to an estimated future cash flow value of $239.93, which is broadly in line with the $220.00 narrative fair value. The P/E perspective is less favorable, however. IBP trades at 21 times earnings compared with a fair ratio of 15.2 times, peers at 17.3 times and the US Consumer Durables average at 13.1 times. That premium can be viewed either as upside optionality or as valuation risk. Which interpretation do you think best reflects your own expectations?
See what the numbers suggest about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these are only useful if you pressure test them yourself and act promptly while sentiment remains divided. Weigh the full balance of potential upside and downside using the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Installed Building Products?
If you stop with Installed Building Products, you miss the chance to line up other strong candidates that could fit different roles in your portfolio.
- Target resilient performers with steadier profiles by reviewing a 30 resilient stocks with low risk scores that focuses on businesses with more measured risk characteristics.
- Hunt for strong cash generators trading below their implied worth by screening for 27 high quality undervalued stocks that combine quality fundamentals with pricing that may look appealing.
- Stack your watchlist with potential income plays by checking a 5 dividend fortresses that highlights companies offering higher yield alongside more robust balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com