
3 U.S. Bank Stocks Retail Investors Are Watching For Higher Rate Sensitive Yield
Inflation worries are back on center stage, with consumers pulling back on big-ticket purchases just as companies lift prices and oil costs surge. That mix can rattle many stocks, yet it can also reshape where cash flows and which short-duration cash and rate-sensitive plays come into focus. This article unpacks three U.S.-listed financial stocks exposed to this backdrop and explains why each might deserve a closer look now.
The three stocks that follow are only a sample of this theme. The full screen surfaced 33 more U.S.-listed banks and asset managers with equally detailed cash and rate stories that are not covered below. To go straight to the source and identify, compare, and analyze the highest-conviction short-duration cash and rate-sensitive yield ideas, move into the U.S. Short-Duration Cash & Rate-Sensitive Yield Plays screener.
National Bank Holdings (NBHC)
National Bank Holdings fits this short-duration cash and rate-sensitive theme because its core lending and deposit franchise lives off short-term spreads, giving extra relevance to how it handles fee-based cash management and newer digital efforts like 2UniFi.
"The 2UniFi small business platform is still in the investment phase, with expenses of about US$20 million to US$22 million in 2026 and guided revenue of US$2 million to US$4 million. Any improvement in credit conversion or monetisation could lift National Bank Holdings noninterest income and narrow the drag on earnings."
What happens to National Bank Holdings margins if that early stage investment either accelerates faster than expected or takes longer to gain traction?
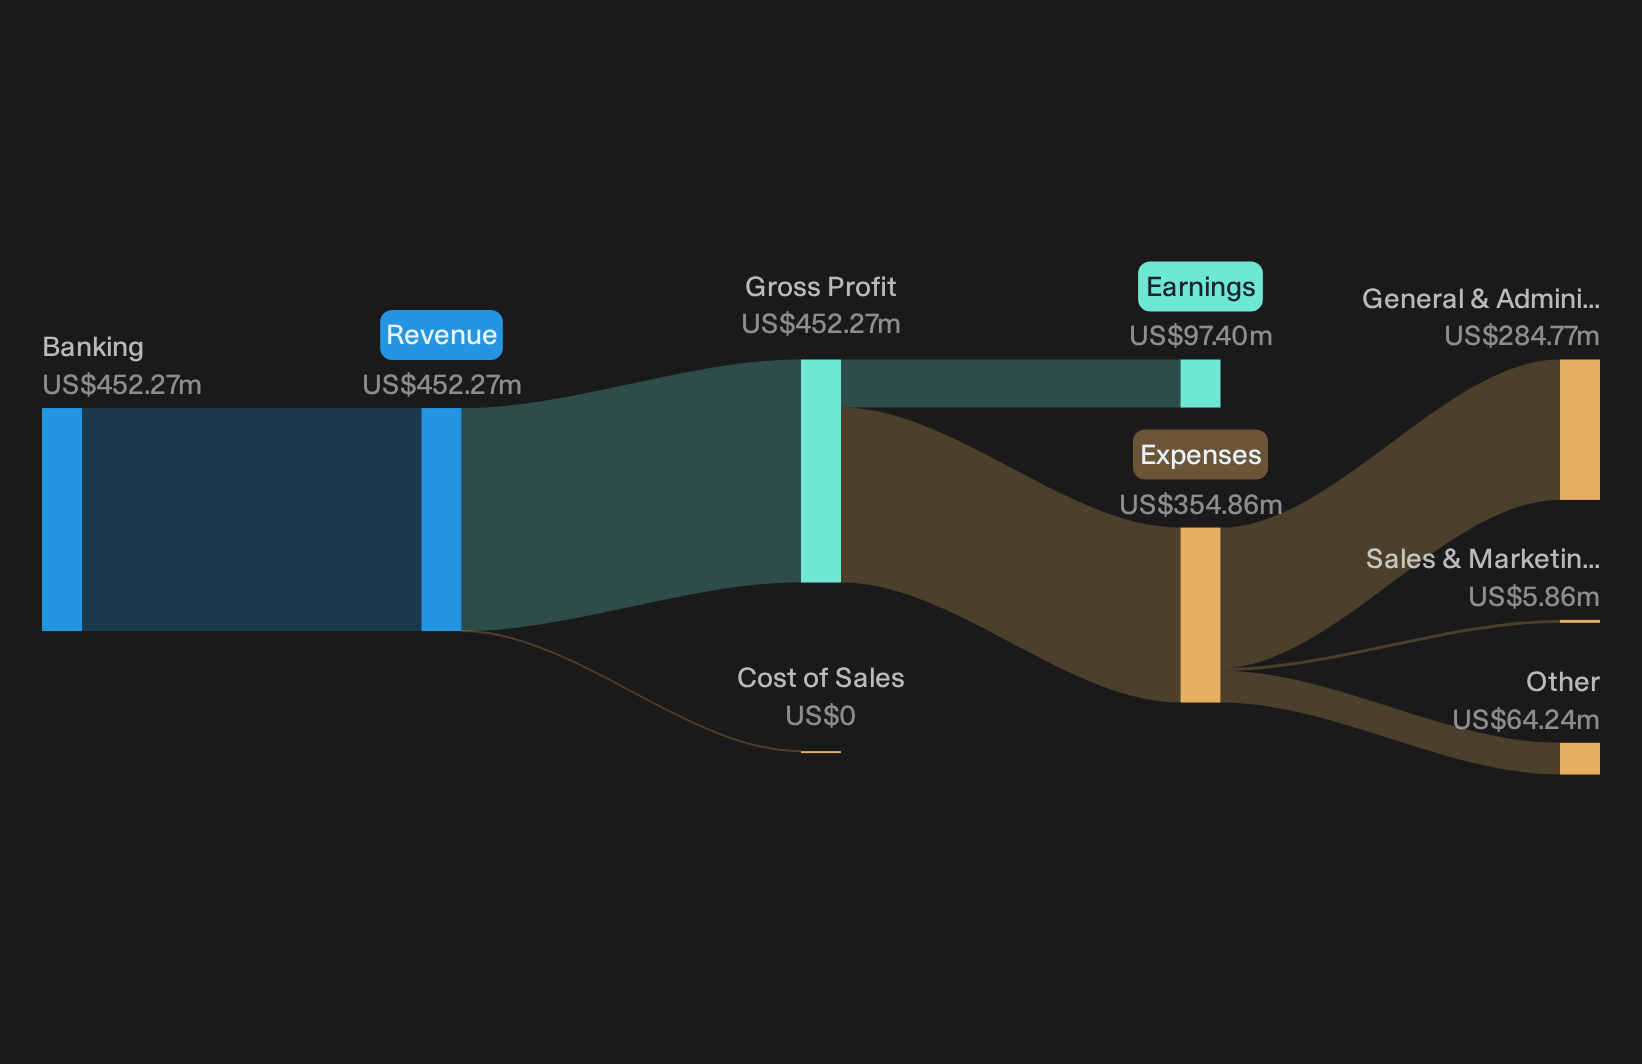
National Bank Holdings runs a regional U.S. bank focused on deposits and loans, generating about US$452 million from banking activities, with earnings linked closely to short-term spreads and cash-like balances, and carries a roughly US$1.7b market value.
If that margin story is what matters most to you, read the full narrative for National Bank Holdings to see how small shifts in 2UniFi could reshape the earnings mix.
First Horizon (FHN)
First Horizon leans heavily on traditional lending, fee-based services, and cash-rich deposit relationships. This places it squarely inside this short-duration cash and rate-sensitive theme as management reshapes the balance sheet to make rising short-term yields work harder.
"First Horizon is still targeting a multi year, $100m plus pre tax pre provision revenue uplift from deeper commercial relationships, with management now indicating progress of roughly 30% to 50% toward that goal, which can continue to support revenue and PPNR."
What happens to First Horizon's margins and earnings power if one unresolved pressure on its funding costs breaks differently than expected?
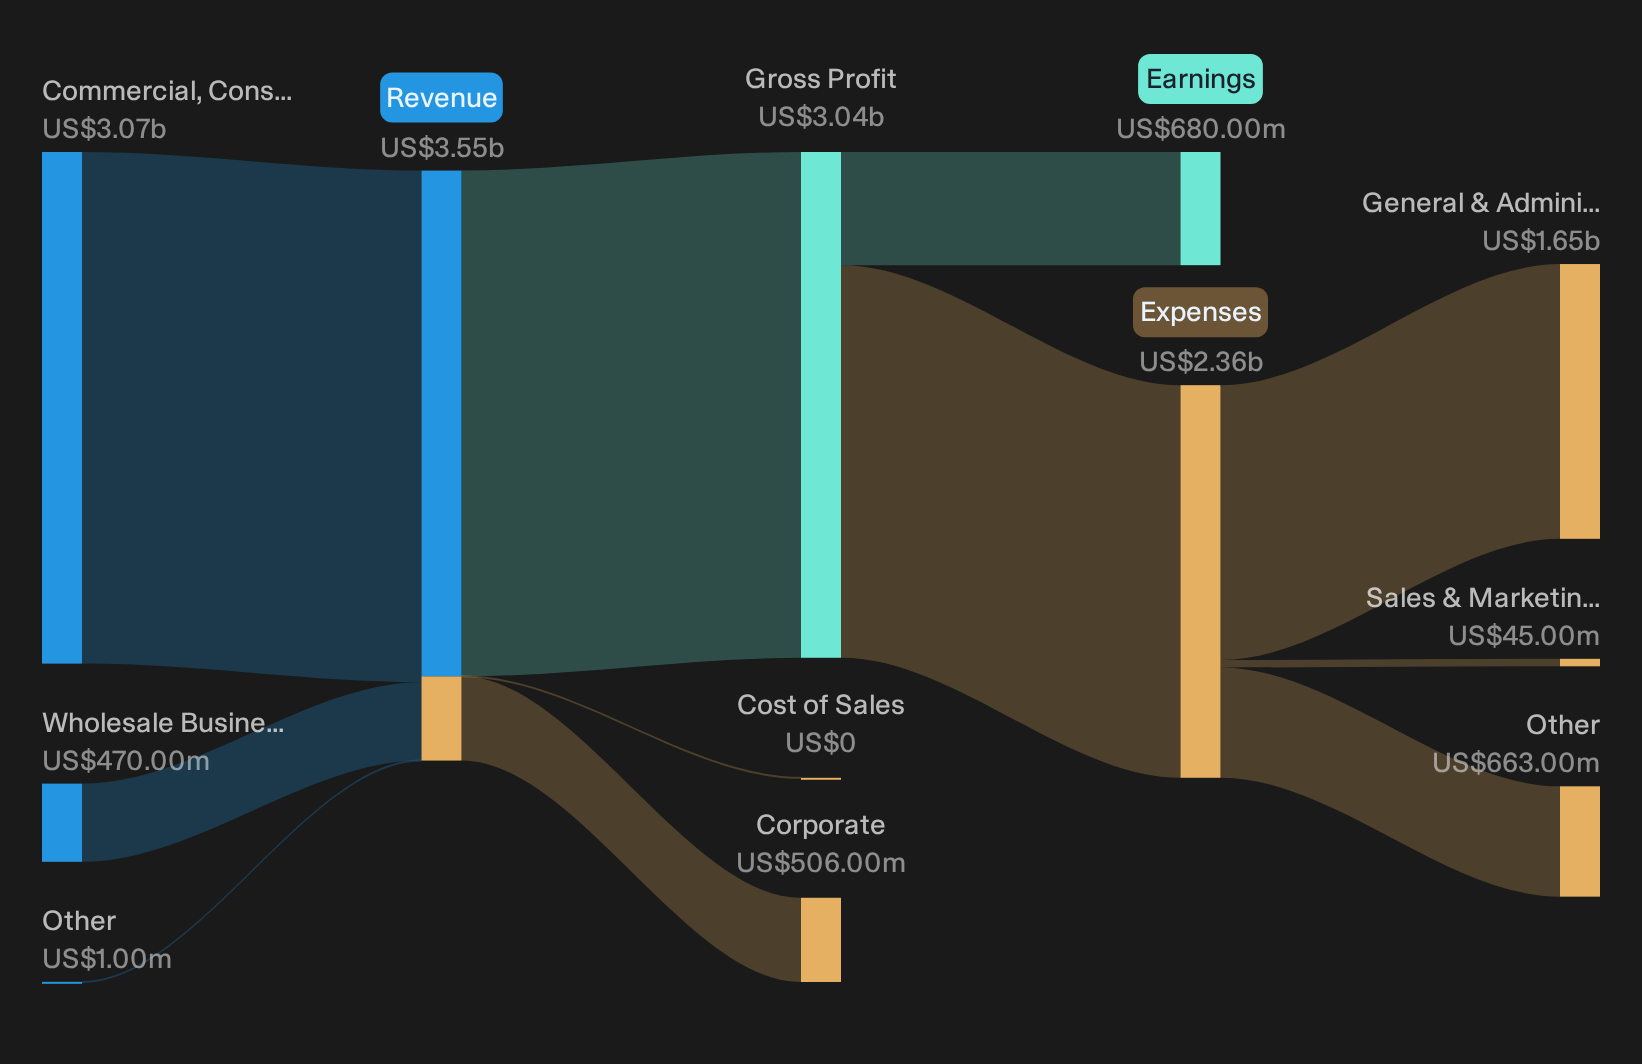
First Horizon Corporation runs a broad U.S. banking and capital-markets platform, with Commercial, Consumer and Wealth activities contributing about US$3.1b, Wholesale Business around US$470 million, and a smaller Corporate drag, and the stock valued at roughly US$11.2b.
If that funding swing is what you care about, move into the full narrative for First Horizon to see how First Horizon's earnings story could be accelerating beneath the surface.
Banc of California (BANC)
Banc of California leans into this short-duration cash and rate-sensitive theme through treasury services and business-focused deposits, giving its Commercial Banking franchise meaningful exposure to non-interest-bearing balances and short-term liquidity products when inflation worries keep policy rates elevated.
Banc of California generates about US$690 million from Commercial Banking in the United States and has a market value of roughly US$2.8b.
The ongoing shift to digital financial services across all demographics is accelerating Banc of California's ability to attract new customers, reduce its customer acquisition and operating costs, and expand core deposit growth. This is driving improved efficiency, net interest margins, and sustained earnings growth.
What really matters now is how one pressure point on funding costs and credit quality shapes that margin repair story investors care about most.
That margin repair hinge matters, and the full narrative for Banc of California explains how funding costs, credit risk and digital momentum could be masking a stronger Banc of California earnings engine.

Seeking Alternatives Before The Crowd?
Fresh opportunities can move quickly when momentum builds, prices move sharply, or quality stocks temporarily drop under the radar. Review these ideas while they may still be relevant and consider your options promptly.
- Target resilient income streams by scanning the 5 dividend fortresses that focus on cash flows and balance-sheet strength before yields reset and the best options are gone.
- Explore potential efficiency gains by reviewing the 95 robotics and automation stocks packed with automation leaders showing momentum while the broader market is still catching up.
- Assess potential infrastructure themes by reviewing the 42 power grid technology and infrastructure stocks where grid upgrades and electrification trends could be priced more cheaply today.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com