
Is Viavi Solutions (VIAV) Cheap Following Its U.S. Army Test Range Win?
Viavi Solutions (VIAV) is back in focus after the U.S. Army's Threat Systems Management Office picked its T/Rx software defined transceiver to create electromagnetic spectrum test environments across newly opened military ranges.
That Army contract lands at an interesting moment for Viavi Solutions, because momentum in the share price has cooled in recent weeks even as longer term returns remain strong. The stock has a 1 day share price return of 0.48% and is down 16.43% over 30 days and 22.96% over 90 days, yet the year to date share price return is 67.74% and the 1 year total shareholder return is 121.42%, with a 3 year total shareholder return of about 3x and a 5 year total shareholder return of 97.69%. This points to strong long term gains despite the recent pullback.
Scan beyond Viavi Solutions and see how other defense focused and high-spec hardware players are priced by reviewing the hand picked 42 power grid technology and infrastructure stocks in a single view.
After a run that turned a recent slide into just a dent on longer term charts, Viavi Solutions now sits in a tricky middle zone. Has the bulk of the rerating already played out, or do the current valuation markers still leave the potential for further upside?
Most Popular Narrative: 50% Undervalued
On the numbers, the most followed narrative pegs Viavi Solutions at a fair value of about $61 per share compared with a last close of $30.45, a gap that puts a lot of weight on how the AI, data center and 6G test story plays out.
Viavi is experiencing robust and sustained demand across the data center ecosystem, with customers updating optical connectivity to 400G, 800G, and now 1.6T enabling multi-year upgrade cycles and expanding its total addressable market, which should drive structural revenue growth through 2026 and beyond. Increasing demand for end-to-end network instrumentation from the data center sector, now viewed as mission-critical, should reduce historical cyclicality linked to telecom service provider budgets and provide more consistent revenue visibility and smoother earnings trajectory.
See why 15 investors see Viavi Solutions as 50% undervalued.
Result: Fair Value of $61.43 (UNDERVALUED)
Still, the Viavi Solutions narrative can unravel if wireless test demand stays weak or if recent acquisitions fail to integrate cleanly and drag on profitability.
Find out about the key risks to this Viavi Solutions narrative.
Another View: What Viavi Solutions Looks Like On Sales Multiples
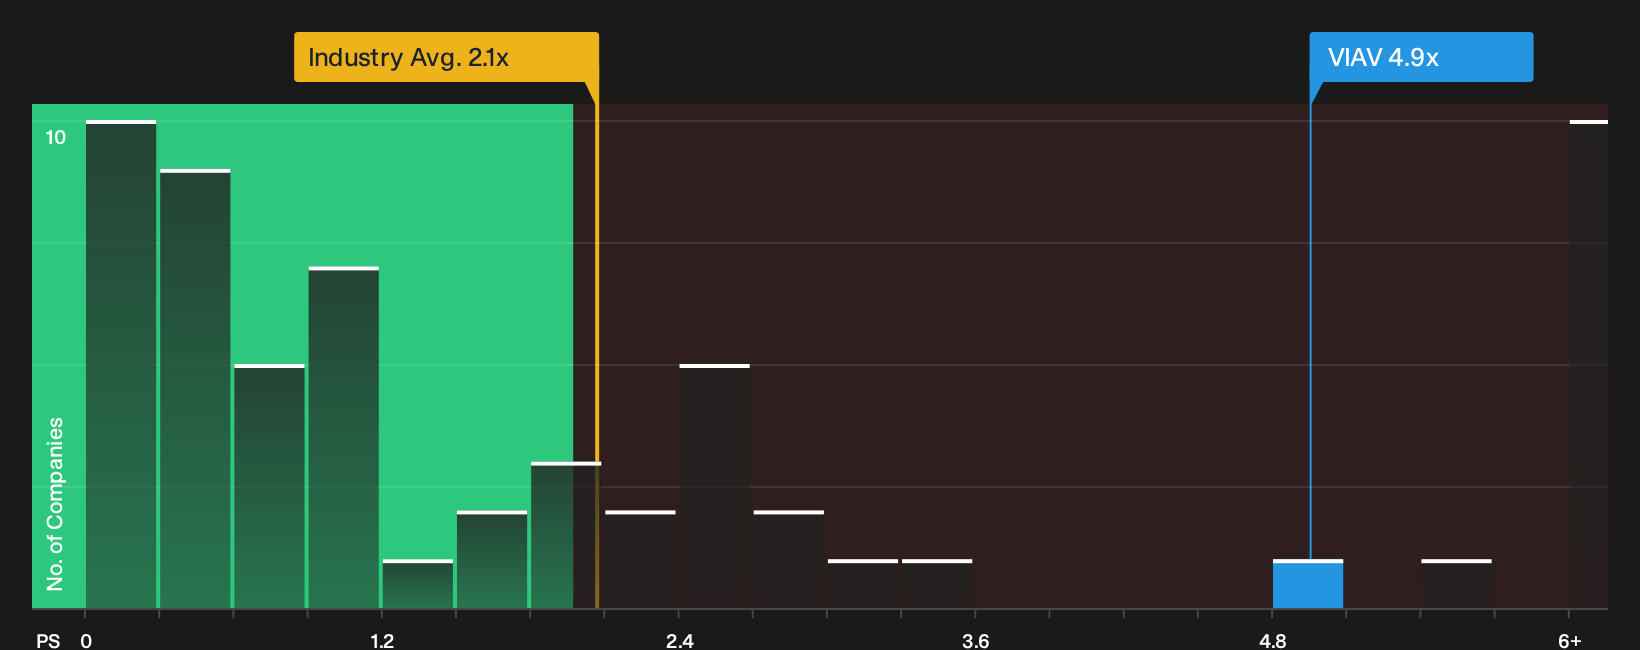
That analyst fair value around $61 leans heavily on long term forecasts. A simpler yardstick looks at what investors pay for each dollar of Viavi Solutions revenue. On a P/S of 4.9x, the stock trades richer than the US Communications sector average of 2.1x but below peer levels at 5.2x, while the fair ratio of 7.3x suggests the market could still move higher if enthusiasm returns. Is that a cushion or a warning sign if expectations cool again?
For a closer breakdown of what this pricing gap could mean in practice, and how much room the multiple leaves for error or surprise, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Viavi Solutions can be confusing, so move quickly from headline impressions to your own view by weighing both sides of the story with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Viavi Solutions?
If you stop with Viavi Solutions, you risk missing other setups that fit your style, your risk limits, and your return goals.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a marked down price level through the 27 high quality undervalued stocks.
- Zero in on overlooked opportunities with strong financial footing using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com