
Somnigroup International (SGI) Wins Automotive Comfort Honors, Is The Stock Still A Bargain?
Somnigroup International’s automotive comfort win catches investor attention
Somnigroup International (SGI) is in focus after its Leggett Dynamics unit earned industry awards for the Mid-Class Massage System, now in serial production with a global automaker, spotlighting a new revenue stream beyond bedding.
The market reaction has been mixed. Somnigroup International’s share price slipped 1.99% over the last session but is up 2.88% over the past month and 1.73% across seven days, while the stock’s total shareholder return is down 21.28% over one year yet still up over three and five years, which suggests recent momentum has cooled after a multi year run.
Spot similar under-the-radar comfort and auto suppliers by scanning our hand picked 21 high quality undiscovered gems, which pair established franchises like Somnigroup International with fresh growth angles in adjacent markets.After a multi year run and a sharp pullback this year, Somnigroup International now pairs fresh automotive momentum with a softer share price. Does that tilt the risk reward toward buyers, or toward caution as valuation comes under the microscope next?
Most Popular Narrative: 31% Undervalued
Somnigroup International closed at $64.68, while the most followed narrative pegs fair value near $93.44. As a result, the current quote sits well below that modeled level and puts the focus squarely on what could justify the gap.
The integration of Mattress Firm is already generating meaningful sales and cost synergies, with $100 million in annual net cost synergies projected and sales synergies ahead of schedule. These operational improvements are expected to expand EBITDA and enhance net margins moving into 2026 and beyond.
See why 6 investors see Somnigroup International as 31% undervalued.
Result: Fair Value of $93.44 (UNDERVALUED)
Still, softer bedding demand and pressure from online only competitors could easily derail the Somnigroup International optimism that analysts have modeled into those 2029 targets.
Find out about the key risks to this Somnigroup International narrative.
Another view on Somnigroup International’s valuation
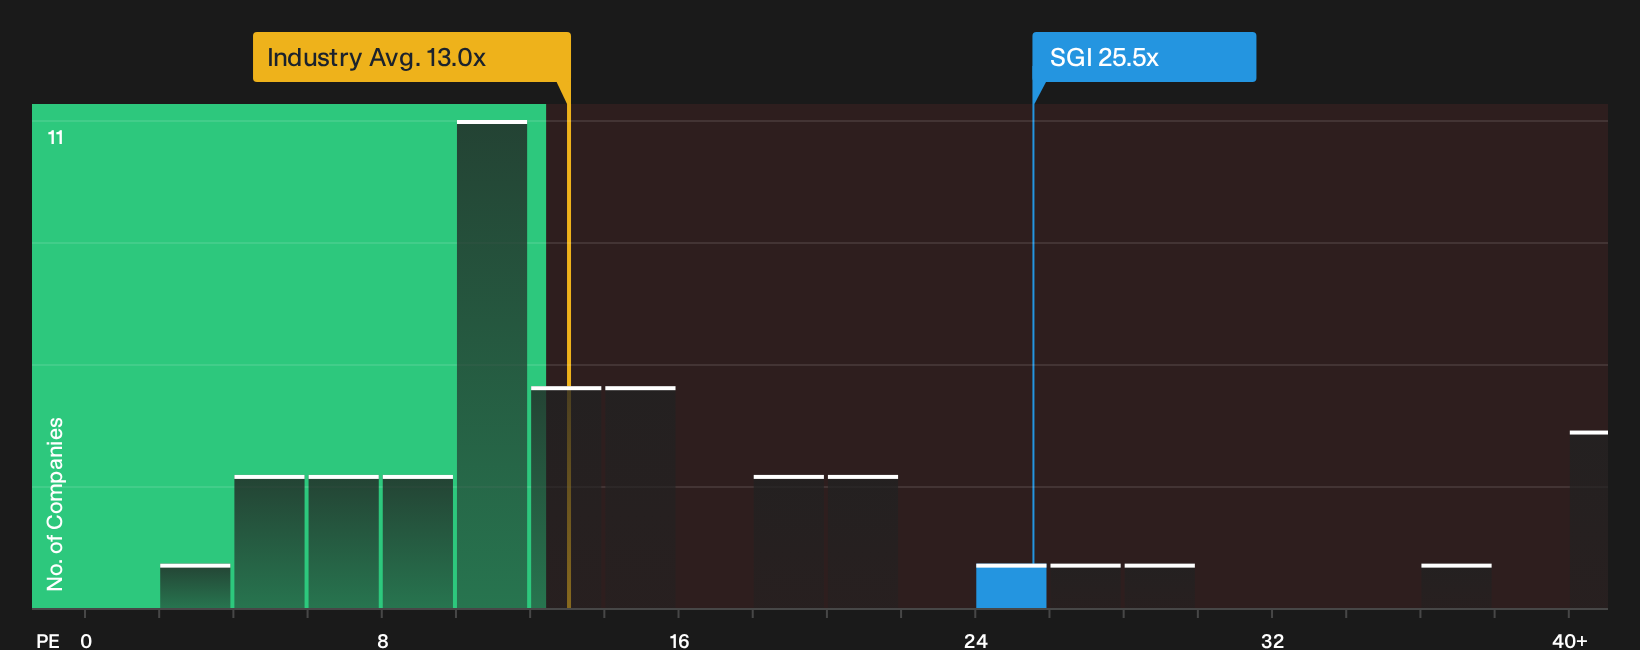
On earnings multiples, Somnigroup International looks richer than it first appears. The stock trades on a P/E of 25.5x versus 13.1x for the US Consumer Durables industry and 15.7x for peers, above a fair ratio of 23.9x. That premium suggests less room for error if the growth story stumbles.
For anyone weighing those multiples against the earlier fair value work, it is worth asking whether the earnings profile truly justifies paying well over sector and peer levels, or if investors are leaning too hard on optimistic scenarios as competition and debt sit in the background.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Somnigroup International can feel confusing, so move fast, check the numbers for yourself, and weigh both sides of the story. To see how risks and potential upsides balance out, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Somnigroup International?
You do not need to stop with Somnigroup International. Put these tools to work and keep building a watchlist that fits your own risk and income goals.
- Target potential mispricing by focusing on quality enterprises trading below modeled value through the 27 high quality undervalued stocks.
- Strengthen income potential by concentrating on companies labelled as 5 dividend fortresses that combine higher yields with underlying business durability.
- Cushion portfolio swings by filtering for 30 resilient stocks with low risk scores that keep volatility and fundamental risk scores in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com