
How Strong Q3 Results Will Impact United Airlines Stock (UAL)
- United Airlines Holdings reported Q3 2026 revenue of US$17.9b and earnings per share of US$3.14, with premium cabins and loyalty income growing faster than the rest of the business, while higher fuel costs still weighed on margins.
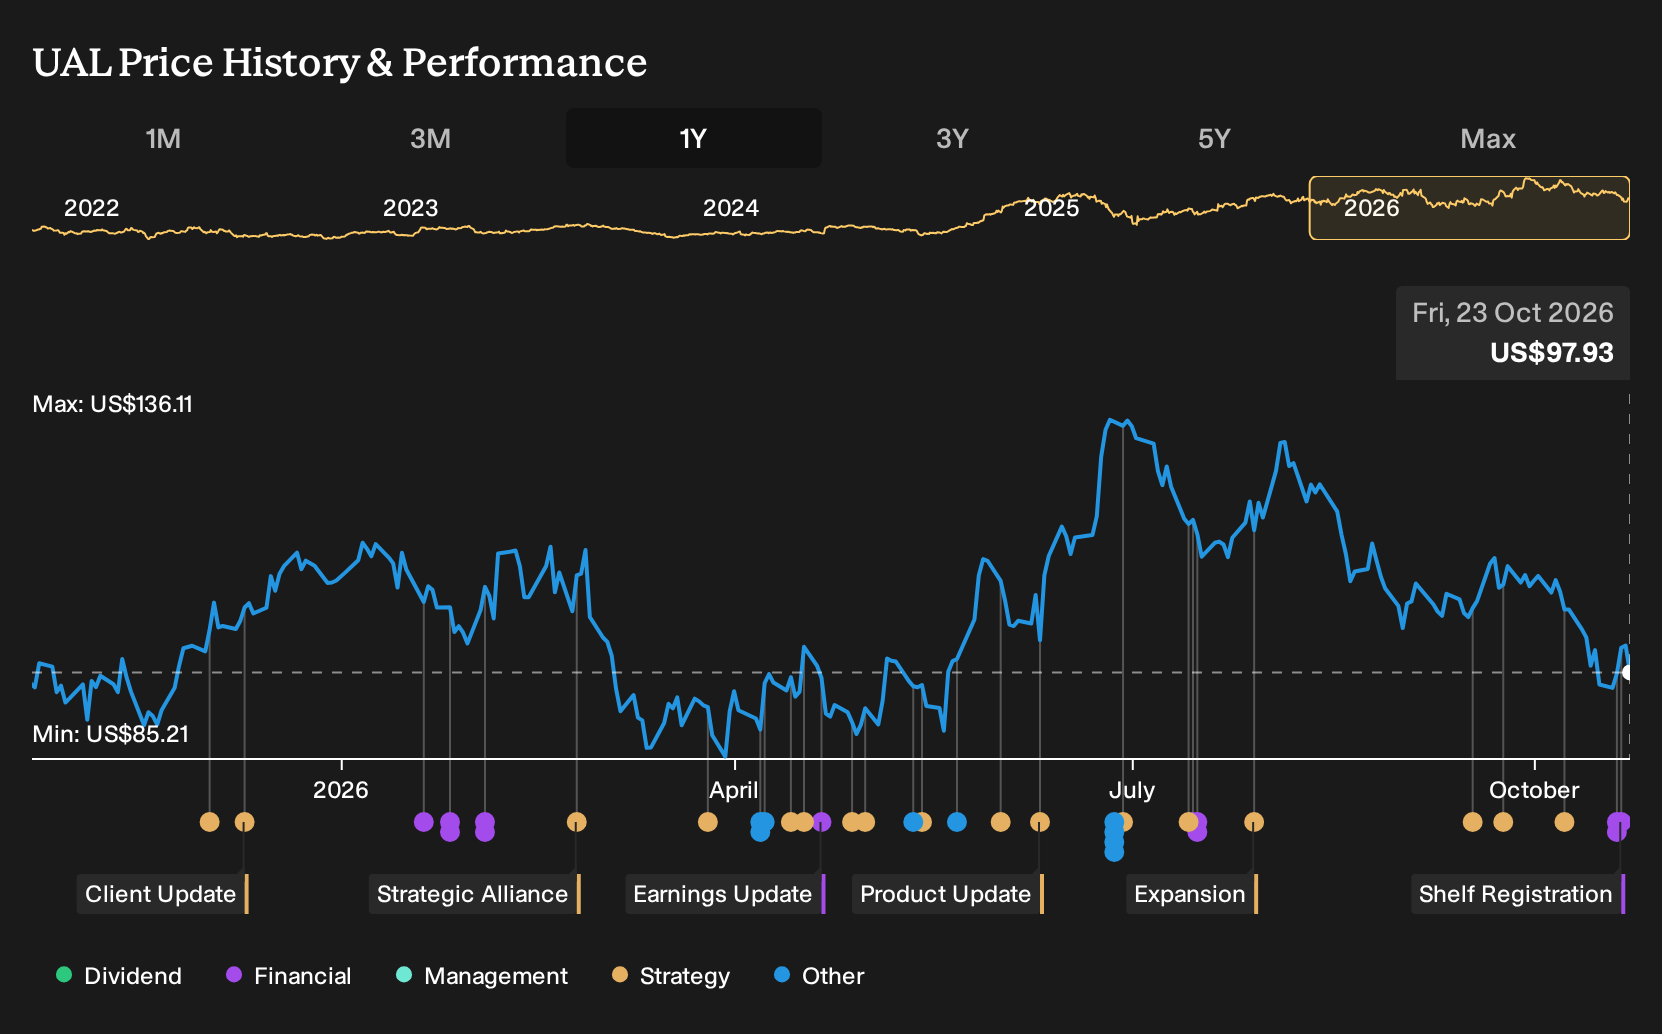
- The airline plans to continue focusing on this premium and loyalty mix, and has also filed an omnibus shelf registration that could give management flexible access to equity and debt funding if it chooses to finance future fleet, technology or balance sheet moves.
- We will now look at how United Airlines Holdings' investment narrative is shaped by strong premium demand and resilient profitability.
United Airlines Holdings Investment Narrative Recap
To own United Airlines Holdings, you need to believe the premium, loyalty and technology focus can offset fuel swings and a heavy balance sheet. Recent Q3 results showed solid profitability despite higher jet fuel, helped by premium demand and pricing power. The key short term catalyst is whether that mix still supports record revenue through Q4 2026.
The biggest near term risk comes from fuel costs and what they do to already thin margins and free cash flow. If jet fuel stays expensive or demand softens, management’s ability to recapture costs through fares and keep pretax margins resilient becomes the pressure point to watch.
The most relevant recent announcement is United Airlines Holdings’ Q4 2026 outlook. Management expects operating revenue growth above Q3 levels and guides earnings per share to US$0.50 to US$1.50, assuming all in fuel at about US$4.80 per gallon. That outlook is central to the near term test of the premium and loyalty thesis.
This forecast ties directly to the core catalysts investors are watching. Premium cabins, higher yielding business traffic and growing loyalty revenue need to offset elevated fuel, labor and fleet expenses. Delivery against this guidance would support the view that operational execution and pricing discipline can handle a structurally higher fuel cost base.
United Airlines Holdings' story is anchored to analysts forecasting US$75.2b in revenue and US$4.2b in earnings by 2029, which implies 6.2% yearly revenue growth and an earnings increase of about US$0.7b from US$3.5b today.
Uncover how United Airlines Holdings' fair value indicates a 56% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Think of the bullish view on United Airlines Holdings as a bet on loyalty income doing even more of the heavy lifting. The most optimistic analysts were penciling in revenue of about US$82.4b and earnings of US$6.0b by 2029, well above the consensus path before this latest guidance and shelf registration. Opinions may shift as fresh information lands, so explore a range of those viewpoints for yourself.
Explore 3 other United Airlines Holdings fair value estimates, including one that suggests as much as 97% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your United Airlines Holdings research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for United Airlines Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Airlines Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Airlines Holdings?
If the premium and loyalty angle at United Airlines Holdings has sharpened your thinking about resilience and balance sheet strength, you may want to broaden that lens to other companies using the Simply Wall St Screener. You can focus on different edges that matter to you and let the filters surface stocks that fit your own playbook.
- For income focused investors who want yield backed by fundamentals, you can scan a curated set of 5 dividend fortresses that aim to keep distributions supported by robust cash generation.
- If capital preservation and steadier risk profiles sit higher on your priority list, you can filter for 30 resilient stocks with low risk scores and see which businesses pair earnings quality with more measured volatility.
- When you want to research potential future leaders early, you can use the screener highlighting 21 high quality undiscovered gems that combine certain financial characteristics with relatively limited market attention so far.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com