
Improved Earnings Outlook Could Be A Factor For Affiliated Managers Group Stock
- Affiliated Managers Group is currently highlighted for an improved earnings outlook, with valuation metrics such as a forward P/E of 10.68 and a PEG ratio of 0.50 comparing favorably to larger peer BlackRock.
- The combination of a Value grade of B and lower forward P/E and PEG ratios than BlackRock underscores how AMG’s affiliate driven model is currently viewed as offering stronger value characteristics within the asset management sector.
- We will look at how Affiliated Managers Group's investment narrative aligns with this improved earnings outlook and relative value positioning.
Scan other asset managers with similar value characteristics by reviewing the 27 high quality undervalued stocks, which combines compressed P/E multiples with stronger quality signals.
Affiliated Managers Group Investment Narrative Recap
For an investor to own Affiliated Managers Group, there needs to be confidence that the affiliate model keeps converting client demand for alternatives and quantitative strategies into fee based earnings, even as traditional active equity outflows persist. The recent improvement in the earnings outlook mainly reinforces that story, rather than changing it. The key near term swing factor remains whether alternatives inflows continue to offset weaker long only flows and support operating leverage.
The biggest risk still sits in concentration. AQR and Pantheon drive more than 30% of adjusted EBITDA and alternatives account for over 60% of earnings, so any stumble at these affiliates could hit fee income quickly. Heavy capital deployment and buybacks amplify that risk because weaker performance at new affiliates would leave Affiliated Managers Group with lower EBITDA and more volatile economic EPS than recent results suggest.
With no new operational announcements since the October 22 valuation and earnings update, the most relevant data point remains the combination of AMG’s forward P/E of 10.68, PEG of 0.50 and its Value grade of B, compared with BlackRock’s higher multiples and weaker value score. That relative pricing, paired with an improving earnings outlook, is what ties the current news flow together for investors watching near term catalysts.
Those same metrics matter for how you weigh the risks already flagged. Affiliated Managers Group carries a high level of debt and has meaningful one off items in recent results, even as earnings grew 93.6% over the past year and return on equity sits at 25%. The question is whether alternatives inflows and disciplined affiliate investments can keep supporting that earnings profile while the balance sheet and concentration risks stay contained.
What The Current Forecasts Assume For Affiliated Managers Group
Analysts are effectively asking investors to believe that Affiliated Managers Group can compound its fee base at a measured pace, with revenue projected to grow by 6.0% a year over the next three years while profit margins ease slightly from 37.7% today to 37.1% by 2029. That mix points to moderate top line expansion paired with a small step down in profitability, which matters because it frames how much of the affiliate driven alternatives story needs to turn into cash earnings for the current valuation to hold up.
The earnings path those forecasts sketch out is fairly specific. Consensus points to earnings today of $856.3 million rising to about $1.0b by 2029, which is an increase of roughly $143.7 million over that period. That step up in profit, along with expectations for a 7.0% annual decline in the share count over the next three years, is what underpins the projected earnings per share of $40.89 and the implied economic EPS growth investors are being asked to underwrite.
Affiliated Managers Group's narrative projects revenues of $2.7b and earnings of $1.0b by 2029. This requires 6.0% yearly revenue growth and an earnings increase of about $143.7 million from $856.3 million today.
On these numbers, the valuation bridge is straightforward enough to track. To line up with the consensus targets, you would need to assume the stock trades on a P/E multiple of 11.9x in 2029, compared with about 11.6x on current earnings and well below the 38.1x figure quoted for the wider US Capital Markets industry. That implies only a modest uplift in the multiple on Affiliated Managers Group itself, with most of the heavy lifting coming from the earnings progression and the shrinking share count rather than a dramatic re rating.
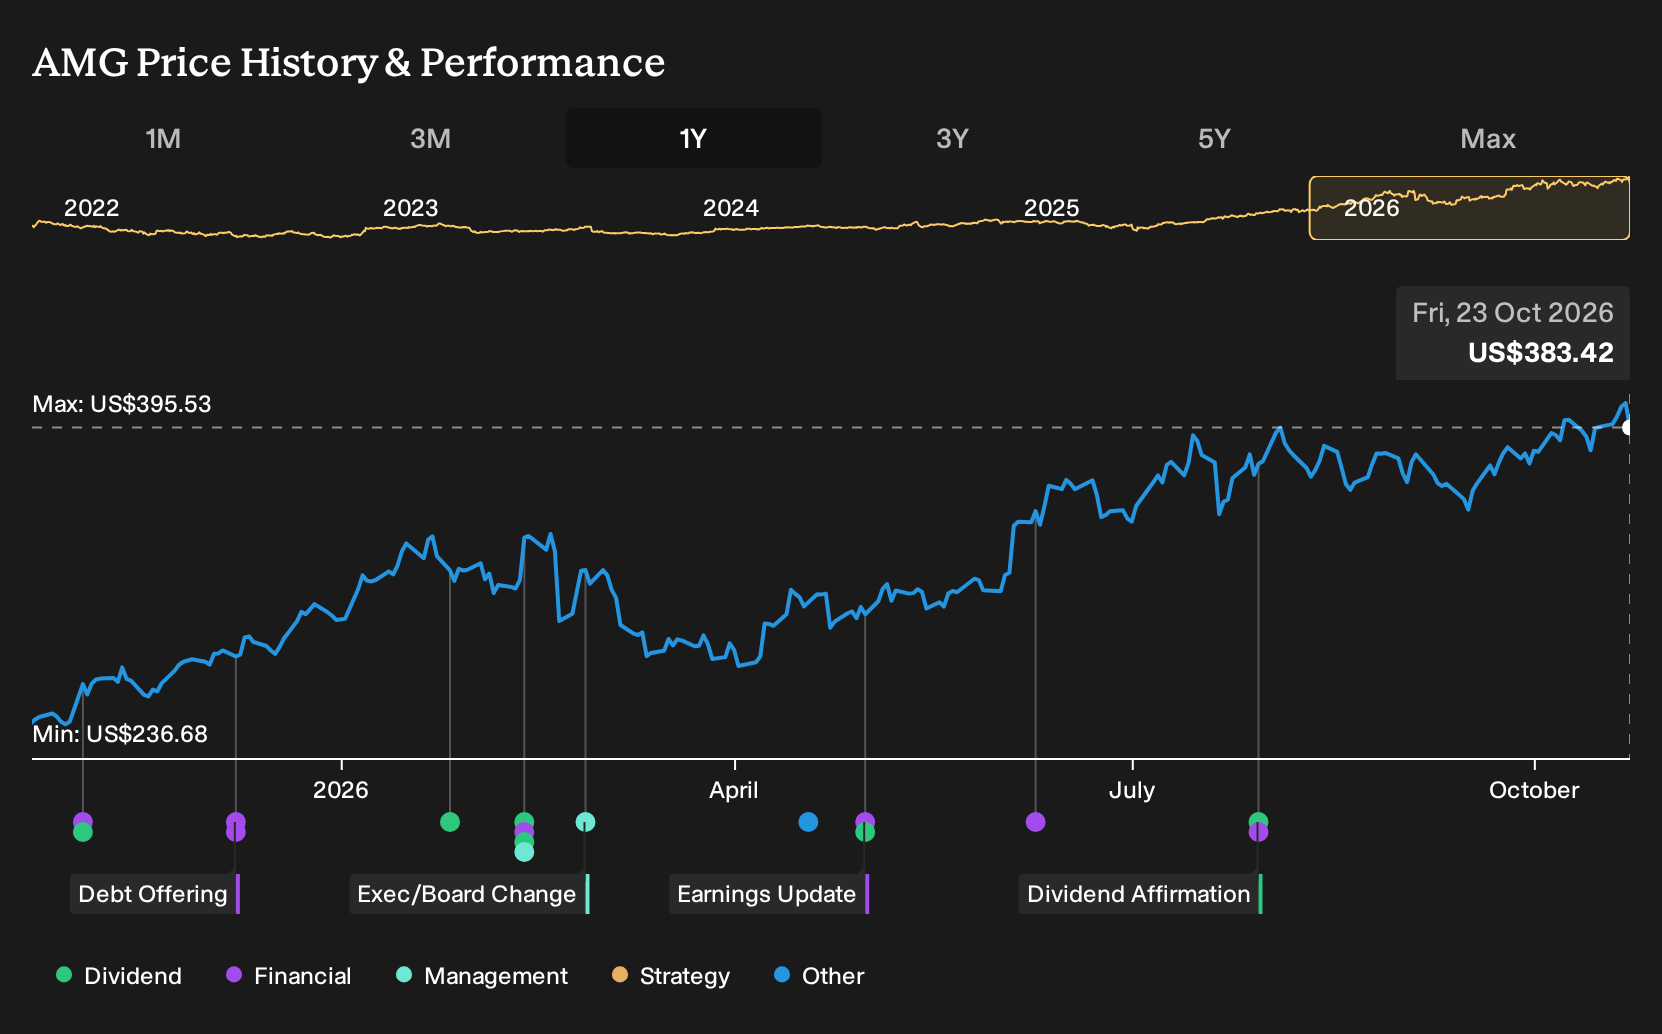
Forecasts do come with a range. The more cautious analysts see earnings closer to $865.7 million instead of the $1.0b headline figure, and price targets stretch from $360.0 to $523.0 per share around a consensus of $445.71. With the stock recently at $383.76, that central target sits 13.9% higher, which gives you a sense of how much of the alternatives and buyback story is already reflected in expectations and how much additional upside those covering the stock are factoring in if the current plan stays on track.
Uncover why Affiliated Managers Group's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Affiliated Managers Group, the most upbeat analysts lean hard into alternatives as the key catalyst. They were already penciling in US$3.2b of 2029 revenue and US$1.0b of earnings, which is more aggressive than consensus. These forecasts predate the latest value focused news, so some views may shift as fresh data lands.
Explore 2 other Affiliated Managers Group fair value estimates, including one that suggests up to 16% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Affiliated Managers Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Affiliated Managers Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Affiliated Managers Group's overall financial health at a glance.
Looking for more Affiliated Managers Group style ideas?
If the Affiliated Managers Group story has you thinking about similar setups in other stocks, it can help to widen your search using a structured tool rather than relying only on headlines or a short watchlist.
- For investors who want compressed valuations paired with solid fundamentals, scan our universe of potential value opportunities through the 27 high quality undervalued stocks.
- If downside resilience matters most to you, narrow your focus to companies that score well on stability and financial risk using the 30 resilient stocks with low risk scores.
- When you are hunting for underfollowed opportunities with healthier balance sheets and fundamentals, cast a wider net with the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com