
Wallenstam (OM:WALL B), What Is Behind The Fresh Attention?
Wallenstam (OM:WALL B) has moved back into focus after its third quarter and nine-month 2026 report, which showed higher sales, revenue, net income, and earnings per share compared with the prior year.
At a share price of SEK38.32, Wallenstam has seen a 7 day share price return of 3.01%, although the 90 day share price return is down 5.15% and the 1 year total shareholder return is down 14.65%, which suggests recent interest after a weaker year.
Scan beyond Wallenstam's recent earnings reaction and size up other property-focused plays using our hand picked list of solid balance sheet and fundamentals (204 results) as a starting universe.
Wallenstam has bounced on stronger quarterly numbers, yet the share is still below both intrinsic estimates and analyst targets. Is that discount justified caution, or is it an opportunity that valuation work can clarify next?
Most Popular Narrative: 30% Undervalued
The most followed narrative pegs Wallenstam's fair value at SEK55, which sits well above the latest close at SEK38.32. That gap rests on concrete rent uplifts, a visible project pipeline, and how effectively management turns those ingredients into recurring earnings.
The recent rent negotiations that added SEK 43 million of higher rental income on an average 4% uplift in residential and 1.6% in commercial base rents point to future periods where similar repricing could compound on an already high occupancy base. This would support further growth in recurring revenue.
See why 0 investors see Wallenstam as 30% undervalued.
Result: Fair Value of SEK55 (UNDERVALUED)
Still, rising operating and administrative costs, along with higher tariffs for heating and water, could erode the bullish Wallenstam case if rent uplifts lag.
Find out about the key risks to this Wallenstam narrative.
Another View: What The SWS DCF Model Says
The popular Wallenstam narrative leans on a fair value of SEK55 and labels the stock as undervalued. The SWS DCF model tells a very different story. At SEK38.32, Wallenstam trades far above an estimated future cash flow value of SEK1.5, which frames the shares as expensive on this lens. That split raises a simple question for you: Are earnings-based assumptions or cash flow realism more important in your own framework?
Before leaning on either camp, it can help to see exactly how the SWS DCF model pieces together cash flow, discount rate, and terminal assumptions for Wallenstam, and what would need to shift for the gap to close. Look into how the SWS DCF model arrives at its fair value.
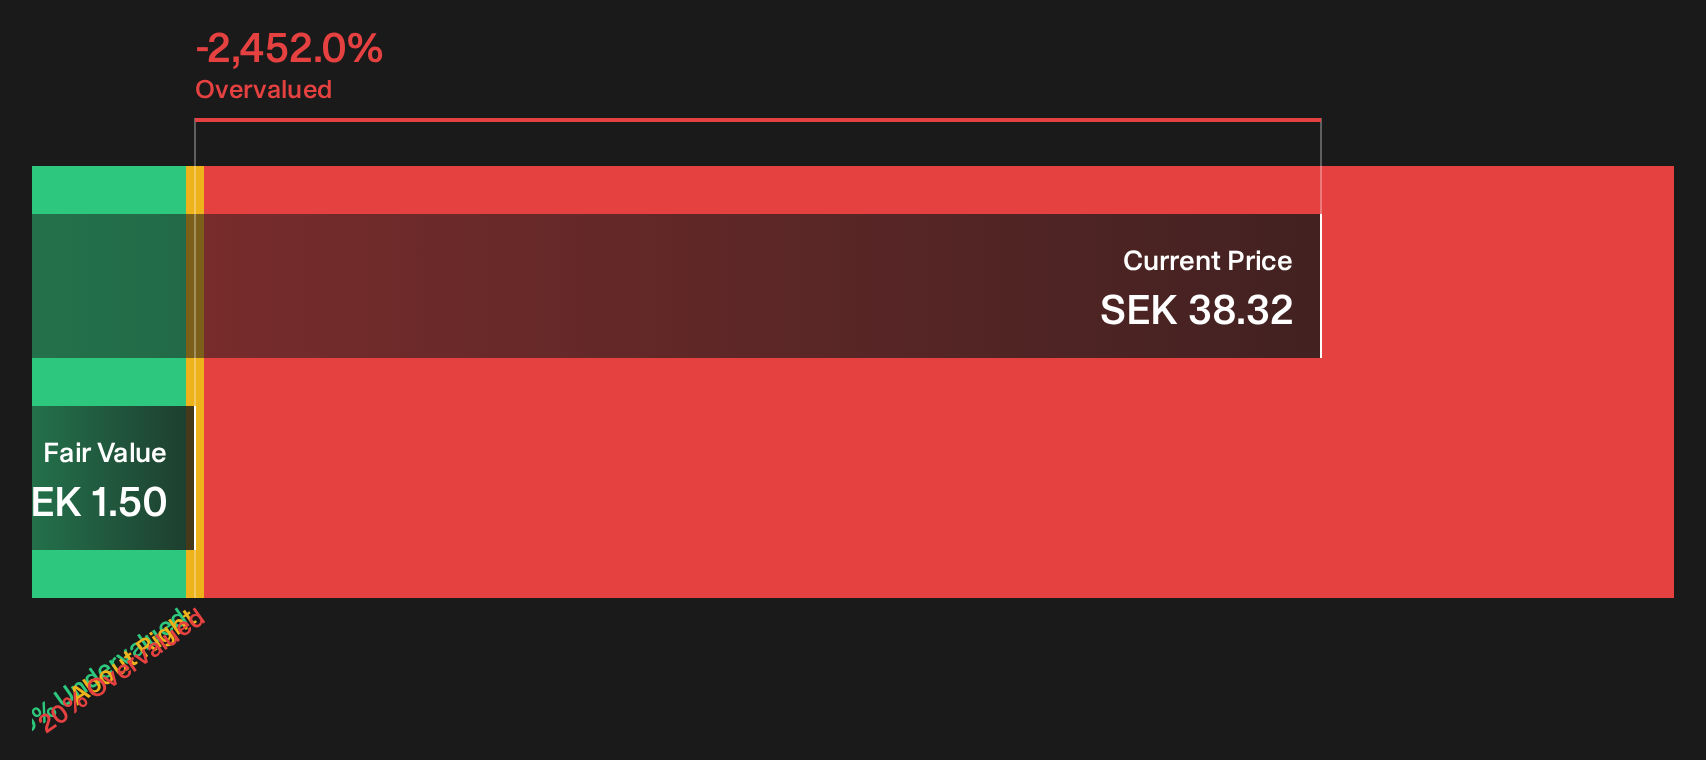
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Wallenstam for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Wallenstam so far, or a clear skew in one direction? Act while the facts are fresh and pressure test the bullish and cautious angles against the 3 key rewards and 3 important warning signs.
Looking for more ideas beyond Wallenstam?
Do not stop at Wallenstam. Fresh opportunities emerge constantly, and broadening your watchlist now can change the way you think about risk, income, and long term potential.
- Target resilience first and scan a 221 resilient stocks with low risk scores that focuses on businesses with steadier risk profiles and more defensible balance sheets.
- Hunt for value gaps by reviewing a 192 high quality undervalued stocks that surfaces stocks where fundamentals and price appear out of sync.
- Prioritize dependable income by checking a 226 dividend fortresses built around higher yielding companies with stronger support for ongoing payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com