
Does Infrastructure Expansion Change The Bull Case For Targa Resources (TRGP)?
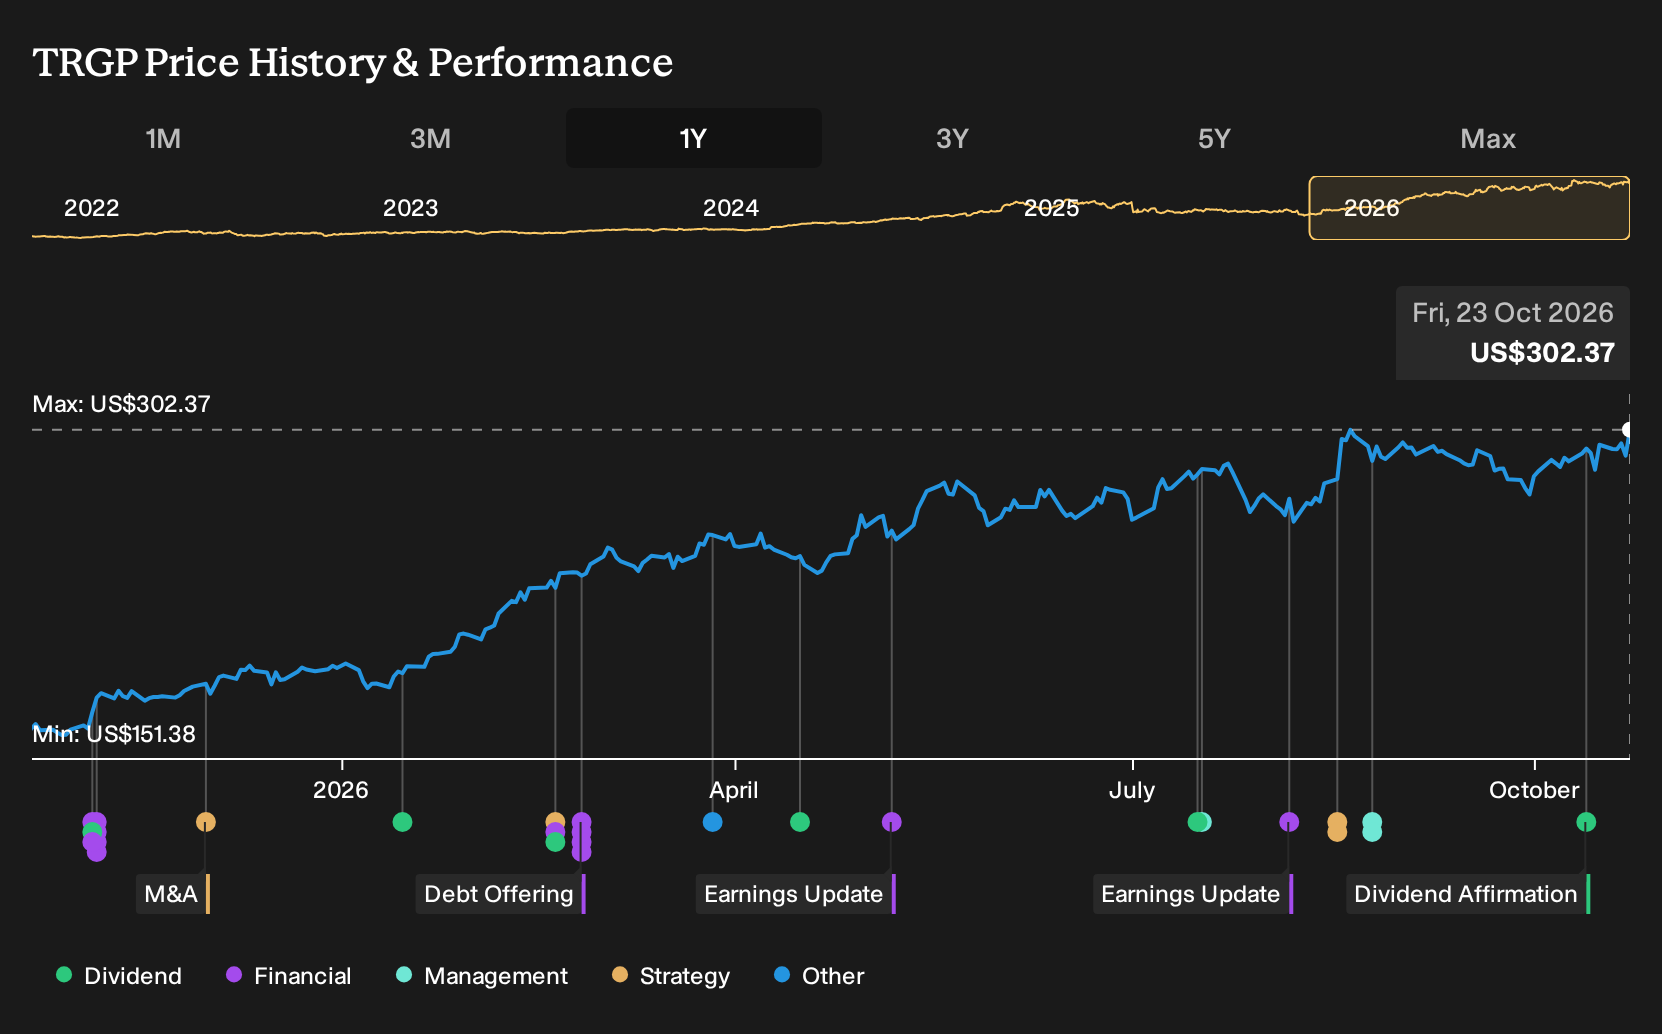
- Targa Resources declared a quarterly cash dividend of US$1.25 per common share for Q3 2026, or US$5.00 on an annualized basis, payable on November 17, 2026 to shareholders of record on October 30, 2026.
- The higher payout sits alongside rising adjusted EBITDA, new Permian gas processing plants and a 20 year ExxonMobil agreement, which together highlight how current capital projects and long term contracts are feeding into cash generation that can fund both growth and returns.
- We will look at how Targa Resources' investment narrative is shaped by this higher dividend.
Targa Resources Investment Narrative Recap
Targa Resources is still an execution story. To be comfortable as a shareholder, you need to believe the build out in Permian gas plants, NGL pipelines and Gulf Coast export capacity will keep filling with fee based volumes over time. The higher Q3 2026 dividend signals confidence, but the short term focus remains on delivering the November 5 earnings print and keeping leverage in the 3x to 4x range.
The biggest near term swing factor is how quickly new plants and fractionation assets ramp while producers maintain activity on Targa Resources acreage. The main risk is that heavy growth capex and high debt collide with any slowdown in volumes or fee pressure, which could crimp future free cash flow and limit flexibility on dividends or buybacks.
The dividend declaration to US$1.25 per share for Q3 2026 ties directly into that operational picture. It is based on recent adjusted EBITDA growth, the expanding Permian footprint and long term contracts such as the 20 year ExxonMobil agreement. The cash return appears more compelling when set against a long history of total return outperformance and high forecast return on equity.
For you, the real question is whether Targa Resources can keep funding this higher payout while spending roughly US$4.5b each year on growth projects and about US$250m on maintenance. That requires disciplined project delivery on Speedway, new gas plants and LPG export expansions, plus stable customer volumes. Otherwise, dividend coverage and balance sheet strength could come under pressure.
What The Forecasts Assume About Targa Resources
Analysts are effectively linking Targa Resources' richer dividend profile to a bigger enterprise in a few years' time. Their models point to revenue growing by 20.8% a year over the next three years and profit margins easing from 13.5% today to 11.9%. On those assumptions, earnings are expected to reach US$3.5b by about 2029, compared with US$2.3b today, which implies an earnings increase of roughly US$1.2b. That consensus view sits between a bullish case of US$4.2b of profit and a more cautious US$3.1b, so there is already a wide range of outcomes embedded in the numbers you see.
Targa Resources' narrative projects US$29.5b revenue and US$3.5b earnings by 2029. This requires 20.8% yearly revenue growth and an earnings increase of about US$1.2b from US$2.3b today.
On valuation, the analyst framework assumes that if those 2029 earnings arrive, the stock would trade on a P/E of 24.4x, slightly below the current 25.7x multiple but still well above the 12.3x level cited for the wider US oil and gas industry. The consensus price target of US$325.14 sits 16.9% above the recent US$270.31 share price and is built on that US$29.5b revenue and US$3.5b earnings profile by 2029, using a discount rate around 7.2% to 7.24%. For you as an income focused holder, the key is not the target itself but whether the revenue compounding, margin drift and earnings step up described here feel realistic when lined up against the project slate and balance sheet that underpin Targa Resources' growing dividend.
Uncover why Targa Resources' fair value indicates an 8% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$228 to US$548 per share, so some private investors see Targa Resources as close to current pricing while others assume far richer outcomes. You are weighing those views against real risks around overbuilding midstream capacity and heavy capex that could strain future cash generation.
Explore 2 other Targa Resources fair value estimates, including one that suggests as much as 25% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Targa Resources research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Targa Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Targa Resources' overall financial health at a glance.
Looking For More Ideas Beyond Targa Resources?
If you like Targa Resources but want a wider watchlist of potential opportunities, the Simply Wall St Screener can help you find other companies with characteristics that match your income, quality or risk appetite.
- If you want resilient balance sheets and cleaner financial profiles, start with a list of solid balance sheet and fundamentals (25 results) that aims to keep debt and funding risk in check.
- For those hunting for value opportunities backed by quality fundamentals, scan a 27 high quality undervalued stocks that filters for stronger cash flows and healthier balance sheets.
- If your priority is dependable cash returns, review a 5 dividend fortresses that focuses on higher yields paired with more robust underlying businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com