
Keppel DC REIT (SGX:AJBU) Rallies On Stronger Results As Valuation Still Looks Undemanding
Keppel DC REIT: Earnings-triggered move
Keppel DC REIT (SGX:AJBU) released nine month 2026 figures that caught investors' attention, with distribution per unit up 11.7%, distributable income up 16.7%, and revenue growth supported by acquisitions and rental reversions.
The earnings release landed alongside a sharp 1-day share price gain of about 3.9% to SG$2.13. However, the 90-day share price return is still down 5.33% and the 1-year total shareholder return has declined 5.87%, while the 3-year total shareholder return of 47.87% points to stronger longer term momentum that recent weakness has only partly cooled.
Capitalize on the earnings-driven interest in Keppel DC REIT by scanning a curated 55 AI infrastructure stocks that could benefit from similar data centre and digital infrastructure trends.Keppel DC REIT’s latest jump could be investors catching up to stronger operations, or just a short burst of optimism after a weak year. The valuation helps indicate which explanation may be more significant.
Price-to-Earnings of 13.2x: Is it justified?
On valuation, Keppel DC REIT trades on a P/E of 13.2x, which points to a cheaper entry point than many peers given where the SG$2.13 unit price sits today.
The P/E ratio compares what you pay for each SG$1 of current earnings. For a data centre focused REIT like Keppel DC REIT, that lens matters because investors usually care about how much they are paying for relatively predictable rental income rather than aggressive expansion stories.
Here, the trust appears to offer value on several fronts. Its 13.2x P/E is lower than the estimated fair P/E of 14.4x, which suggests the market may be assigning a more conservative multiple compared with this fair ratio.
Against wider yardsticks, the discount is even clearer. The same 13.2x multiple sits below the peer average of 17.2x and below the Global Specialized REITs industry average of 15.1x, which indicates investors are pricing Keppel DC REIT more conservatively than similar listed landlords.
Explore the SWS fair ratio for Keppel DC REIT.
Result: Price-to-Earnings of 13.2x (UNDERVALUED)
Still, the Keppel DC REIT story can be knocked off course by weaker net income trends or by any slowdown in data centre leasing demand.
Find out about the key risks to this Keppel DC REIT narrative.
Another view on Keppel DC REIT’s value
The P/E points to value, but the SWS DCF model adds another angle. On that framework, Keppel DC REIT units at SG$2.13 trade about 14% below an estimated future cash flow value of SG$2.48. That raises a simple question for investors: Is the market too cautious about those future cash flows?
Look into how the SWS DCF model arrives at its fair value.
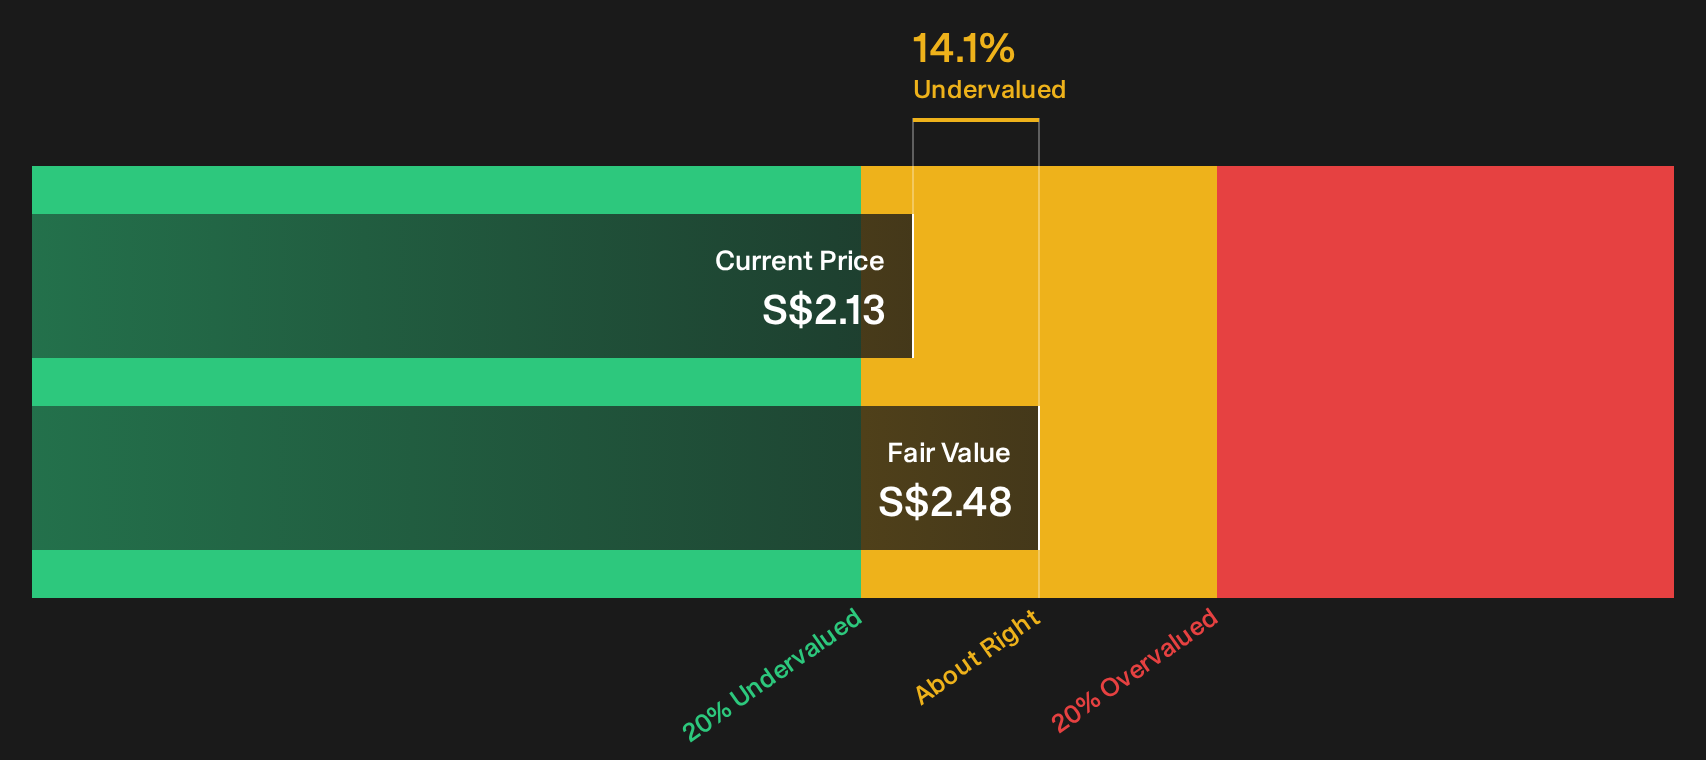
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Keppel DC REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Keppel DC REIT so far, with both concerns and bright spots in play, make this a moment to move quickly and test your own view using the balance of 6 key rewards and 3 important warning signs
Looking for more Keppel DC REIT style investment ideas?
If you like what Keppel DC REIT brings to your watchlist, do not stop here. Use the tools available and expand your opportunity set.
- Target resilient compounding potential by screening for companies with strong earnings and attractive valuations using the 192 high quality undervalued stocks.
- Focus on stability and sleep-better-at-night resilience by running a 221 resilient stocks with low risk scores that filters for businesses with healthier profiles.
- Hunt for tomorrow's quiet standouts by scanning a 615 high quality undiscovered gems before the wider market pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com