
Suncor Energy (TSX:SU) Could Be 28% Undervalued As Buybacks Draw Fresh Attention
Recent commentary around Suncor Energy (TSX:SU) has zeroed in on two linked moves. The group is selling offshore assets and leaning harder into buybacks, which refocuses attention on what investors are really paying for its future cash flows.
Recent price action shows that momentum in Suncor Energy is building, with a 30 day share price return of 16.10% feeding into a 77.58% year to date gain. The 1 year total shareholder return of 105.68% and 3 year total shareholder return of 177.60% reflect how buybacks and asset sales are contributing to long term outcomes.
Scan beyond Suncor Energy and size up other potential value ideas moving on earnings and buyback stories with our hand picked 2 high quality undervalued stocks.
Suncor Energy now trades at a modest discount to analyst targets and at a deeper gap to some fair value estimates. Is that a safety margin, or a signal that the market doubts the recent repositioning?
Most Popular Narrative: 4% Overvalued
Against a last close of CA$111.18, the most followed narrative pegs Suncor Energy’s fair value at about CA$107.35, which frames that recent rally as slightly ahead of the underlying cash flow story.
The multi decade plan to shift production toward standardized in situ projects, including a targeted 400,000 barrels per day portfolio at around $30,000 of capital per flowing barrel, positions Suncor Energy to focus future capital on barrels that currently produce higher cash flow per barrel, which can support margins and long term earnings.
See why 108 investors see Suncor Energy as 4% overvalued.
Result: Fair Value of CA$107.35 (OVERVALUED)
Still, the narrative around Suncor Energy depends on revenue not declining more quickly than forecast and on the market accepting a higher future P/E multiple.
Find out about the key risks to this Suncor Energy narrative.
Another View: Cash Flow Model Paints Suncor Energy As Underpriced
That 4% overvalued narrative is only one lens. Our DCF model, which values Suncor Energy on projected cash flows, points to a fair value of about CA$154.12 per share versus the current CA$111.18. On that math, the stock trades at roughly a 28% discount. Which story do you trust more: price or cash flows?
Look into how the SWS DCF model arrives at its fair value.
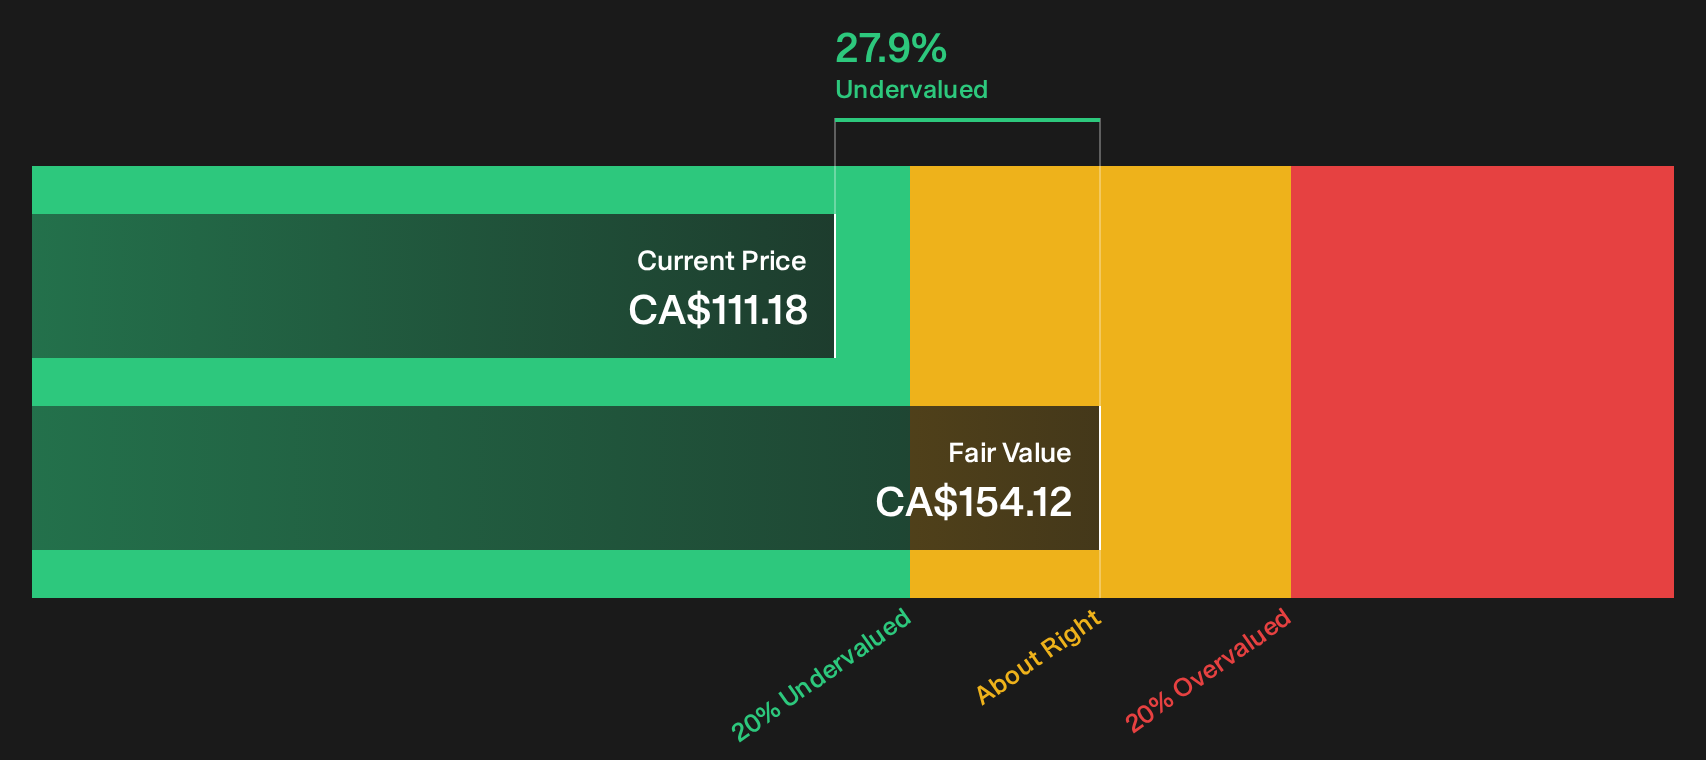
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Suncor Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in Suncor Energy's valuation story. If you want to move past headlines and sentiment, pull up the numbers yourself and weigh both sides of the argument. For a concise snapshot of the balance between optimism and concern, review the 2 key rewards and 2 important warning signs
Looking for more ideas beyond Suncor Energy?
Do not stop at Suncor Energy. Use this momentum to scan fresh opportunities, compare quality, and pressure test your thesis against other potential winners on your radar.
- Target potential mispricings and widen your watchlist by reviewing the 2 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by focusing on a 8 resilient stocks with low risk scores.
- Hunt for future standouts before they hit the spotlight by running through the 9 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com