
Is ON Semiconductor (ON) Reasonable Or Stretched After Its 50% Run?
ON Semiconductor has delivered a 50.3% total return over the past 5 years, and fresh headlines around its silicon carbide technology keep pushing the story forward. That kind of track record raises a straightforward question for you as a shareholder or potential buyer: whether the current price around US$72 reflects the cash the business is expected to generate.
- The 50.3% 5 year gain puts real money behind the question of whether ON Semiconductor's current valuation is fully supported by its projected cash flows or leans more on optimism.
- The adoption of onsemi's EliteSiC power module by Sungrow for utility scale energy storage suggests future demand that can influence revenue visibility, margin structure, and the timing of free cash flow.
- Prefer to judge ON Semiconductor on earnings? See why ON Semiconductor's 44.6x P/E tells a different valuation story.
The issue now is whether ON Semiconductor's recent share price level is justified by what a Discounted Cash Flow (DCF) view of its future cash generation implies.
If you want a clear comparison point for ON Semiconductor's story around cash generation and energy transition demand, it can help to line it up against 42 power grid technology and infrastructure stocks
Is ON Semiconductor Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) approach here looks at the cash ON Semiconductor could return to shareholders over time and discounts it back to today. Latest twelve month free cash flow sits at about $1.1b, and the model assumes this builds to higher annual levels by 2030, which points to a business expected to grow its cash generation rather than tread water.
Those projections line up with a market valuation that already prices in that expansion, with the DCF output broadly in line with the current share price of $72.25. Because Sungrow’s adoption of onsemi’s EliteSiC power module links the company directly to large scale energy storage projects, this kind of pipeline helps explain why the market is comfortable valuing ON Semiconductor near the level implied by its projected cash flows. Find out what ON Semiconductor could be worth using our Discounted Cash Flow (DCF) estimate.
The ON Semiconductor Narrative: What Would Justify Today's Price?
ON Semiconductor’s valuation puzzle only really makes sense once you spell out the stories that could pull the stock meaningfully above or below today’s price, and that is what Simply Wall St Narratives on the Community page aim to clarify. Each scenario ties ON Semiconductor's potential value to a specific mix of growth, margins and earnings risks, so you can track which version of the future appears to be gaining ground over time.
One of the top community narratives on ON Semiconductor: 31% undervalued
"The main requirement for this thesis is continued execution on the shift to differentiated power and sensing platforms..."
Discover why this Narrative puts ON Semiconductor at 31% undervalued.
One more angle on ON Semiconductor that is easy to miss
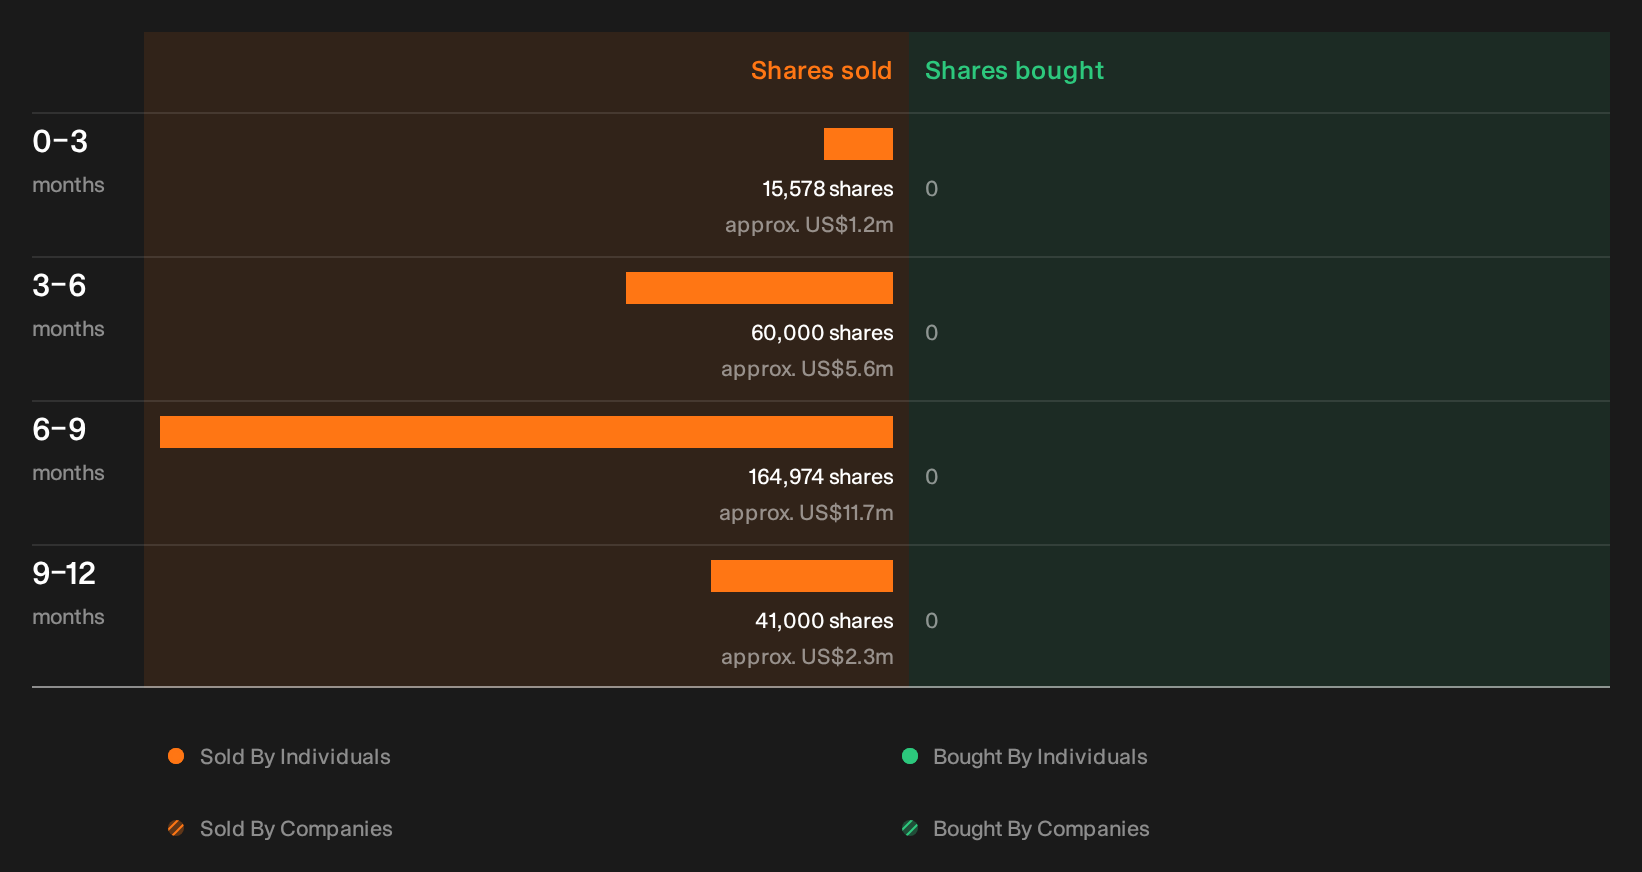
Price and cash flow tell only part of the ON Semiconductor story, because recent trades by people inside the business have been flagged and the who, how much and why are still for you to unpack. See the recent insider selling flagged for ON Semiconductor.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com