
A. O. Smith (AOS) Could Be 12% Overvalued Even After Its 6% Dividend Lift
A. O. Smith (AOS) just approved a 6% lift in its quarterly cash dividend to $0.38 per share, a move that lands as investors question its recent earnings momentum.
Recent trading tells a mixed story. A. O. Smith’s share price has gained 6.8% over the past month and 4.1% across the last week, yet it remains down 9.8% year to date, while the 1 year total shareholder return has fallen 8.5%. This points to fading momentum as concerns around softer sales trends, lower earnings per share and a forward P/E of 15.5x keep sentiment cautious despite the dividend increase.
Look beyond A. O. Smith’s pressured earnings story and identify other businesses where pricing, quality and balance sheets still align in your favor with the curated 27 high quality undervalued stocks.
Dividend income just went up while the share price performance and a 15.5x forward P/E keep A. O. Smith on the back foot. Is this the moment to commit, or to wait for a cheaper entry before earnings reset again?
Most Popular Narrative: 12% Overvalued
A. O. Smith last closed at $61.65 while the most followed narrative, according to Brunhilde_Wagner, pegs fair value closer to $55. That gap frames the current dividend move as a sweetener layered on top of what is seen as a fully valued share price rather than a bargain.
AOS manufactures water heaters and boilers in North America, with a secondary business in China that is in structural decline. The North American franchise is genuinely strong: three players control 90%+ of the market, the product is a non-discretionary emergency replacement in 80%+ of cases, and prices have risen above inflation for twelve consecutive years. The company generates around $550M in free cash flow annually against a market capitalisation of roughly $8B, has paid a growing dividend for 34 consecutive years, and has reduced its share count nearly 10% over five years.
See why 3 investors see A. O. Smith as 12% overvalued.
Result: Fair Value of $55 (OVERVALUED)
Still, the heat pump mandate and a drawn out China review could unsettle A. O. Smith holders if profit visibility or distribution strength start to look weaker.
Find out about the key risks to this A. O. Smith narrative.
Another View on A. O. Smith's Valuation
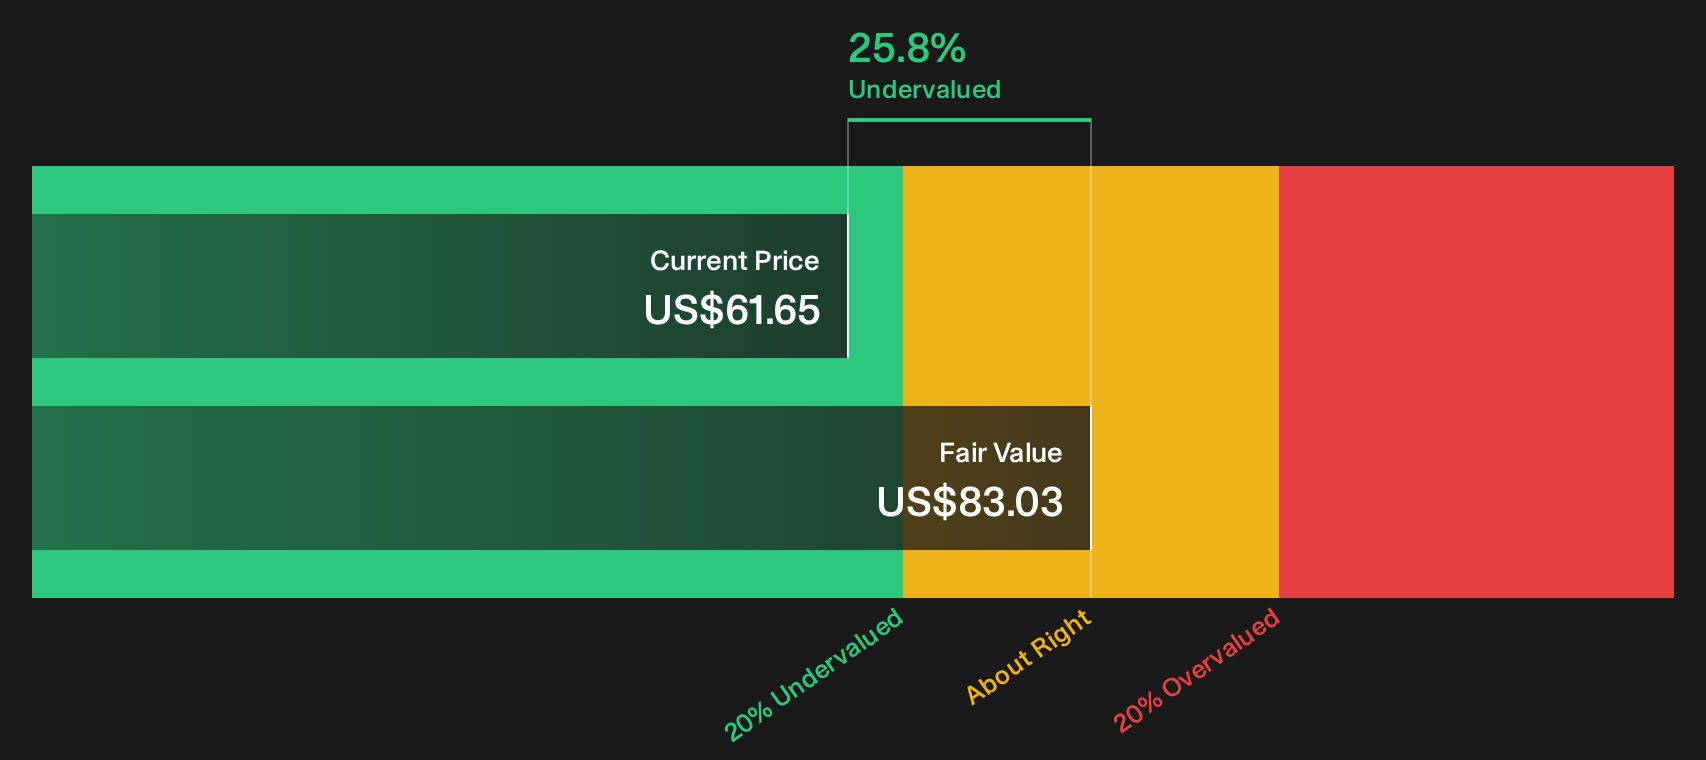
While the leading narrative tags A. O. Smith as roughly 12% overvalued around $61.65 versus a $55 fair value, the SWS DCF model points in the opposite direction. On that framework, the stock trades near $61.65 against an estimated future cash flow value of $83.03, which screens as undervalued. Which lens do you trust more when real cash flows and sentiment disagree?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Conflicted by the split signals around A. O. Smith’s price and dividend story. Move quickly, review the underlying drivers yourself, then weigh them against the 4 key rewards.
Looking for more A. O. Smith sized ideas?
If A. O. Smith has you rethinking where your next dollar goes, use this moment to refresh your watchlist before the market moves without you.
- Target resilient performers with stronger downside protection by scanning 30 resilient stocks with low risk scores that might better match your comfort with volatility.
- Hunt for quality at a discount through the curated 21 high quality undiscovered gems that many investors are not watching yet.
- Anchor your portfolio with dependable cash generators by reviewing the income focused 5 dividend fortresses that can complement more growth oriented ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com