
Aramark (ARMK) Is Getting Fresh Attention, So What Is The Market Weighing?
Aramark (ARMK) is back in focus after fresh analysis compared its recent multi year contract wins and cash flow outlook with an updated estimate of fair value that differs from the current share price.
Recent trading tells a mixed story. Aramark’s share price has eased over shorter windows, with 7 day and 30 day share price returns of 4.9% and 5.8% respectively. In contrast, a year to date share price return of 43.7% and a 5 year total shareholder return of 111.3% point to momentum that has built over a longer horizon as investors weigh fresh contract wins against questions about how current expectations align with fair value.
Spot under followed contract driven stories like Aramark by scanning our hand picked list of 21 high quality undiscovered gems before your watchlist feels out of date.Bulls point to Aramark’s multiyear contract wins and 98% client retention. Bears focus on the DCF work that suggests the stock trades above estimated fair value. Which side does the current valuation support?
Most Popular Narrative: 23% Undervalued
Aramark’s most followed narrative pegs fair value at $68.50 using a 9.49% discount rate, compared with the last close at $52.56. This puts the spotlight firmly on whether contract wins and new verticals can bridge that gap.
The launch and ramp of Nexus, with three AI data center hospitality sites expected to contribute roughly US$400m to US$500m of annualized revenue in fiscal 2027 and 2028 at above company margins and low capital intensity, points to a new earnings stream that can support both margin expansion and free cash flow.
See why 3 investors see Aramark as 23% undervalued.
Result: Fair Value of $68.50 (UNDERVALUED)
Still, Aramark’s story can change quickly if reputational issues in corrections or persistently weak free cash flow make long term contract wins less valuable than they look today.
Find out about the key risks to this Aramark narrative.
Another View: Aramark Looks Expensive On Earnings
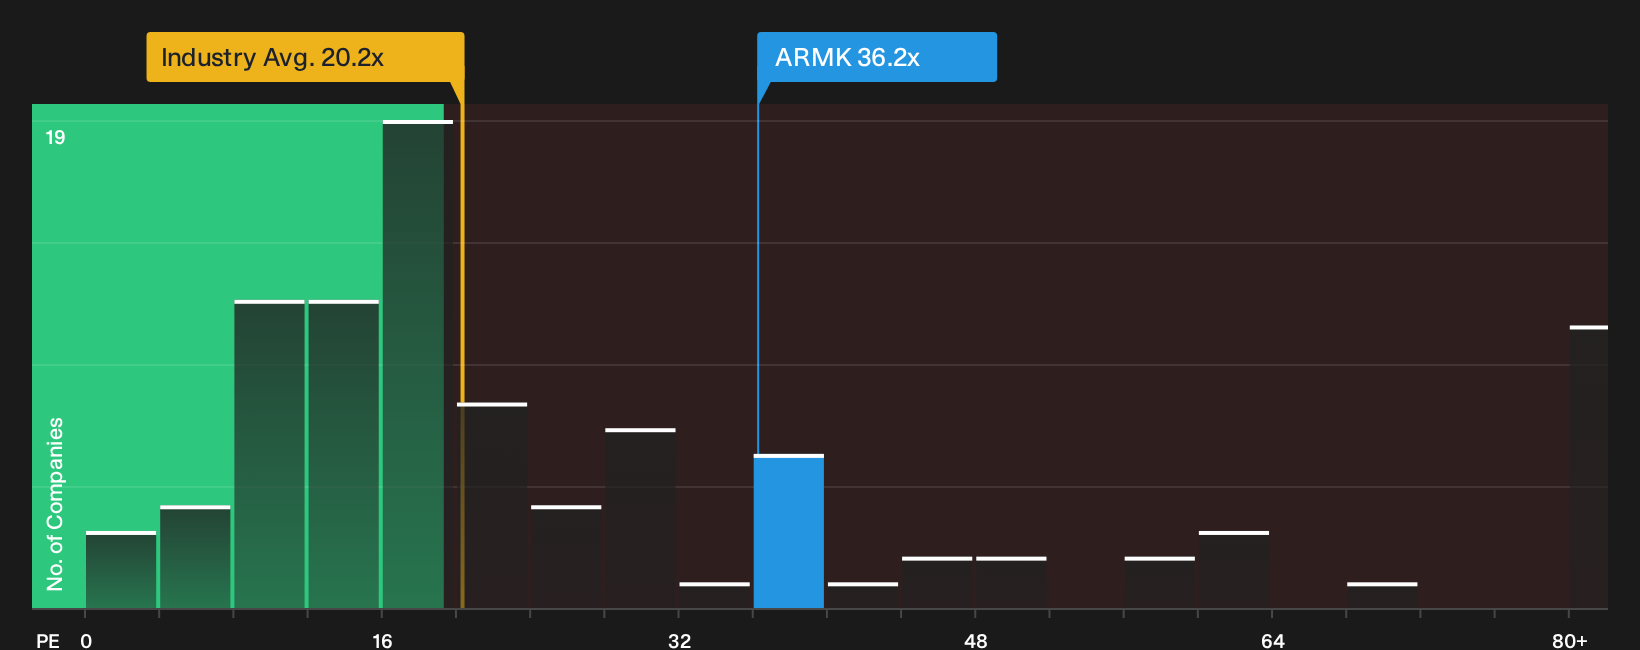
On the flip side, Aramark screens as pricey on earnings. The shares trade on a P/E of 36.2x, while the fair ratio is 24.8x and the US Hospitality group sits near 20.5x, with peers around 19.7x. That kind of gap raises a simple question: How much optimism is already in the price?
To see how this earnings based view stacks against a more detailed fair value estimate, take a closer look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Aramark’s valuation and contract story can feel hard to reconcile, so review the numbers yourself, move quickly, and weigh both sides through 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Aramark?
If Aramark has sharpened your focus on valuation and quality, do not stop here. Use fresh screeners to pressure test your next few additions.
- Target resilience first and scan 30 resilient stocks with low risk scores to help keep volatility in check while you focus on the bigger picture.
- Hunt for mispriced potential and review the 27 high quality undervalued stocks that pair quality fundamentals with a market price that has not fully caught up.
- Prioritize financial staying power and filter through the list of solid balance sheet and fundamentals (25 results) before capital chases the next crowded story without you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com