
Fast Retailing (TSE:9983) Extends North America Momentum, Is The Premium Already Priced In?
Why Fast Retailing’s North America surge matters now
Fast Retailing (TSE:9983) is back in focus after its Uniqlo brand reported a 34.6% sales jump in North America for the latest fiscal year, contributing to a 16.6% overall annual gain.
That North American surge is landing at a time when Fast Retailing’s share price has climbed 11.72% over the past month and 32.70% year to date. Total shareholder return of 38.80% over one year and 216.99% over five years points to momentum that long term holders have already experienced.
Scan how Fast Retailing’s momentum compares across global retailers by reviewing our curated 14 high quality undervalued stocks that also pair strong cash flows with solid balance sheets.
Fast Retailing’s sharp share price move and strong recent North America sales leave investors with a simple tension: lean into the current price, or wait and hope the valuation offers a cleaner entry later on.
Preferred P/E of 42.9x for Fast Retailing: Is it justified?
Fast Retailing last closed at ¥75,880, and the valuation question circles around a P/E of 42.9x that sits well above several benchmarks.
The P/E ratio compares the current share price to annual earnings per share and reflects what investors are willing to pay for each unit of profit. For a retailer like Fast Retailing, which reported earnings growth of 25.3% over the past year and 19.4% per year over five years, a richer multiple often signals that the market is assigning a premium to its profit track record and expectations.
That premium is not small. The P/E of 42.9x is more than double the peer average of 18.1x and more than three times the JP Specialty Retail industry average of 13.1x. It also sits far above the estimated fair P/E of 28.9x, which is a level the market could move towards if sentiment cools or earnings do not keep pace with the current price.
Explore the SWS fair ratio for Fast Retailing.
Result: Price-to-earnings of 42.9x (OVERVALUED)
Still, any earnings stumble or slower consumer demand in key regions could quickly challenge the premium P/E that Fast Retailing currently commands.
Find out about the key risks to this Fast Retailing narrative.
Another view on Fast Retailing’s valuation
The P/E story paints Fast Retailing as expensive, and the SWS DCF model also points to a stretched price. At ¥75,880, the stock trades above an estimated future cash flow value of ¥41,785.63. Both lenses lean the same way, so where does a potential buyer find comfort.
Look into how the SWS DCF model arrives at its fair value.
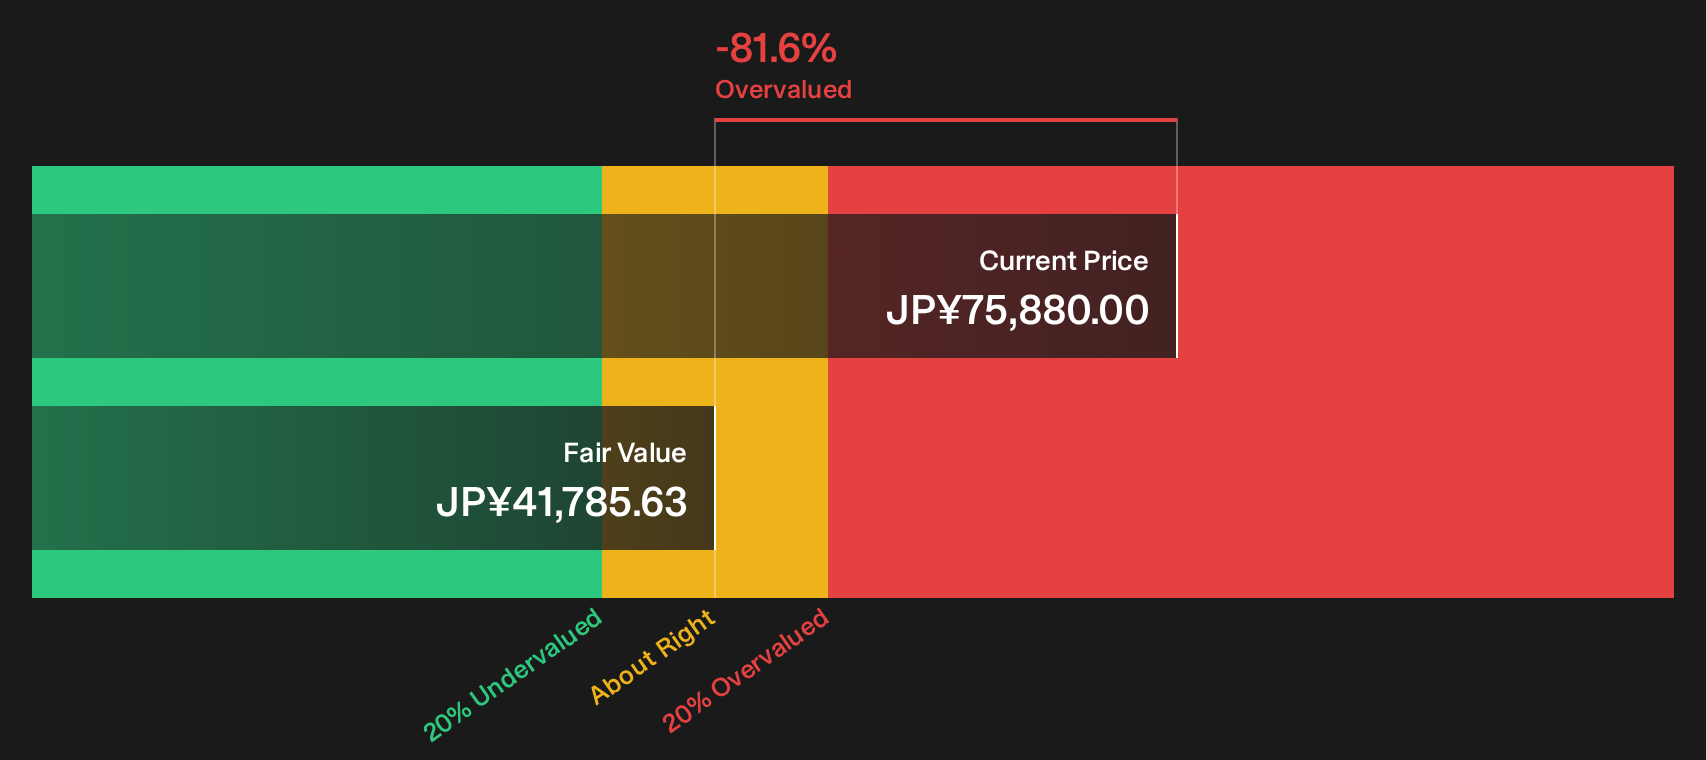
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fast Retailing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
These mixed signals around Fast Retailing can feel confusing, especially with both risks and bright spots in play. Move quickly, review the underlying metrics, and weigh the balance of 2 key rewards and 1 important warning sign
Looking for more Fast Retailing sized opportunities?
If Fast Retailing has sharpened your appetite for ideas, do not stop here. Cast a wider net now or risk missing the next standout opportunity.
- Target resilient compounding potential by focusing on high quality businesses that look cheap on fundamentals through our 14 high quality undervalued stocks.
- Prioritise peace of mind with companies that pair sturdy finances and conservative risk profiles using the 22 resilient stocks with low risk scores.
- Spot tomorrow’s potential leaders early by scanning lesser known businesses with solid metrics via the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com