
Stille (OM:STIL) Q3 Earnings Spotlight Margin Gains And Cash Flow
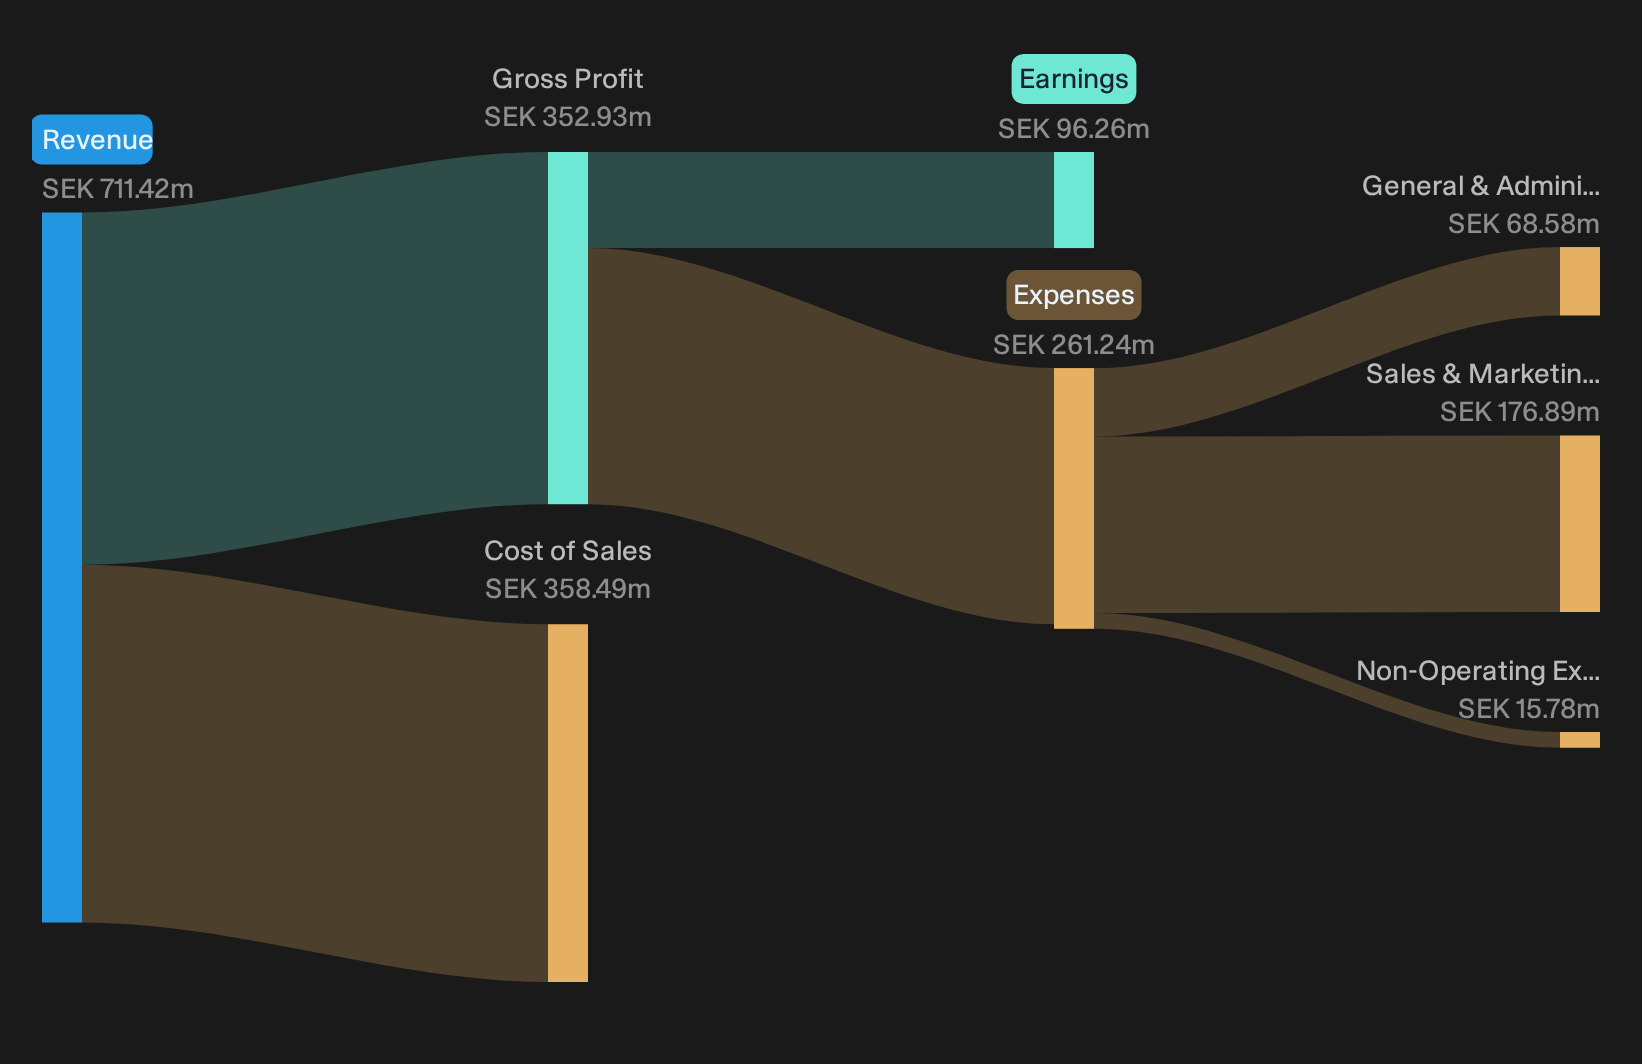
Stille just reported Q3 2026, and the story is all about margins and cash, not the share price. The stock closed at SEK257.5 after a flat short term stretch, while the business itself printed a SEK34m operating cash inflow and an EBIT margin before nonrecurring items of 14.4%.
Traders saw another steady day. Fundamental investors saw something different. Revenue reached SEK170.6m and gross margin touched 49.9%. The emotional read is muted, yet the numbers point to a quarter where profitability and cash generation did the heavy lifting.
Love Stille’s near 50% gross margin and solid operating cash inflow but want a broader set of high quality cash generators in your watchlist too? Compare it against our list of solid balance sheet and fundamentals stocks (205 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): SEK170.6m vs SEK138.8m (up about 23%)
- Net Income, excl. extra items (Q3 2026 vs Q3 2025): SEK24.5m vs SEK0.9m (very large increase, more than 7x higher)
- Basic EPS (Q3 2026 vs Q3 2025): SEK2.73 vs SEK0.10 (very large increase, more than 25x higher)
- EBIT Margin before nonrecurring items (Q3 2026 vs Q3 2025): 14.4% vs 12.5% (margin higher year on year)
Table sales are up about 30% so far this year. Ask Charlie what’s driving Stille’s imagiQ3 table momentum.
Stille bull case hinges on premium mix execution
The optimistic story says Stille can turn operational investment into lasting share gains in high value niches. The premium brand push is central to that idea.
"Continued focus on premium brands such as Fehling, S&T and imagiQ3, which have been growing faster than mid single digit market levels, positions Stille to keep increasing its share in higher value products."
Q3 gives some backing. Instruments delivered SEK134m with strong demand in Fehling and S&T, while Tables reached SEK36.8m and lifted EBIT margin to 11.2%. Group gross margin at 49.9% and SEK34m operating cash inflow show the mix and availability efforts are converting into higher quality earnings.
Bear case tests cash quality and tables volatility
Skeptics worry that recent strength in Stille depends on temporary cash and an unusually hot tables cycle, rather than repeatable economics.
"The case rests heavily on the ability of Stille to keep converting strong reported results into sustained cash generation."
Q3 cash flow of SEK34m and 9 month operating cash of SEK91.2m are flattered by tariff refunds of SEK5.2m classified as nonrecurring items. Management also flags that roughly 30% year to date growth in Surgical Tables is extraordinary and that capital equipment revenue is lumpy, so the current SEK36.8m quarter and 11.2% tables EBIT margin may not be a clean run rate.
One Narrative disagrees with today's price. → See where this Narrative says Stille should trade.
Hunt For Quiet Cash Engines
Stille just showed how a solid quarter and a flat share price can pull in different directions. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 31% below our estimate - builds long term infrastructure service contracts that shift earnings toward recurring, high cash conversion work across essential assets.
- Company 2 - 22% below our estimate - channels rising semiconductor investment into higher margin service and aftermarket activity as chipmakers lock in critical equipment support.
- Company 3 - 27% below our estimate - lifts earnings power by pushing through higher project fees and tightening billing ratios on energy, water and security focused design work.
Those are three of them. See every one of the 194 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com