
Peabody Energy (BTU) Stock Looks Fully Valued Against Its Sales Base
Peabody Energy shares have retreated in recent months after a strong multi year run, which puts fresh focus on a simple question for investors who care about fundamentals. Is the current US$22.89 price still aligned with what the business is generating through its sales?
- Over the past 5 years the stock has gained 101.9%, so anyone looking at Peabody Energy today is effectively being asked to pay far more for the same stream of coal related revenue than they were several years ago.
- Freedom Broker’s recent idea on Peabody Energy points to higher output at the Centurion mine and supportive coal pricing, which can feed directly into future sales levels and influence how much investors are prepared to pay for each dollar of revenue.
- The analysts covering Peabody Energy have run their own numbers. See what analysts think Peabody Energy's shares could be worth.
The issue now is whether Peabody Energy’s current share price is appropriately grounded in the scale and quality of its sales base.
If you want a wider set of ideas built around similar valuation questions, start your research with our screener of 29 high quality undervalued stocks.
Is Peabody Energy Getting Expensive on Sales?
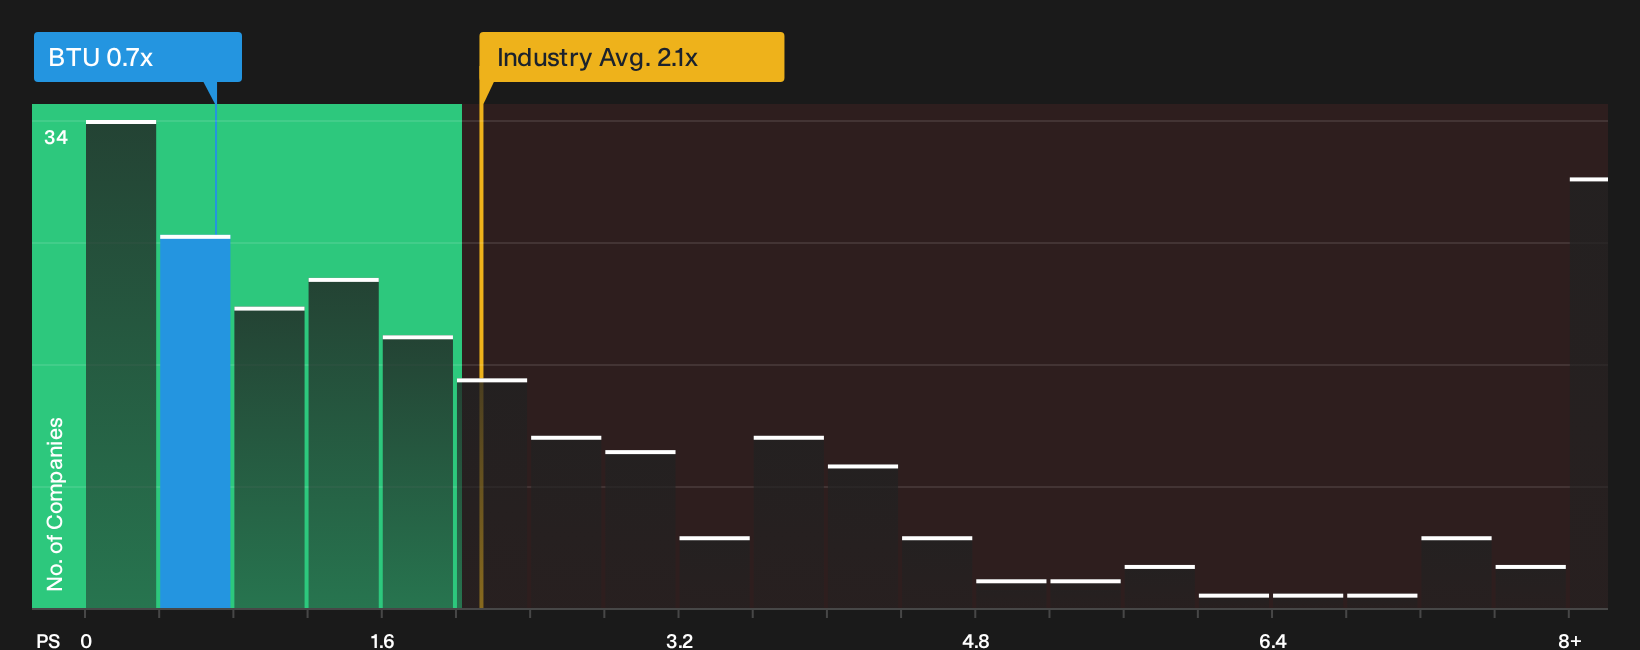
P/S is a clean way to look at Peabody Energy because coal producers can see earnings move around more than revenue. At the current share price, Peabody Energy trades on a P/S of about 0.7x, which is well below the Oil and Gas industry average of roughly 2.1x and the peer group level near 3.7x.
The in house fair multiple, which factors in Peabody Energy’s sector, risk profile and business quality, also sits above the current 0.7x reading. As a result, the stock screens overvalued relative to that tailored benchmark even though it looks inexpensive against broad industry numbers. Despite Freedom Broker flagging potential benefits from higher Centurion mine output and supportive coal pricing, the P/S ratio already reflects enough value that investors may want to consider how durable current revenue conditions are before expecting further upside on this metric. Explore the numbers behind Peabody Energy's P/S valuation.
The Peabody Energy Narrative: What Would Justify Today's Price?
Peabody Energy’s Narratives on Simply Wall St pick up where the P/S puzzle leaves off, explaining what kind of revenue trends, margin profile and earnings path would need to occur for the shares to be worth significantly more or less than today’s level. Instead of stopping at a single valuation output, they break down the future that figure is based on so you can keep checking whether Peabody Energy’s real world performance is matching those assumptions over time.
One of the top community narratives on Peabody Energy: 28% undervalued
"The main requirement is a successful Centurion ramp-up to the targeted low-cost, long-life production profile, while Peabody manages commissioning issues…"
Discover why this Narrative puts Peabody Energy at 28% undervalued.
One more piece of the Peabody Energy puzzle before you move on
Price to sales tells you what you are paying for Peabody Energy’s current turnover, but analyst roadmaps for the next few years give a different lens on what that tag might be pointing toward. Explore where analysts expect Peabody Energy to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com